

Company Coverage
Ratch Group (RATCH TB): 3Q26: Earnings Rebound; Growth Story Intact
BUY (Maintained)
Current price:
Target price:
Upside:
Bt36.50
Bt44.00
20.55%
Analyst
Highlights
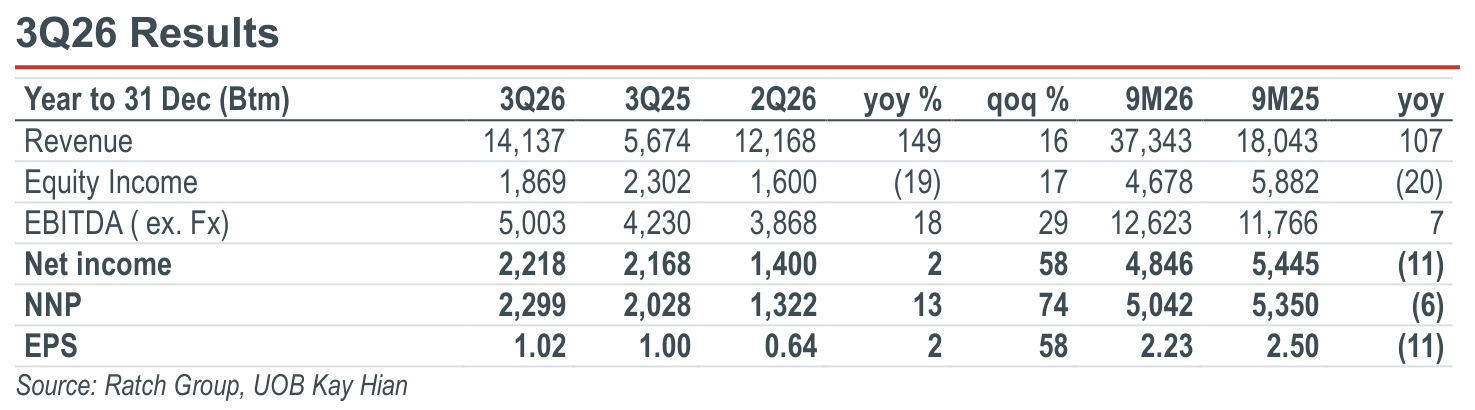
- RATCH reported 3Q26 net profit of Bt2.22b (+2% yoy, +58% qoq) and normalised profit of Bt2.30b (+13% yoy, +74% qoq), driven by stronger power plant operations.
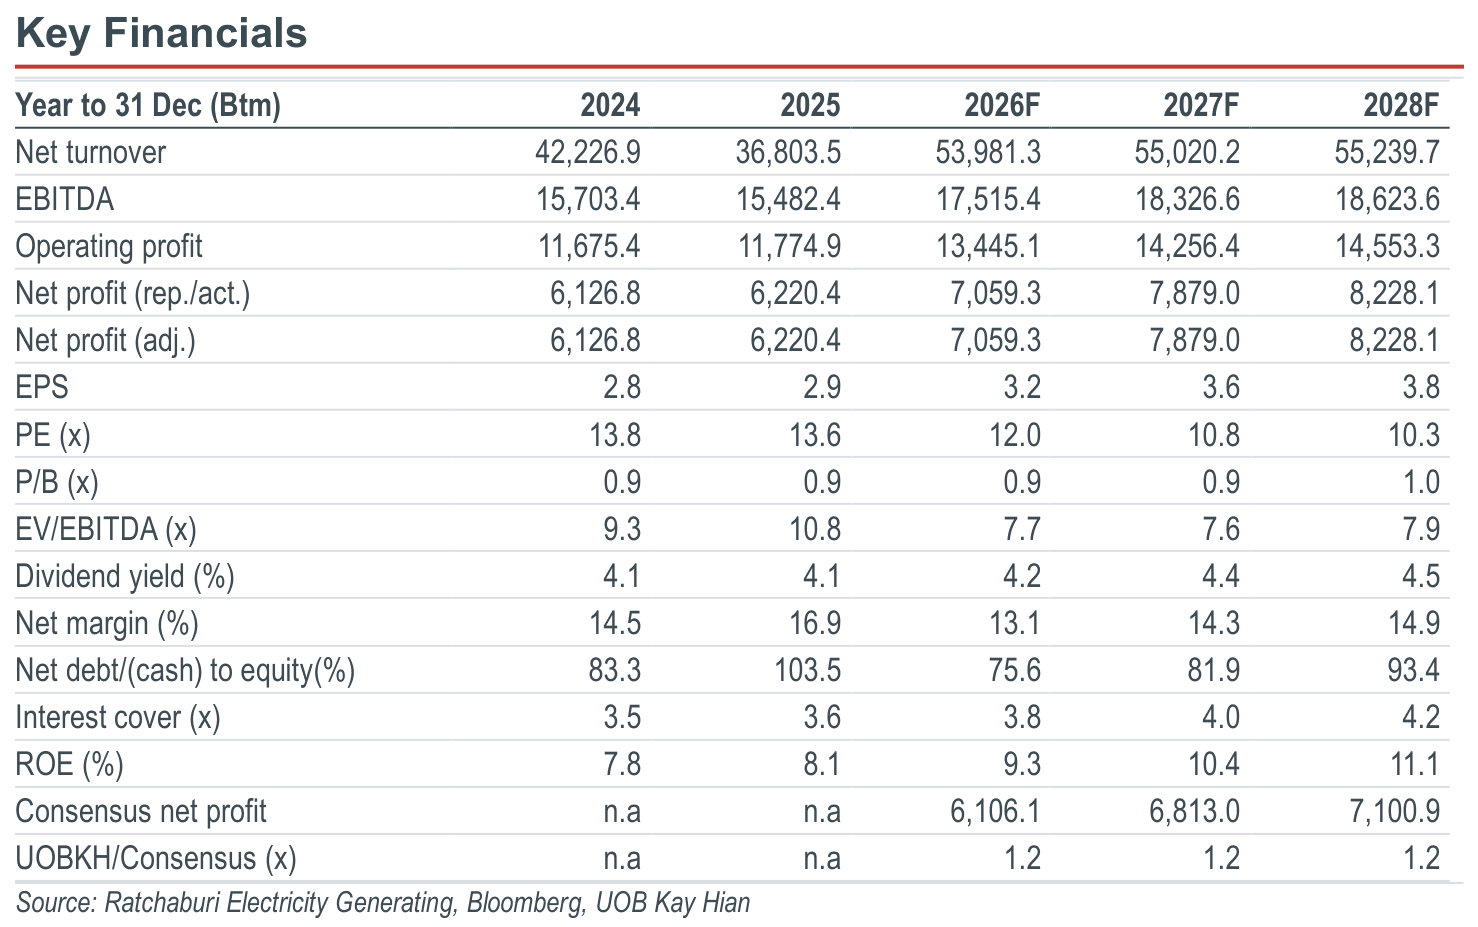
- We expect earnings to remain resilient in 4Q26-2027.
- Maintain BUY with a 2027F target price of Bt44.00.
Analysis
- Strong earnings recovery as expected. RATCH Group (RATCH) reported 3Q26 net profit of Bt2.22b (+2% yoy, +58% qoq) and normalised profit of Bt2.30b (+13% yoy, +74% qoq), driven by stronger power plant operations. Both core and net profit were in line with our estimate. This brought 9M26 core profit to Bt5.04b, accounting for 71% of our full-year forecast.
- HKP led the earnings recovery. Availability of Hin Kong Power Plant (HKP) improved significantly to 99.1% from 88.1% in 2Q26 following the completion of scheduled maintenance, while dispatch reached 98.2%, driving a 12.5% qoq increase in electricity sales volume. Hongsa Power Plant (HPC) also maintained strong operations above Bt700m, despite weak seasonal factors, with availability of 91.5% and EGAT dispatch of 106.8%. Meanwhile, Paiton benefitted from improved plant availability and higher earnings, up 7% yoy and 6% qoq to Bt673m despite RATCH’s reduced ownership stake.
Highlights
- RATCH reported 3Q26 net profit of Bt2.22b (+2% yoy, +58% qoq) and normalised profit of Bt2.30b (+13% yoy, +74% qoq), driven by stronger power plant operations.
- We expect earnings to remain resilient in 4Q26-2027.
- Maintain BUY with a 2027F target price of Bt44.00.
Analysis
- Strong earnings recovery as expected. RATCH Group (RATCH) reported 3Q26 net profit of Bt2.22b (+2% yoy, +58% qoq) and normalised profit of Bt2.30b (+13% yoy, +74% qoq), driven by stronger power plant operations. Both core and net profit were in line with our estimate. This brought 9M26 core profit to Bt5.04b, accounting for 71% of our full-year forecast.
- HKP led the earnings recovery. Availability of Hin Kong Power Plant (HKP) improved significantly to 99.1% from 88.1% in 2Q26 following the completion of scheduled maintenance, while dispatch reached 98.2%, driving a 12.5% qoq increase in electricity sales volume. Hongsa Power Plant (HPC) also maintained strong operations above Bt700m, despite weak seasonal factors, with availability of 91.5% and EGAT dispatch of 106.8%. Meanwhile, Paiton benefitted from improved plant availability and higher earnings, up 7% yoy and 6% qoq to Bt673m despite RATCH’s reduced ownership stake.
BUY (Maintained)
Current price:
Target price:
Upside:
Bt36.50
Bt44.00
20.55%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.

