

Company Coverage
Moshi Moshi (MOSHI TB): Record-high Earnings, Record-low Valuation
BUY (Maintained)
Current price:
Target price:
Upside:
Bt35.50
Bt50.00
26.31%
Analyst
Highlights
- The tone from our Asian Gems Conference was neutral, with near-term earnings facing pressure from external factors, while the long-term outlook remains promising.
- MOSHI increased its market share to 60.5% in 2025 and continued to aggressively expand new stores.
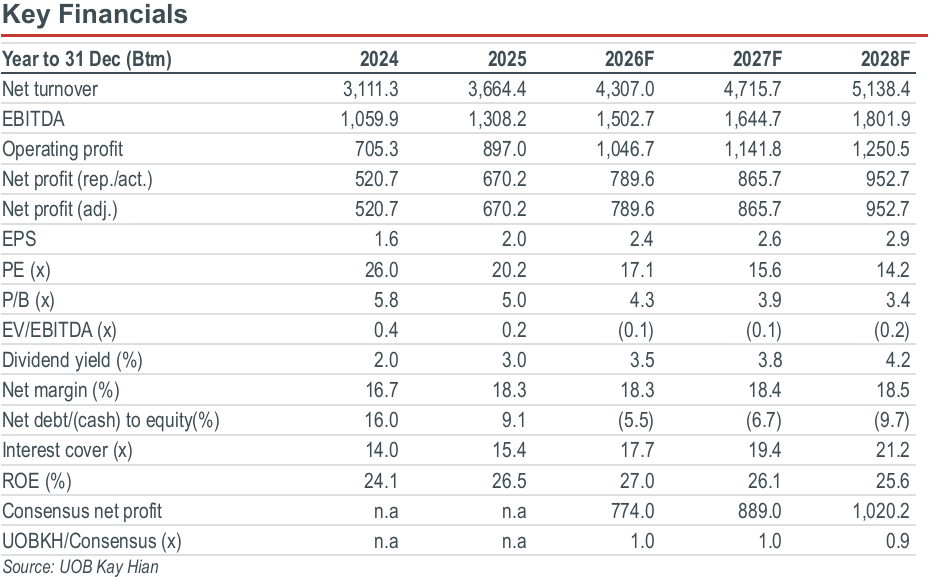
- Maintain BUY. Target price is Bt50.00. The share price is trading at 14.5x PE, close to its historical trough, which we view as a reasonable entry point.
Analysis
- Neutral tone from Asian Gems Conference. Moshi Moshi’s (MOSHI) management was a key speaker at our Asian Gems Conference. Management struck a neutral tone, while maintaining a positive long-term outlook.
- Management continues to focus on quality growth, with key priorities on improving sales productivity, maintaining margins, developing new products, and increasing customer engagement. MOSHI targets 35 new stores per year, mainly in upcountry markets where there remains significant whitespace and limited competition. Some locations remain underserved as competitors lack sufficient scale to operate profitably and offer competitive pricing. At least five of the new stores will be standalone formats, mainly in provincial cities where MOSHI can become a key shopping destination.
- Market share winner. MOSHI increased its market share to 60.5% in 2025 and continued to aggressively expand new stores despite intensifying competition. The competitors’ key challenge remains understanding local consumer behavior and achieving strong product-market fit. Management believes its local consumer insights, product development capabilities, and scale remain key advantages over smaller competitors.
- Oversea expansion remains at the early stage, with MOSHI assessing potential markets across Southeast Asia, eg Malaysia or Indonesia. The potential model would be a JV with local partners, leveraging their expertise in location selection, consumer understanding, and supply-chain management. Management expects to see more tangible progress over the medium term.
Highlights
- The tone from our Asian Gems Conference was neutral, with near-term earnings facing pressure from external factors, while the long-term outlook remains promising.
- MOSHI increased its market share to 60.5% in 2025 and continued to aggressively expand new stores.
- Maintain BUY. Target price is Bt50.00. The share price is trading at 14.5x PE, close to its historical trough, which we view as a reasonable entry point.
Analysis
- Neutral tone from Asian Gems Conference. Moshi Moshi’s (MOSHI) management was a key speaker at our Asian Gems Conference. Management struck a neutral tone, while maintaining a positive long-term outlook.
- Management continues to focus on quality growth, with key priorities on improving sales productivity, maintaining margins, developing new products, and increasing customer engagement. MOSHI targets 35 new stores per year, mainly in upcountry markets where there remains significant whitespace and limited competition. Some locations remain underserved as competitors lack sufficient scale to operate profitably and offer competitive pricing. At least five of the new stores will be standalone formats, mainly in provincial cities where MOSHI can become a key shopping destination.
- Market share winner. MOSHI increased its market share to 60.5% in 2025 and continued to aggressively expand new stores despite intensifying competition. The competitors’ key challenge remains understanding local consumer behavior and achieving strong product-market fit. Management believes its local consumer insights, product development capabilities, and scale remain key advantages over smaller competitors.
- Oversea expansion remains at the early stage, with MOSHI assessing potential markets across Southeast Asia, eg Malaysia or Indonesia. The potential model would be a JV with local partners, leveraging their expertise in location selection, consumer understanding, and supply-chain management. Management expects to see more tangible progress over the medium term.
BUY (Maintained)
Current price:
Target price:
Upside:
Bt35.50
Bt50.00
26.31%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
