

Company Coverage
Delta (Thailand) (DELTA TB) : 3Q26 Results Preview: Earnings Expected To Improve qoq, Driven By Higher Sales And Margins
BUY (Maintained)
Current price:
Target price:
Upside:
Bt263.00
Bt300.00
14.4%
Analyst
Analyst
Sirithat Prasertwuti
Sirithat@uobkh.co.thHighlights
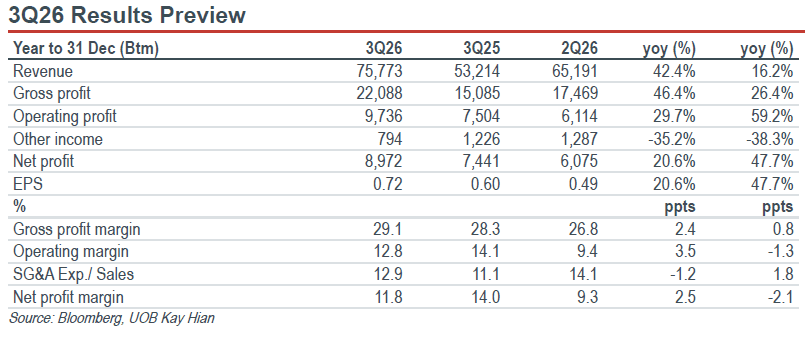
We expect DELTA to report a 3Q26 net profit of Bt8.97b (+21% yoy, +48% qoq), improving significantly qoq from a low base.
Sales are expected to remain strong, especially during the high season, while gross margin could recover qoq.
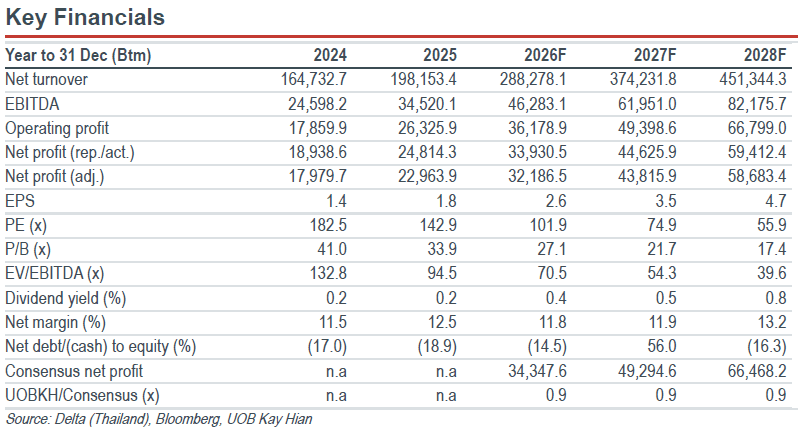
Maintain BUY with an unchanged target price of Bt300.00. We believe the valuation has already priced in the weak gross margin from the latest earnings.
Analysis
Earnings are expected to improve qoq, driven by higher sales and margin recovery. We maintain our view that 2Q26 earnings are likely to be the lowest quarterly level of the year, reflecting several negative factors during the quarter, including inventory provision, raw material shortages and an unusual product mix. For 3Q26, we expect Delta (Thailand) (DELTA) to report a net profit of Bt8.97b (+21% yoy, +48% qoq). The yoy increase is expected to come from continued data centre demand, while the qoq improvement should come from a recovery from the 2Q26 low base. Sales could reach Bt75.77b (+42% yoy, +16% qoq), reflecting some order shifts from 2Q26, the high season sales, and improved order fulfilment.
- Gross margin is projected to recover qoq in 3Q26 from a low base. We expect gross margin to recover qoq to 29.1% in 3Q26 (vs 31.2% in 1Q26 and 26.3% in 2Q26), driven by a better product mix compared with 2Q26, a lower rush order level and the absence of inventory provisions in our assumption.
Highlights
We expect DELTA to report a 3Q26 net profit of Bt8.97b (+21% yoy, +48% qoq), improving significantly qoq from a low base.
Sales are expected to remain strong, especially during the high season, while gross margin could recover qoq.
Maintain BUY with an unchanged target price of Bt300.00. We believe the valuation has already priced in the weak gross margin from the latest earnings.
Analysis
Earnings are expected to improve qoq, driven by higher sales and margin recovery. We maintain our view that 2Q26 earnings are likely to be the lowest quarterly level of the year, reflecting several negative factors during the quarter, including inventory provision, raw material shortages and an unusual product mix. For 3Q26, we expect Delta (Thailand) (DELTA) to report a net profit of Bt8.97b (+21% yoy, +48% qoq). The yoy increase is expected to come from continued data centre demand, while the qoq improvement should come from a recovery from the 2Q26 low base. Sales could reach Bt75.77b (+42% yoy, +16% qoq), reflecting some order shifts from 2Q26, the high season sales, and improved order fulfilment.
- Gross margin is projected to recover qoq in 3Q26 from a low base. We expect gross margin to recover qoq to 29.1% in 3Q26 (vs 31.2% in 1Q26 and 26.3% in 2Q26), driven by a better product mix compared with 2Q26, a lower rush order level and the absence of inventory provisions in our assumption.
BUY (Maintained)
Current price:
Target price:
Upside:
Bt263.00
Bt300.00
14.4%
Analyst
Analyst
Sirithat Prasertwuti
Sirithat@uobkh.co.thIMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.

