

Company Coverage
Berli Jucker (BJC TB): Site Visit Takeaways: Strong Glass And Retail Recovery
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Bt18.00
Bt21.00
16.67%
Bt18.00
Analyst
Highlights
- We organised a site visit for institutional clients to BJC’s glass factory and the new Big C DC, and came back with a bullish view.
- Packaging earnings are set to reach a decade-high, while Big C’s SSSG should turn positive for the first time since 1Q25. MMVN performance was also stronger than expected.
- Maintain BUY with a higher target price of Bt21.00 (from Bt18.00). Our 2027 earnings forecast is 13% above consensus, driven by cost saving initiatives.
Analysis
- Came back from the site visit with a bullish view. We organised a site visit for institutional clients to Berli Jucker’s (BJC) glass factory and the Big C new distribution centre (DC) in Bang Pa-in. The visit reinforced our positive view, with both businesses showing solid operational momentum.
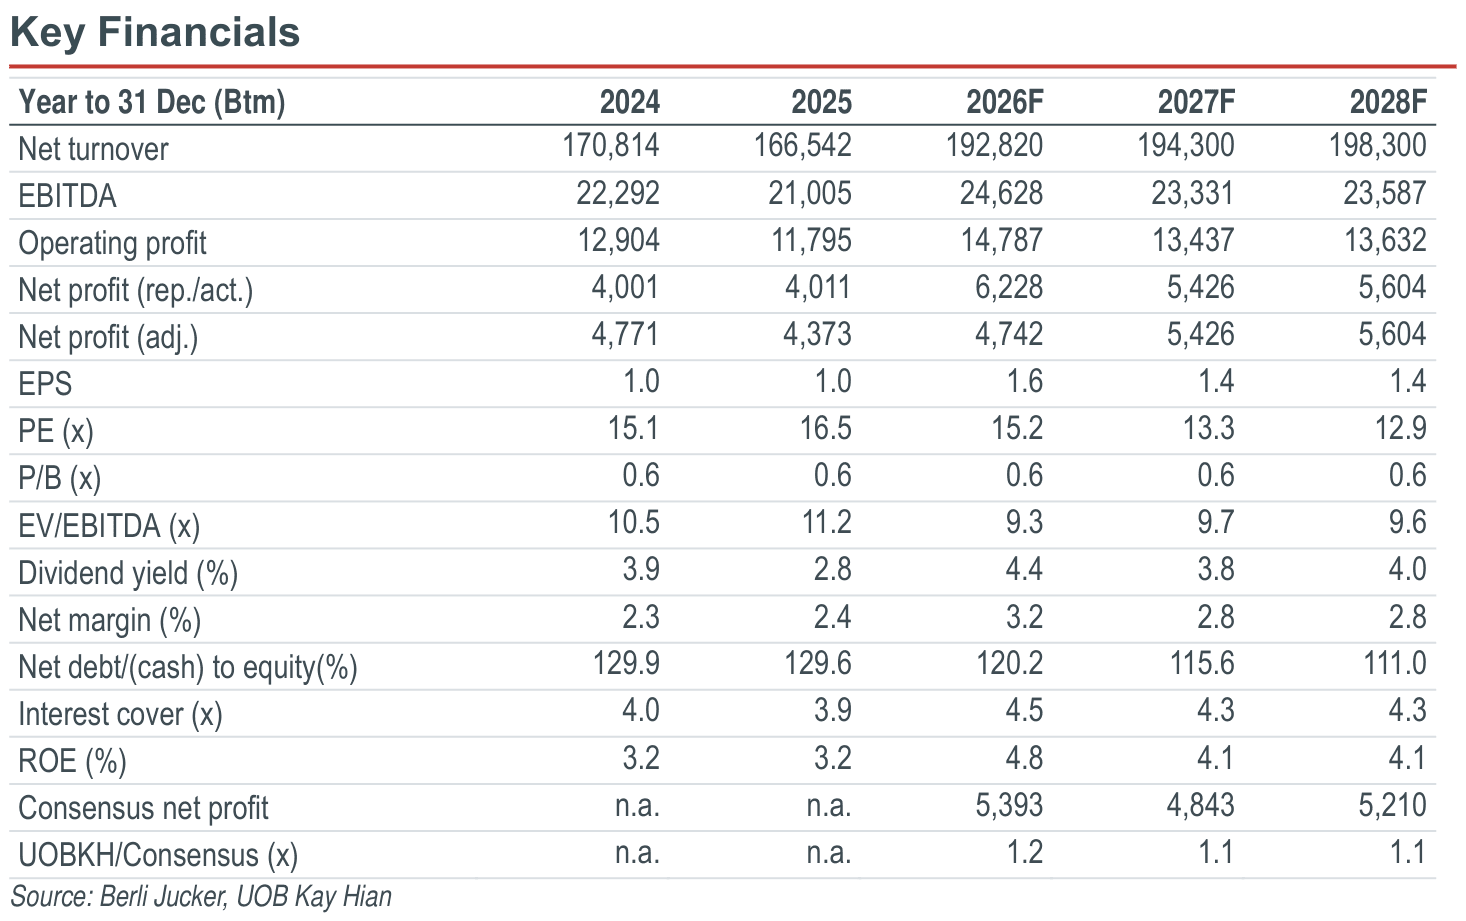
- Our new 2027 earnings forecast is 13% above consensus. We raise our 2027 core profit forecast by 7%, driven by three key factors: a) cost savings initiatives, as one-off expenses may be incurred in 2H26 but should generate significant savings from 2027 onwards, which we believe are not yet reflected in market perception; b) Big C recovery, with 3Q26 SSSG expected to turn positive for the first time since 1Q25; and c) stronger-than-expected MM Mega Market Vietnam (MMVN) performance.
- Glass business: Best performance in the past decade. BJC’s glass factory is the largest glass production facility in Southeast Asia. After discussions with the glass business’ management, we remain confident in its 2H26 outlook. Orders from both existing and new customers remain strong, supported by stronger demand and production disruptions at two key competitors. This has allowed BJC to gain market share across various product categories. We see BJC’s strong customer relationships and cost leadership as key advantages in winning new orders. Meanwhile, its existing customer, Thai Beverage, continues to gain market share in both alcohol and non-alcohol beverages, supporting demand. As a result, the factory continues to operate at full capacity, similar to 2Q26. We expect glass gross margin to expand yoy in 3Q26, driven by operating leverage and lower raw material costs, which should more than offset higher natural gas costs. Overall, we expect the glass business to remain a key earnings driver throughout 2H26.
Highlights
- We organised a site visit for institutional clients to BJC’s glass factory and the new Big C DC, and came back with a bullish view.
- Packaging earnings are set to reach a decade-high, while Big C’s SSSG should turn positive for the first time since 1Q25. MMVN performance was also stronger than expected.
- Maintain BUY with a higher target price of Bt21.00 (from Bt18.00). Our 2027 earnings forecast is 13% above consensus, driven by cost saving initiatives.
Analysis
- Came back from the site visit with a bullish view. We organised a site visit for institutional clients to Berli Jucker’s (BJC) glass factory and the Big C new distribution centre (DC) in Bang Pa-in. The visit reinforced our positive view, with both businesses showing solid operational momentum.
- Our new 2027 earnings forecast is 13% above consensus. We raise our 2027 core profit forecast by 7%, driven by three key factors: a) cost savings initiatives, as one-off expenses may be incurred in 2H26 but should generate significant savings from 2027 onwards, which we believe are not yet reflected in market perception; b) Big C recovery, with 3Q26 SSSG expected to turn positive for the first time since 1Q25; and c) stronger-than-expected MM Mega Market Vietnam (MMVN) performance.
- Glass business: Best performance in the past decade. BJC’s glass factory is the largest glass production facility in Southeast Asia. After discussions with the glass business’ management, we remain confident in its 2H26 outlook. Orders from both existing and new customers remain strong, supported by stronger demand and production disruptions at two key competitors. This has allowed BJC to gain market share across various product categories. We see BJC’s strong customer relationships and cost leadership as key advantages in winning new orders. Meanwhile, its existing customer, Thai Beverage, continues to gain market share in both alcohol and non-alcohol beverages, supporting demand. As a result, the factory continues to operate at full capacity, similar to 2Q26. We expect glass gross margin to expand yoy in 3Q26, driven by operating leverage and lower raw material costs, which should more than offset higher natural gas costs. Overall, we expect the glass business to remain a key earnings driver throughout 2H26.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Bt18.00
Bt21.00
16.67%
Bt18.00
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
