

Company Coverage
Bangkok Expressway and Metro (BEM TB): 3Q26: Results In Line, Reaching A Record High
BUY (Maintained)
Current price:
Target price:
Upside:
Bt6.30
Bt8.50
34.92%
Analyst
Highlights
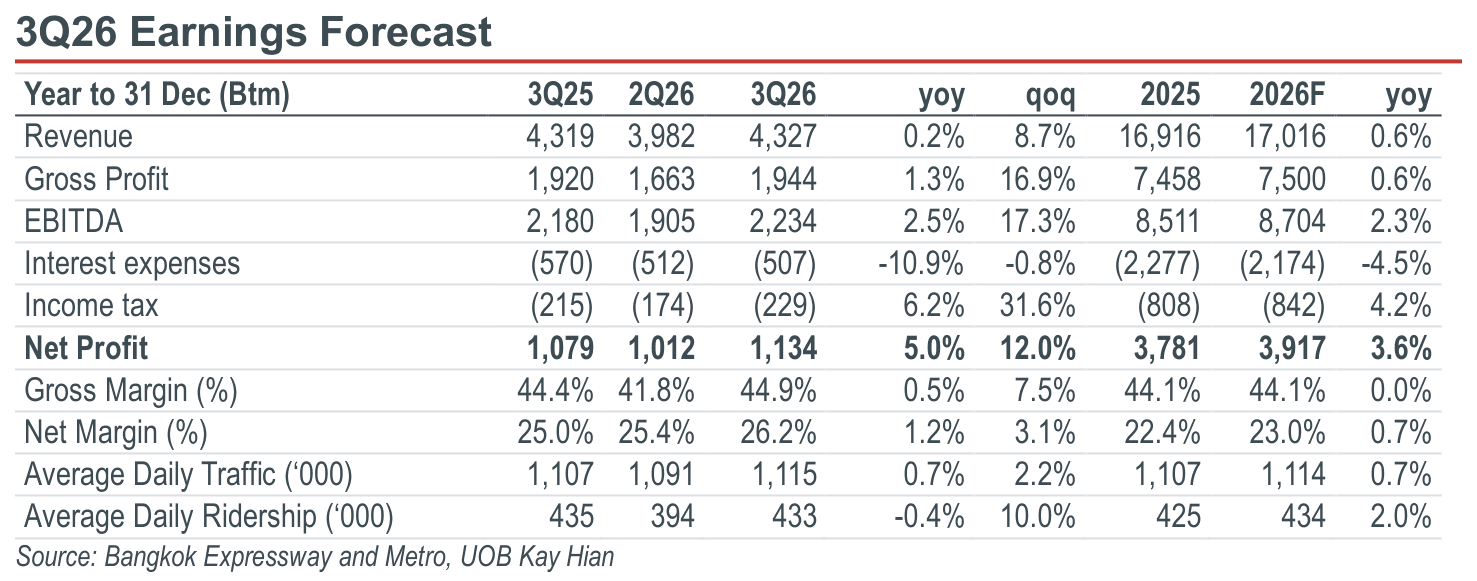
- BEM’s 3Q26 net profit reached a record high of Bt1.1b, +5% yoy, in line with our and consensus estimates.
- Expressway traffic and MRT ridership began to recover in the second half of Oct 26. Our forecast for 7% yoy earnings growth in 4Q26 remains achievable.
- The share price has declined since Aug 26, while fundamentals remain unchanged. We remain positive on BEM's short- to medium-term outlook.
- Maintain BUY with a target price of Bt8.50.
Analysis
- Results in line. Bangkok Expressway and Metro’s (BEM) 3Q26 net profit reached a record high of Bt1.1b (+5% yoy, +12% qoq), in line with our and consensus estimates, mainly supported by lower financial costs and strong rail business. Revenue remained flat yoy, while gross profit increased 1%. By segment, rail was the key growth contributor, with gross profit rising 34% yoy, supported by higher Purple Line O&M revenue and lower maintenance costs. Expressway gross profit declined 4% yoy due to higher amortisation and maintenance-related expenses, while commercial development gross profit fell 6% yoy. In terms of profitability, gross profit margin improved 40bps yoy, while the SG&A-to-revenue increased 28bps to 7.2%. As a result, EBIT remained broadly flat yoy, with lower financial costs providing the key support to net profit growth.
Highlights
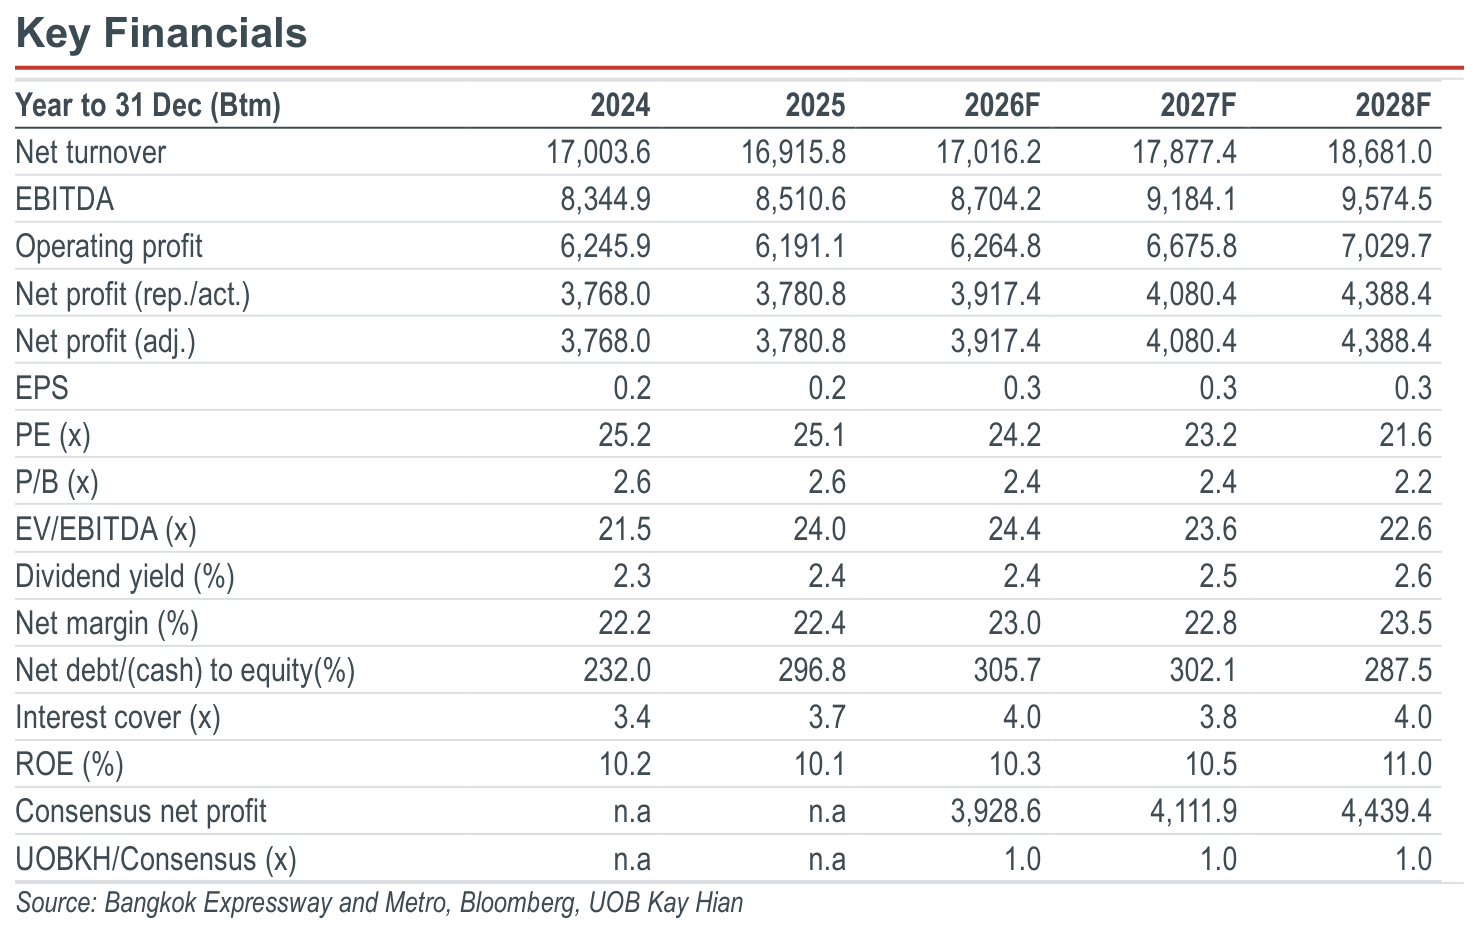
- BEM’s 3Q26 net profit reached a record high of Bt1.1b, +5% yoy, in line with our and consensus estimates.
- Expressway traffic and MRT ridership began to recover in the second half of Oct 26. Our forecast for 7% yoy earnings growth in 4Q26 remains achievable.
- The share price has declined since Aug 26, while fundamentals remain unchanged. We remain positive on BEM's short- to medium-term outlook.
- Maintain BUY with a target price of Bt8.50.
Analysis
- Results in line. Bangkok Expressway and Metro’s (BEM) 3Q26 net profit reached a record high of Bt1.1b (+5% yoy, +12% qoq), in line with our and consensus estimates, mainly supported by lower financial costs and strong rail business. Revenue remained flat yoy, while gross profit increased 1%. By segment, rail was the key growth contributor, with gross profit rising 34% yoy, supported by higher Purple Line O&M revenue and lower maintenance costs. Expressway gross profit declined 4% yoy due to higher amortisation and maintenance-related expenses, while commercial development gross profit fell 6% yoy. In terms of profitability, gross profit margin improved 40bps yoy, while the SG&A-to-revenue increased 28bps to 7.2%. As a result, EBIT remained broadly flat yoy, with lower financial costs providing the key support to net profit growth.
BUY (Maintained)
Current price:
Target price:
Upside:
Bt6.30
Bt8.50
34.92%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.

