

Company Coverage
Reclaims Global (RGL SP) : 1HFY27: Healthy Results; Margins Remain Resilient
BUY (Maintained)
Current price:
Target price:
Upside:
S$0.20
S$0.27
+35.0%
Analyst
Highlights
1HFY27 revenue of S$33.3m and earnings of S$3.8m formed 62% and 56% of our forecasts respectively, driven by stronger demand across all segments.
Its orderbook of S$25m, which comprises mostly earthworks projects, provides earnings visibility through 1H28.
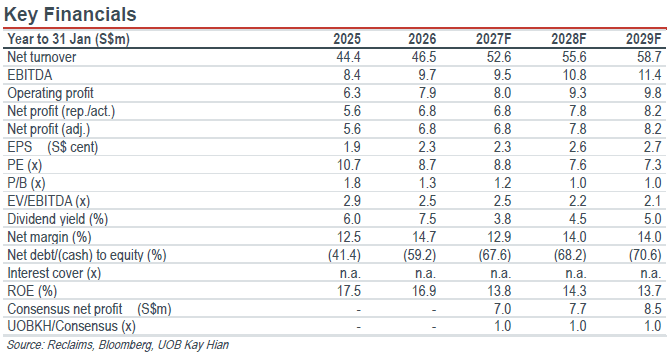
Maintain BUY with an unchanged target price of S$0.27. Reclaims currently trade at 8.8x 2027F PE, representing a 15% discount vs peers.
Analysis
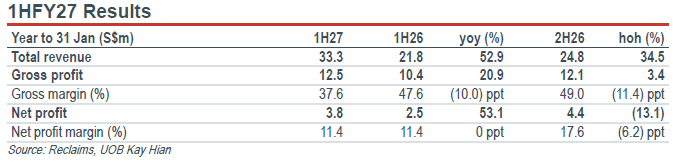
Strong 1HFY27 results; margins remained stable yoy. Reclaims Global (Reclaims) reported 1HFY27 revenue of S$33.3m (+53% yoy), representing 62% of our FY27 forecast. This was largely driven by stronger market demand across all business segments. Net profit of S$3.8m (+53.1% yoy), accounted for 55.7% of our FY27 forecast, underpinned by revenue growth.. Gross margin declined 10ppt yoy to 37.6% (1HFY26:47.6%) largely due to higher diesel prices, while net profit margin remained stable yoy at 11.4%, demonstrating improved operational efficiencies despite the incremental costs arising from higher diesel prices and two property acquisitions. On a hoh basis, revenue grew 34.5% on stronger project demand, but both gross and net margin fell 11.4ppt and 6.2ppt respectively largely due to higher diesel costs.
By segment, excavation services grew 47% yoy to S$24.1m, logistics and leasing services grew 52% yoy to S$7.2m, while recycling more than doubled yoy to S$1.7m. Growth in its key business - excavation services - is expected to remain strong, supported by its current orderbook of around S$25m, consisting of largely earthworks projects and some demolition projects. This also provides earnings visibility through to 1H28.
- Interim dividend declared. Reclaim declared an interim dividend of 25 S cents per share, equivalent to a 20% payout ratio (FY26: 54%). Management reiterated that they are prioritising the maintenance of a sustainable payout while preserving cash amid the current volatile operating environment. The interim dividend also comes after an enlarged share base following the 1:1 bonus issue in Mar 26. This is also supported by a cash balance of S$12.2m
Highlights
1HFY27 revenue of S$33.3m and earnings of S$3.8m formed 62% and 56% of our forecasts respectively, driven by stronger demand across all segments.
Its orderbook of S$25m, which comprises mostly earthworks projects, provides earnings visibility through 1H28.
Maintain BUY with an unchanged target price of S$0.27. Reclaims currently trade at 8.8x 2027F PE, representing a 15% discount vs peers.
Analysis
Strong 1HFY27 results; margins remained stable yoy. Reclaims Global (Reclaims) reported 1HFY27 revenue of S$33.3m (+53% yoy), representing 62% of our FY27 forecast. This was largely driven by stronger market demand across all business segments. Net profit of S$3.8m (+53.1% yoy), accounted for 55.7% of our FY27 forecast, underpinned by revenue growth.. Gross margin declined 10ppt yoy to 37.6% (1HFY26:47.6%) largely due to higher diesel prices, while net profit margin remained stable yoy at 11.4%, demonstrating improved operational efficiencies despite the incremental costs arising from higher diesel prices and two property acquisitions. On a hoh basis, revenue grew 34.5% on stronger project demand, but both gross and net margin fell 11.4ppt and 6.2ppt respectively largely due to higher diesel costs.
By segment, excavation services grew 47% yoy to S$24.1m, logistics and leasing services grew 52% yoy to S$7.2m, while recycling more than doubled yoy to S$1.7m. Growth in its key business - excavation services - is expected to remain strong, supported by its current orderbook of around S$25m, consisting of largely earthworks projects and some demolition projects. This also provides earnings visibility through to 1H28.
- Interim dividend declared. Reclaim declared an interim dividend of 25 S cents per share, equivalent to a 20% payout ratio (FY26: 54%). Management reiterated that they are prioritising the maintenance of a sustainable payout while preserving cash amid the current volatile operating environment. The interim dividend also comes after an enlarged share base following the 1:1 bonus issue in Mar 26. This is also supported by a cash balance of S$12.2m
BUY (Maintained)
Current price:
Target price:
Upside:
S$0.20
S$0.27
+35.0%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.

