

Company Coverage
City Developments (CIT SP): Focus On Portfolio Revamp
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$8.09
S$11.85
46.50%
S$11.50
Analyst
Highlights
- CIT to announce strategic review outcome on 28 Sep 26. We expect the review to deliver clarity on asset monetisation, redevelopment or value-unlocking opportunities. A more optimal capital and long-term value creation discipline should enhance ROE and catalyse share price performance.
- Rolling out Lucerne Grand in Sep/Oct 26. CIT’s Lucerne Grand opened for public preview on 18 September and will be launched in the first week of October. With starting prices from just under S$1.5m/unit, we anticipate the launch to be well received.
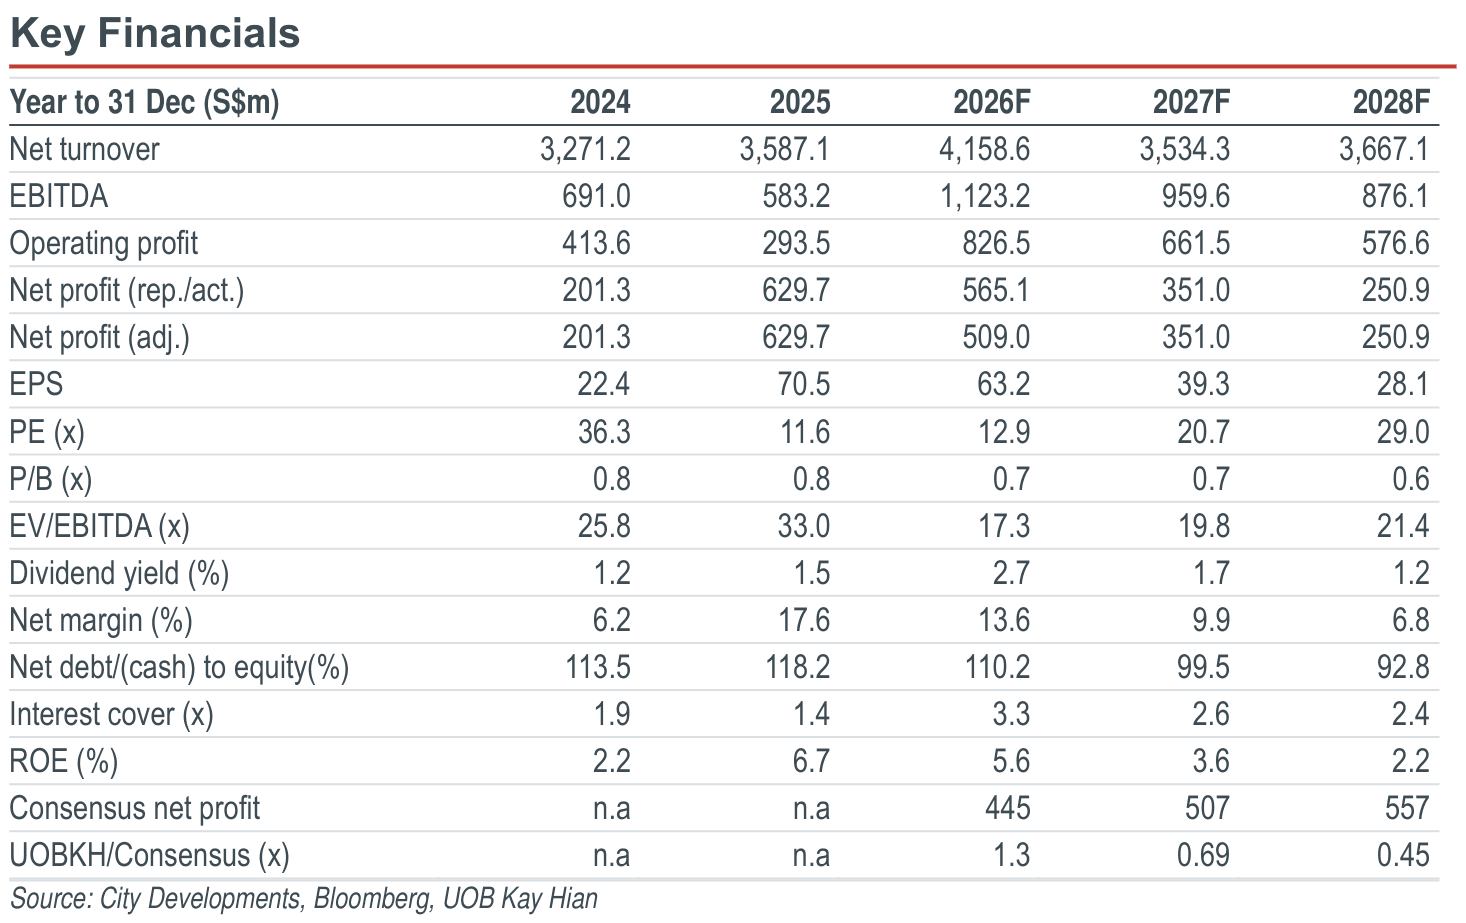
- We raise our RNAV to S$16.92 as we factor in the latest residential land acquisitions and review our assumptions. Accordingly, our target price is lifted to S$11.85, based on a 30% discount to RNAV.
Analysis
- A holistic portfolio re-look. We expect the portfolio review to provide more clarity on opportunities for asset divestments, redevelopment or value-unlocking opportunities. This move should lead to a more disciplined approach towards capital management and long-term value creation, through balance-sheet optimisation and lower net debt-to-equity ratio. The resulting uplift in ROE should likely catalyse share price and narrow the gap to NAV. Further strategies regarding its reinvestment focus and long-term capital allocation could support continued share price performance.
- Potential divestments could include assets in the UK and China. City Developments (CIT) estimates its total asset base (including fair value of investment properties and hotels) at S$36b as at end-1H26. Of this, 41% comprises investment properties, 31% from development properties and 25% from hotels. Potential assets earmarked for sale could include the £800m legacy UK development platform, completed properties such as UK office properties, and China investment properties such as Hong Leong Hongqiao Center and Hong Leong Technology Park. It could also look to unlock value from its global living portfolio (S$3.7b as at end-25) via private funds or REIT platforms, in our view.
Highlights
- CIT to announce strategic review outcome on 28 Sep 26. We expect the review to deliver clarity on asset monetisation, redevelopment or value-unlocking opportunities. A more optimal capital and long-term value creation discipline should enhance ROE and catalyse share price performance.
- Rolling out Lucerne Grand in Sep/Oct 26. CIT’s Lucerne Grand opened for public preview on 18 September and will be launched in the first week of October. With starting prices from just under S$1.5m/unit, we anticipate the launch to be well received.
- We raise our RNAV to S$16.92 as we factor in the latest residential land acquisitions and review our assumptions. Accordingly, our target price is lifted to S$11.85, based on a 30% discount to RNAV.
Analysis
- A holistic portfolio re-look. We expect the portfolio review to provide more clarity on opportunities for asset divestments, redevelopment or value-unlocking opportunities. This move should lead to a more disciplined approach towards capital management and long-term value creation, through balance-sheet optimisation and lower net debt-to-equity ratio. The resulting uplift in ROE should likely catalyse share price and narrow the gap to NAV. Further strategies regarding its reinvestment focus and long-term capital allocation could support continued share price performance.
- Potential divestments could include assets in the UK and China. City Developments (CIT) estimates its total asset base (including fair value of investment properties and hotels) at S$36b as at end-1H26. Of this, 41% comprises investment properties, 31% from development properties and 25% from hotels. Potential assets earmarked for sale could include the £800m legacy UK development platform, completed properties such as UK office properties, and China investment properties such as Hong Leong Hongqiao Center and Hong Leong Technology Park. It could also look to unlock value from its global living portfolio (S$3.7b as at end-25) via private funds or REIT platforms, in our view.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$8.09
S$11.85
46.50%
S$11.50
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
