

Company Coverage
Uzma Group (UZMA MK) : Uzma Ver 4.0: Embracing Resilience In Growth
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
RM0.37
RM0.70
+89.2%
RM0.76
Analyst
Highlights
Foundation for resilient growth established; near-term earnings risks largely priced in. Uzma’s evolution is a success story of its diversification as an energy and technology platform. While its next long-term growth will focus on resilience, we anticipate near-term earnings risk caused by largely industry-wide factors. Seismic contracts may see lower revenue due to dry docking works that were fortunately completed by end-Jul 26. However, on top of the anticipated monsoon season, we understand massive maintenance work suspensions had occurred due to Petronas’ asset ownership transfers.
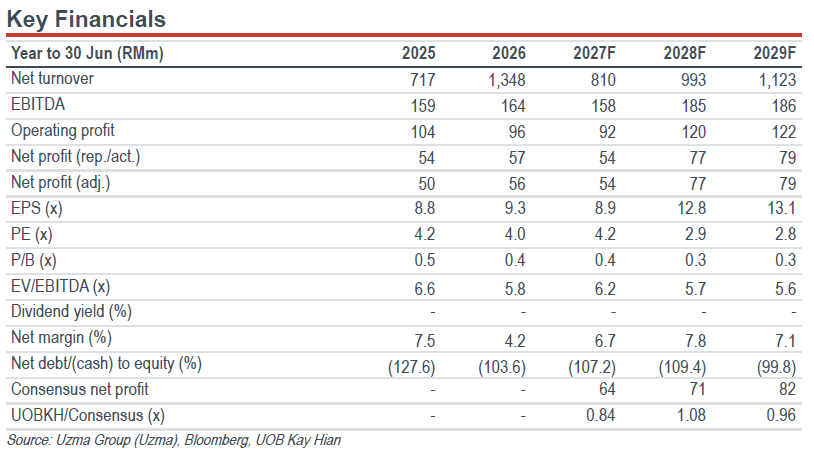
We Retain BUY with an adjusted RM0.70 target price (from RM0.76), at an unchanged 8x PE. Despite cutting our near-term earnings forecasts, we believe the risks are mostly priced in, and advise investors to accumulate the shares which are trading at a forward PE of below 3x. We remain optimistic on its longer-term growth, given that Uzma’s asset-light and nimble business model will likely make it benefit from opportunities from Searah’s creation.
Analysis
The foundation for income diversification has been well established. Uzma Group (Uzma) has evolved over 26 years from its founding in 2000 as an O&G service provider into a diversified energy and technology platform. Through its previous five-year plan, Uzma had been successful in diversifying into non-O&G ventures, building its base of in-house technology and assets that grant long-term income. These assets include water injection facilities (WIF) like MARSYA (first deployed in 2016) and SARA, and the flagship 50MW Large Scale Solar (LSS) project in Kedah.
The next growth is all about building resilience. The second five-year plan effective 2026, appears to be a consolidation phase necessary for the group to resharpen and mature its growth engines to become independent, while continuing to build a higher long-term earnings mix and reoptimise its cost structure. Priority goals for FY27 include securing continuity, embracing operator transition, as well as margin preservation and deleveraging. On deleveraging, Uzma aims to restructure about RM100m of its RM816m loans with financing rates exceeding 7%, vs its blended interest rate of 3.7%.
Highlights
Foundation for resilient growth established; near-term earnings risks largely priced in. Uzma’s evolution is a success story of its diversification as an energy and technology platform. While its next long-term growth will focus on resilience, we anticipate near-term earnings risk caused by largely industry-wide factors. Seismic contracts may see lower revenue due to dry docking works that were fortunately completed by end-Jul 26. However, on top of the anticipated monsoon season, we understand massive maintenance work suspensions had occurred due to Petronas’ asset ownership transfers.
We Retain BUY with an adjusted RM0.70 target price (from RM0.76), at an unchanged 8x PE. Despite cutting our near-term earnings forecasts, we believe the risks are mostly priced in, and advise investors to accumulate the shares which are trading at a forward PE of below 3x. We remain optimistic on its longer-term growth, given that Uzma’s asset-light and nimble business model will likely make it benefit from opportunities from Searah’s creation.
Analysis
The foundation for income diversification has been well established. Uzma Group (Uzma) has evolved over 26 years from its founding in 2000 as an O&G service provider into a diversified energy and technology platform. Through its previous five-year plan, Uzma had been successful in diversifying into non-O&G ventures, building its base of in-house technology and assets that grant long-term income. These assets include water injection facilities (WIF) like MARSYA (first deployed in 2016) and SARA, and the flagship 50MW Large Scale Solar (LSS) project in Kedah.
The next growth is all about building resilience. The second five-year plan effective 2026, appears to be a consolidation phase necessary for the group to resharpen and mature its growth engines to become independent, while continuing to build a higher long-term earnings mix and reoptimise its cost structure. Priority goals for FY27 include securing continuity, embracing operator transition, as well as margin preservation and deleveraging. On deleveraging, Uzma aims to restructure about RM100m of its RM816m loans with financing rates exceeding 7%, vs its blended interest rate of 3.7%.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
RM0.37
RM0.70
+89.2%
RM0.76
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.

