

Company Coverage
Tenaga Nasional (TNB MK): Absorbs RM120m-150m Subsidy For Additional Domestic Users
HOLD (Downgraded)
Current price:
Target price:
Upside:
Previous TP :
RM13.04
RM14.60
+12.3%
RM16.30
Analyst
Highlights
- Contrary to our expectation, Tenaga announced that the group will absorb the RM120m-150m impact from the electricity tariff fuel surcharge exemption for the period Sep-Dec 26.
- Albeit a minimal 2% earnings impact, the decision above is now an overhang on Tenaga’s near-term share price performance – given rising regulatory interference and we are unsure if this will be a one-off.
- Downgrade Tenaga to HOLD with a lowered DCF-fair value of RM14.60. In arriving at our fair value, we have prudently raised our discount rate from 7.8% to 8.2% (incorporating a 100bp increase in risk premium for the stock).
Analysis
- Tenaga shares government’s burden; absorbs subsidy. Contrary to our expectation, Tenaga Nasional (Tenaga) announced last Friday that the group will absorb the RM120m-150m impact from the electricity tariff fuel surcharge exemption for the period Sep-Dec 26. To recap, the RM120m-150m arose as a result of the government expanding electricity bill protection for domestic users from 600kWh to 800kWh.
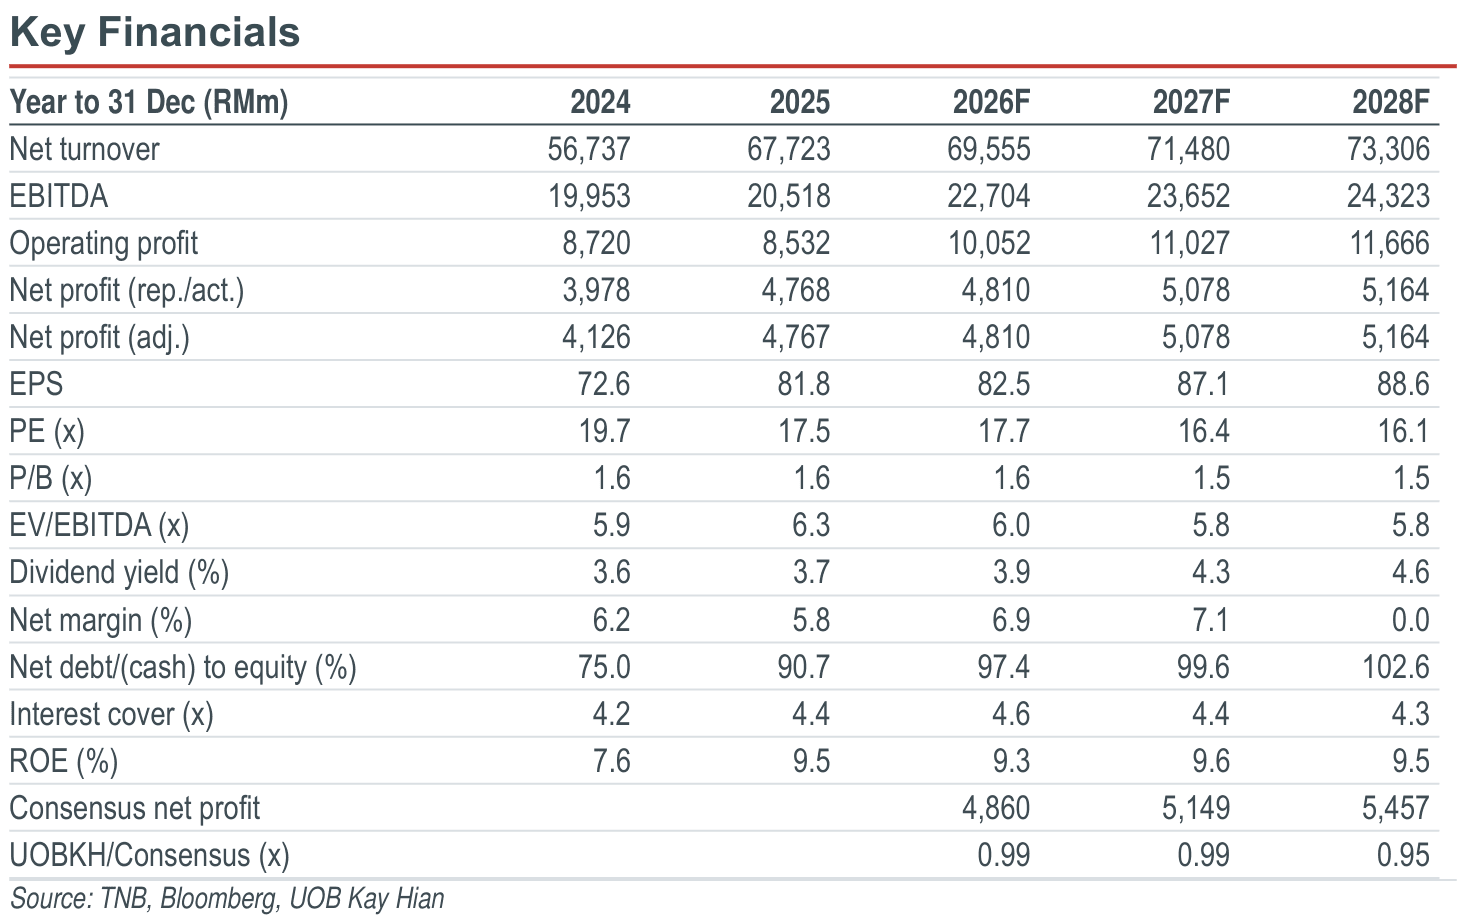
- Negative for Tenaga. Earnings impact is 2% to 2026’s forecast. However, the decision above implies that the Automatic Fuel Adjustment (AFA) mechanism may be subject to government intervention in the near future and we expect investors to gradually discount the sanctity of the Incentive Based Regulation (IBR) and cost pass-through framework.
- Downgrade Tenaga to HOLD, overhang to persist into the near future. As we cannot say with certainty that this is a one-off (there is now an overhang that Tenaga may be asked to absorb the subsidy if Jan-Mar 27 electricity usage remains high), we downgrade Tenaga from BUY to HOLD with a lower DCF-based target price of RM14.60. In arriving at our fair value, we have prudently raised our discount rate from 7.8% to 8.2% (incorporating a 100bp increase in risk premium for the stock).
Highlights
- Contrary to our expectation, Tenaga announced that the group will absorb the RM120m-150m impact from the electricity tariff fuel surcharge exemption for the period Sep-Dec 26.
- Albeit a minimal 2% earnings impact, the decision above is now an overhang on Tenaga’s near-term share price performance – given rising regulatory interference and we are unsure if this will be a one-off.
- Downgrade Tenaga to HOLD with a lowered DCF-fair value of RM14.60. In arriving at our fair value, we have prudently raised our discount rate from 7.8% to 8.2% (incorporating a 100bp increase in risk premium for the stock).
Analysis
- Tenaga shares government’s burden; absorbs subsidy. Contrary to our expectation, Tenaga Nasional (Tenaga) announced last Friday that the group will absorb the RM120m-150m impact from the electricity tariff fuel surcharge exemption for the period Sep-Dec 26. To recap, the RM120m-150m arose as a result of the government expanding electricity bill protection for domestic users from 600kWh to 800kWh.
- Negative for Tenaga. Earnings impact is 2% to 2026’s forecast. However, the decision above implies that the Automatic Fuel Adjustment (AFA) mechanism may be subject to government intervention in the near future and we expect investors to gradually discount the sanctity of the Incentive Based Regulation (IBR) and cost pass-through framework.
- Downgrade Tenaga to HOLD, overhang to persist into the near future. As we cannot say with certainty that this is a one-off (there is now an overhang that Tenaga may be asked to absorb the subsidy if Jan-Mar 27 electricity usage remains high), we downgrade Tenaga from BUY to HOLD with a lower DCF-based target price of RM14.60. In arriving at our fair value, we have prudently raised our discount rate from 7.8% to 8.2% (incorporating a 100bp increase in risk premium for the stock).
HOLD (Downgraded)
Current price:
Target price:
Upside:
Previous TP :
RM13.04
RM14.60
+12.3%
RM16.30
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
