

Company Coverage
Northern Solar (NORTHERN MK): All Cylinders Fired Up
BUY (Maintained)
Current price:
Target price:
Upside:
RM0.69
RM1.00
+44.9%
Analyst
Analyst
Highlights
- We believe the group may be close to capturing a sizeable RM800m CRESS project. This will lift NS’ orderbook to RM1b – a substantial enhancement to both earnings and orderbook visibility into the near future.
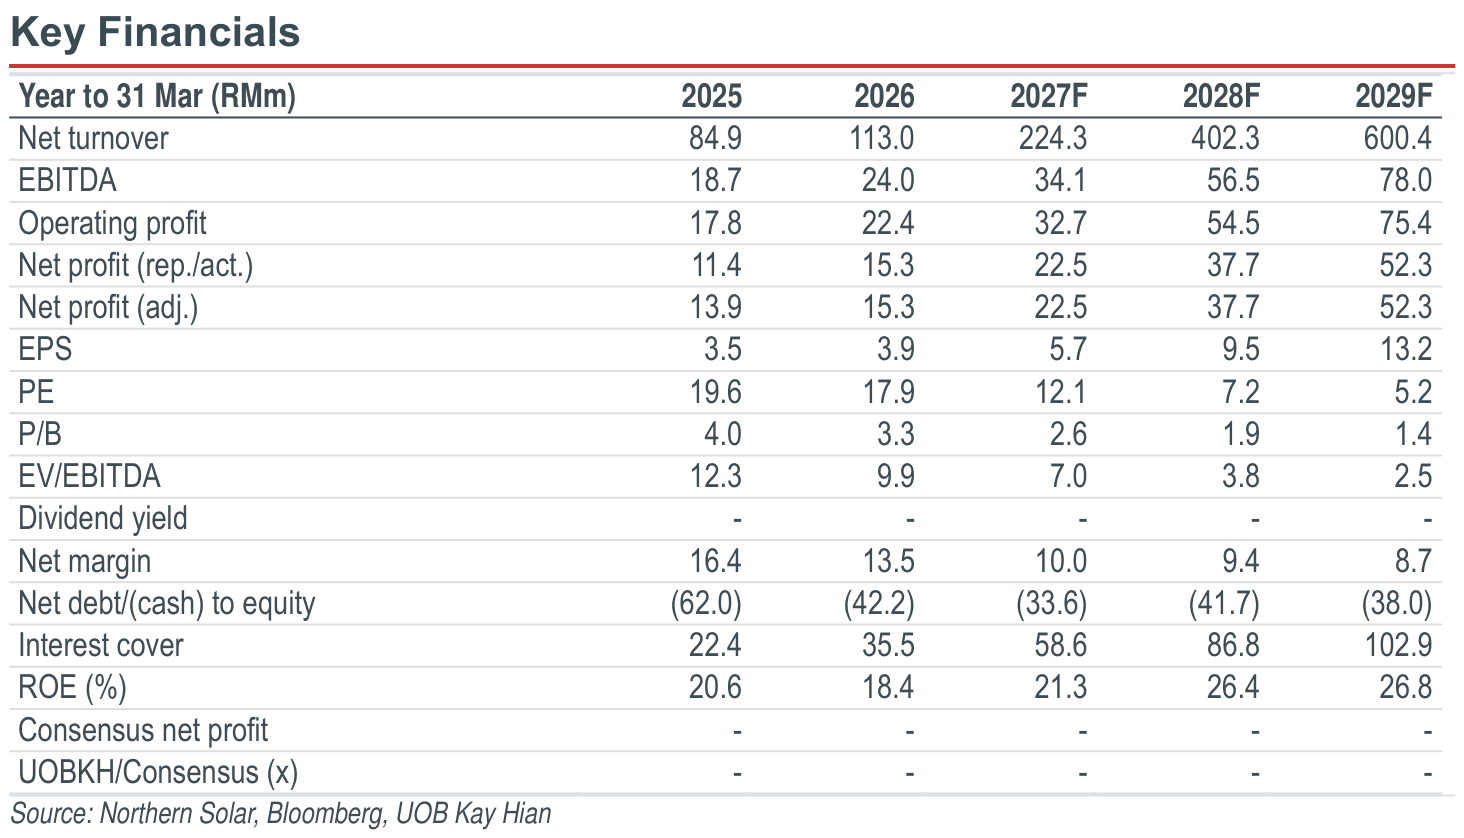
- We like the group for its undemanding valuation (single digit PER) and three-year earnings CAGR of 51% (FY26-29). The group is currently working on a main board listing transfer and Shariah status reinstatement by end-26.
- Maintain BUY with a target price of RM1.00, based on 11x FY28F EPS.
Analysis
- All cylinders fired up... We believe Northern Solar (NS) is well positioned to capture substantial orderbook within the solar sector as the group actively pursues Corporate Renewable Energy Supply Scheme (CRESS) projects worth RM800m – 3x its current market capitalisation of RM273m. Trading at undemanding 12x and 7x FY27 and FY28 EPS, we believe NS is a compelling stock to accumulate. NS is on track to be transferred to the main board by end-26.
- .…as the sector is set to re-rate. The Ministry of Energy Transition and Water Transformation (PETRA) has introduced a new CRESS Acceleration Package and reduced the system access charge (SAC) by 30% to 14 sen/kwh for firm output with battery storage. With this, CRESS project IRRs improved to 10-12% – a bankable outcome. This is a key re-rating catalyst for solar EPCC players – as we expect new CRESS wins in the next three months, so as to fulfil the stipulated commercial operation date by 31 Dec 28.
- Robust three-year earnings CAGR of 51% (FY26-29). Despite a slow start in 1QFY27 (seasonally weaker quarter for solar players), we expect NS to meet our full-year FY27 net profit growth of 50% yoy. FY27 revenue is expected to double on the back of: a) a RM120m large scale solar 5 (LSS5) project win in Mar 26, b) improving commercial and industrial (C&I) demand as businesses seek to mitigate rising electricity costs, and c) a recovery in residential rooftop solar installations supported by a RM3,000 SuRIA Home rebate. NS derived 85% of its revenue from the C&I segment. With the inclusion of the LSS5 contract win, we expect FY27 net profit margin to ease to 10% (FY26: 13.5%). The projected LSS5 project revenue recognised in FY27 is estimated to account for one-third of the group’s revenue at RM75m (63% of total LSS5 EPCC contract value).
Highlights
- We believe the group may be close to capturing a sizeable RM800m CRESS project. This will lift NS’ orderbook to RM1b – a substantial enhancement to both earnings and orderbook visibility into the near future.
- We like the group for its undemanding valuation (single digit PER) and three-year earnings CAGR of 51% (FY26-29). The group is currently working on a main board listing transfer and Shariah status reinstatement by end-26.
- Maintain BUY with a target price of RM1.00, based on 11x FY28F EPS.
Analysis
- All cylinders fired up... We believe Northern Solar (NS) is well positioned to capture substantial orderbook within the solar sector as the group actively pursues Corporate Renewable Energy Supply Scheme (CRESS) projects worth RM800m – 3x its current market capitalisation of RM273m. Trading at undemanding 12x and 7x FY27 and FY28 EPS, we believe NS is a compelling stock to accumulate. NS is on track to be transferred to the main board by end-26.
- .…as the sector is set to re-rate. The Ministry of Energy Transition and Water Transformation (PETRA) has introduced a new CRESS Acceleration Package and reduced the system access charge (SAC) by 30% to 14 sen/kwh for firm output with battery storage. With this, CRESS project IRRs improved to 10-12% – a bankable outcome. This is a key re-rating catalyst for solar EPCC players – as we expect new CRESS wins in the next three months, so as to fulfil the stipulated commercial operation date by 31 Dec 28.
- Robust three-year earnings CAGR of 51% (FY26-29). Despite a slow start in 1QFY27 (seasonally weaker quarter for solar players), we expect NS to meet our full-year FY27 net profit growth of 50% yoy. FY27 revenue is expected to double on the back of: a) a RM120m large scale solar 5 (LSS5) project win in Mar 26, b) improving commercial and industrial (C&I) demand as businesses seek to mitigate rising electricity costs, and c) a recovery in residential rooftop solar installations supported by a RM3,000 SuRIA Home rebate. NS derived 85% of its revenue from the C&I segment. With the inclusion of the LSS5 contract win, we expect FY27 net profit margin to ease to 10% (FY26: 13.5%). The projected LSS5 project revenue recognised in FY27 is estimated to account for one-third of the group’s revenue at RM75m (63% of total LSS5 EPCC contract value).
BUY (Maintained)
Current price:
Target price:
Upside:
RM0.69
RM1.00
+44.9%
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
