

Company Coverage
Eco-Shop Marketing (ECOSHOP MK): Prospects Intact; Macro Perspective Mixed
BUY (Maintained)
Current price:
Target price:
Upside:
RM1.47
RM1.70
16.1%
Analyst
Highlights
- Upcoming 1QFY27 results appear to be improving as SSSG has begun recovering.
- Operationally, Eco-Shop appears sound as impact from cost increases and competition from Pinduoduo appear manageable.
- However, Budget 2027 impact is expected to be mixed. Positive measures such as increased cash handouts will likely be offset by the expected minimum wage hike, though implementation is likely only in 2028.
- Maintain BUY as Eco-Shop offers attractive growth, underpinned by its store expansion rollout. Target price remains unchanged at RM1.70.
Analysis
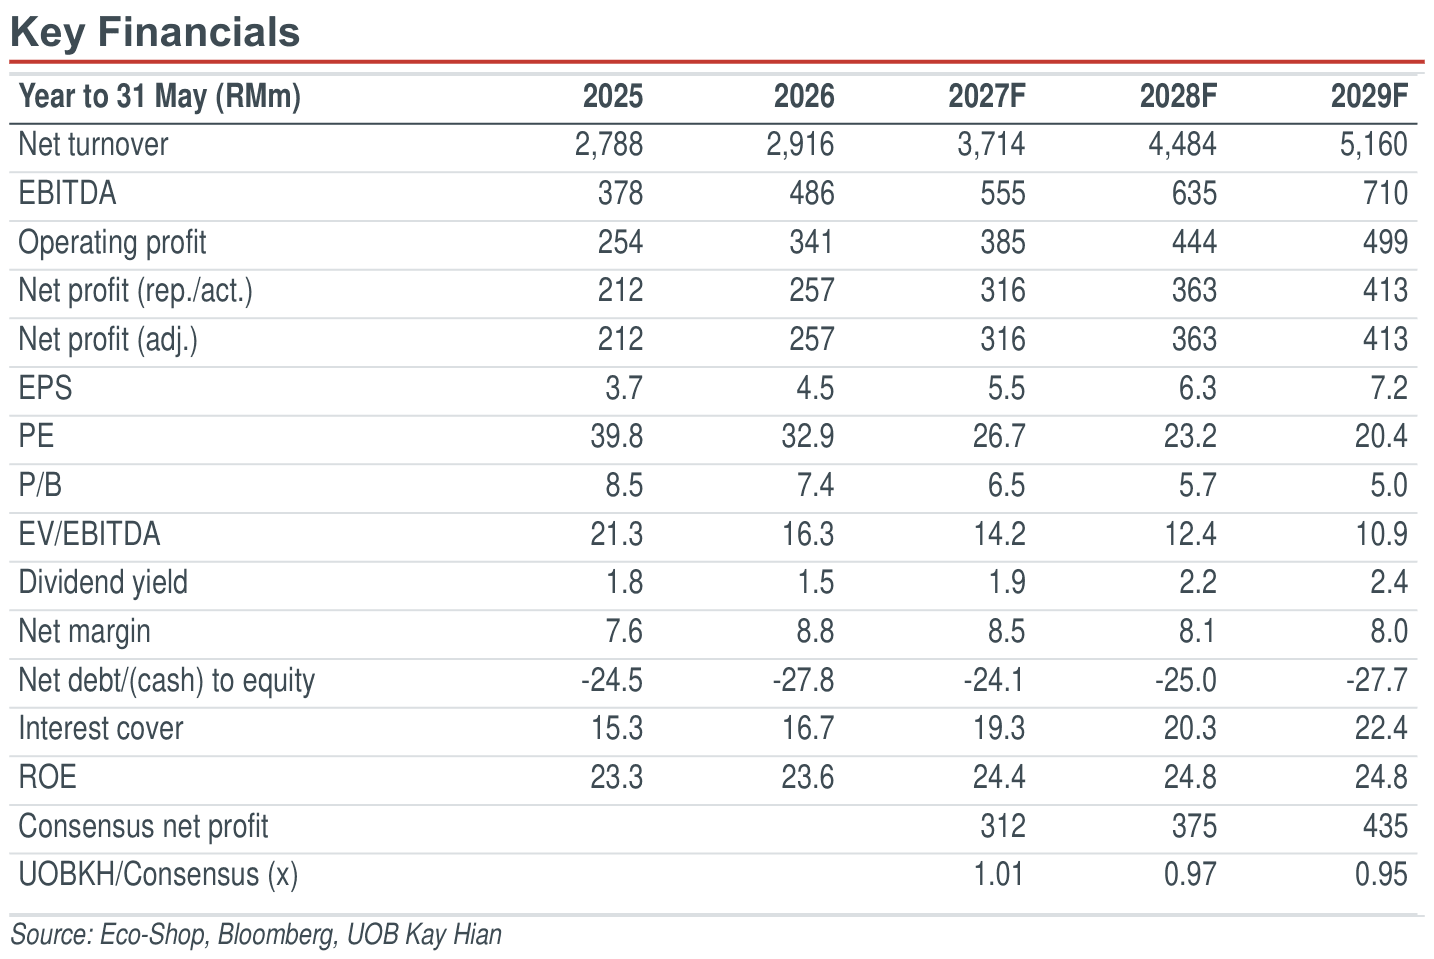
- Store rollout intact, SSSG on the mend. Eco-Shop Marketing’s (Eco-Shop) SSSG may have hit an inflection point with its upcoming quarter no longer seeing major contractions in growth. We expect 1QFY27 results to be robust, underpinned by the improving SSSG as well as its pipeline of new store openings. Following an additional 17 new store openings, total store count has now surpassed 400 with its FY27 target of 100 new store openings remaining intact. Overall, while we view the improving SSSG as a positive sign, we estimate that earnings growth will still largely be driven by new store openings, forecasting mild SSSG improvements of 1-2% over FY27-28.
- Budget 2027 in focus… The upcoming Budget 2027 announcement remains the next key catalyst for Eco-Shop as impact from the anticipated measures could be mixed. Positively, increased cash handouts via the MySara/MyKasih programmes should benefit consumer sentiment as spending is stimulated via subsidies. Going forward, Eco-Shop is prioritising MyKasih implementation in its new stores and have recently secured an additional 97 terminals, bringing the total to 256 or roughly 55% of existing stores. However, we remain conservative on this front given historically, Eco-Shop was actually negatively impacted by MyKasih handouts as spending was channelled to competitors. Otherwise, indirect measures such as increased tax reliefs and a civil servant wage increase could help stimulate consumer sentiment by boosting discretionary income.
Highlights
- Upcoming 1QFY27 results appear to be improving as SSSG has begun recovering.
- Operationally, Eco-Shop appears sound as impact from cost increases and competition from Pinduoduo appear manageable.
- However, Budget 2027 impact is expected to be mixed. Positive measures such as increased cash handouts will likely be offset by the expected minimum wage hike, though implementation is likely only in 2028.
- Maintain BUY as Eco-Shop offers attractive growth, underpinned by its store expansion rollout. Target price remains unchanged at RM1.70.
Analysis
- Store rollout intact, SSSG on the mend. Eco-Shop Marketing’s (Eco-Shop) SSSG may have hit an inflection point with its upcoming quarter no longer seeing major contractions in growth. We expect 1QFY27 results to be robust, underpinned by the improving SSSG as well as its pipeline of new store openings. Following an additional 17 new store openings, total store count has now surpassed 400 with its FY27 target of 100 new store openings remaining intact. Overall, while we view the improving SSSG as a positive sign, we estimate that earnings growth will still largely be driven by new store openings, forecasting mild SSSG improvements of 1-2% over FY27-28.
- Budget 2027 in focus… The upcoming Budget 2027 announcement remains the next key catalyst for Eco-Shop as impact from the anticipated measures could be mixed. Positively, increased cash handouts via the MySara/MyKasih programmes should benefit consumer sentiment as spending is stimulated via subsidies. Going forward, Eco-Shop is prioritising MyKasih implementation in its new stores and have recently secured an additional 97 terminals, bringing the total to 256 or roughly 55% of existing stores. However, we remain conservative on this front given historically, Eco-Shop was actually negatively impacted by MyKasih handouts as spending was channelled to competitors. Otherwise, indirect measures such as increased tax reliefs and a civil servant wage increase could help stimulate consumer sentiment by boosting discretionary income.
BUY (Maintained)
Current price:
Target price:
Upside:
RM1.47
RM1.70
16.1%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.

