

Company Coverage
Binastra Corporation Group (BNASTRA MK): 2QFY27: Yielding Impressively
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
RM2.49
RM3.05
+22.5%
RM2.68
Analyst
Analyst
Highlights
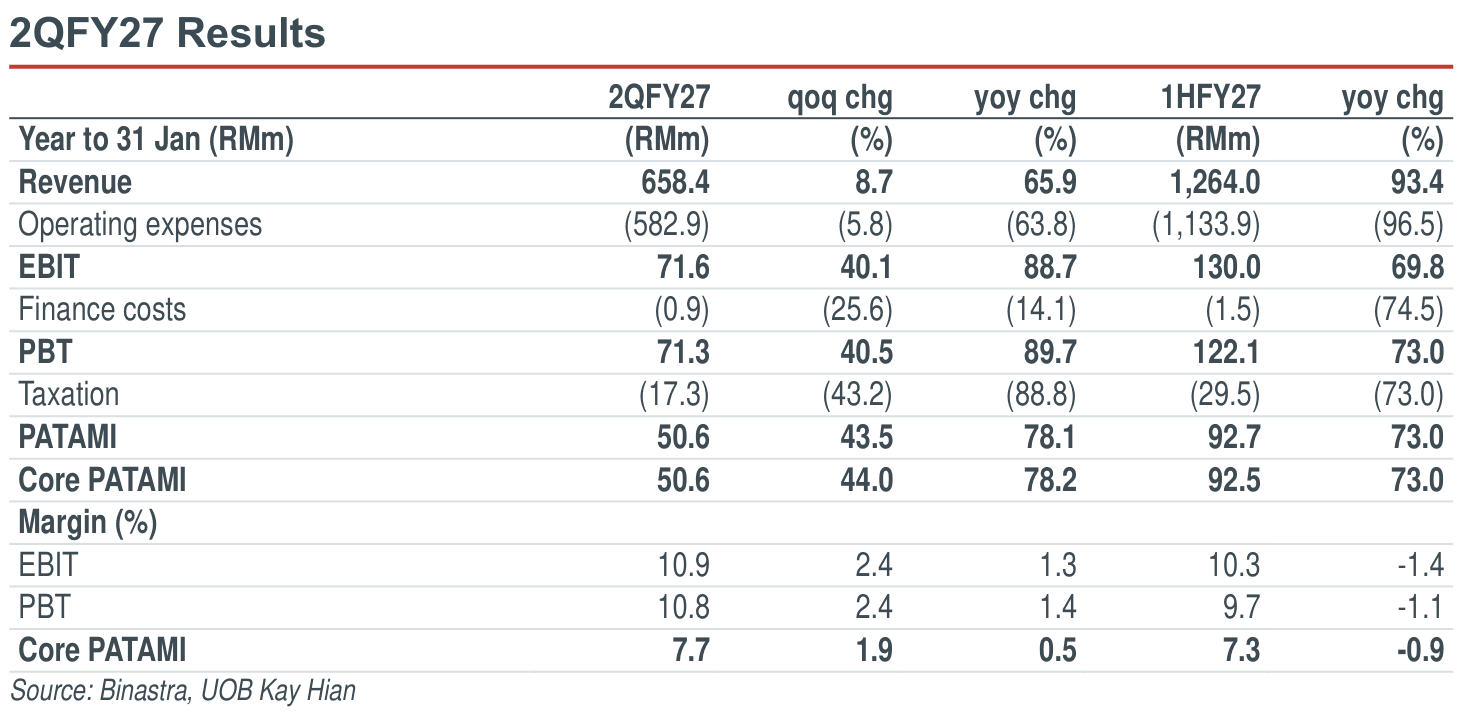
- Above expectations (53% of our and consensus expectations), as we anticipate a stronger earnings momentum for 2HFY27. 2QFY27 revenue grew 66% yoy and core profit rose 78% yoy.
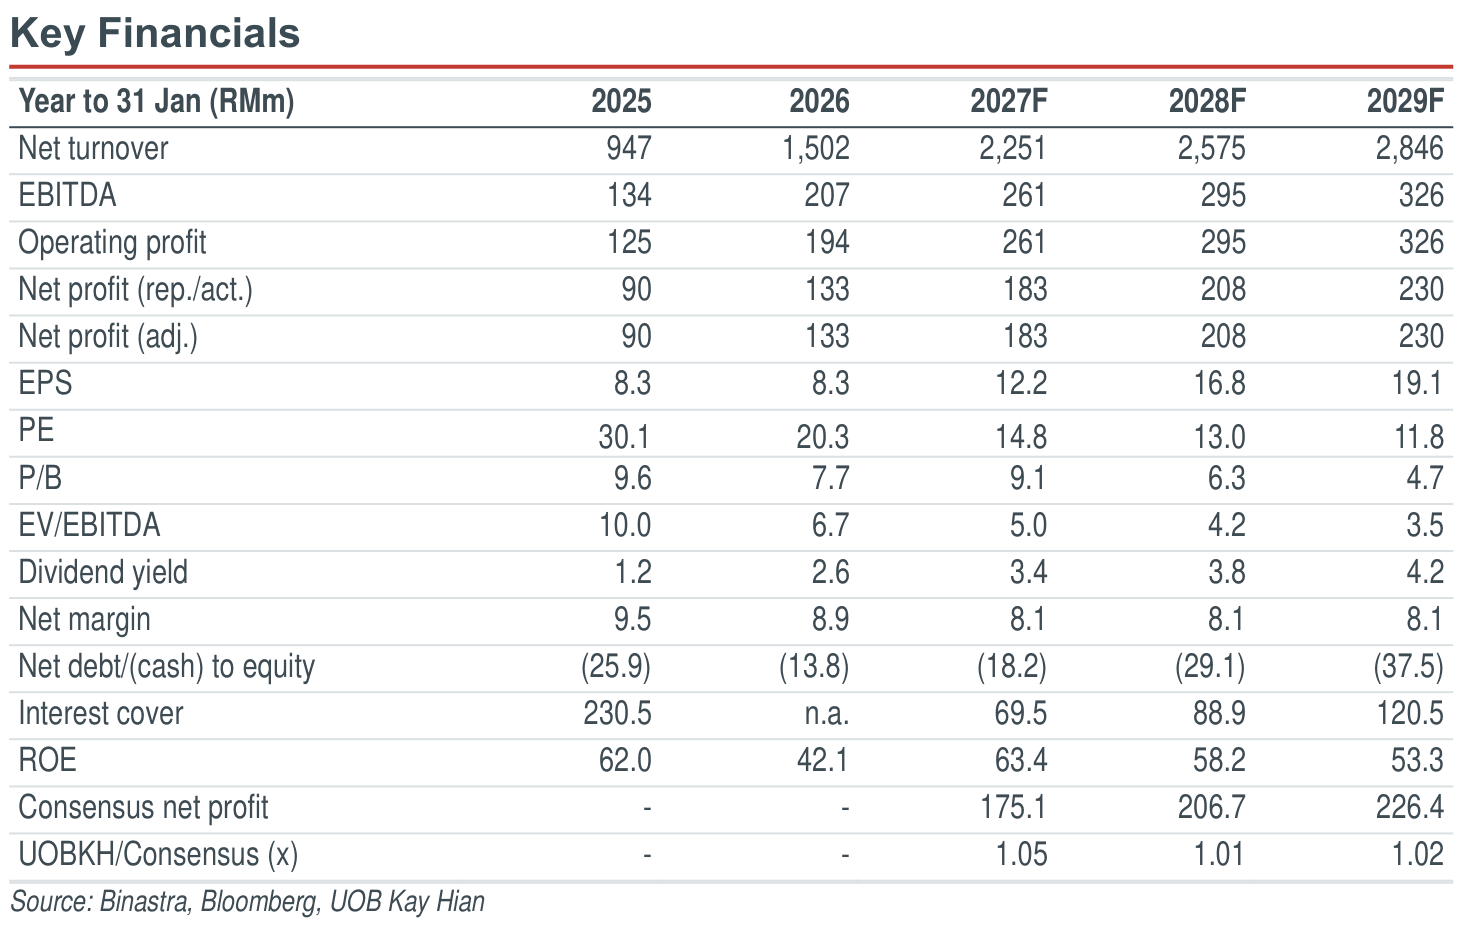
- Maintain BUY with a higher target price of RM3.05 (from RM2.68), rolled over to FY28 valuations. Binastra offers a resilient dividend yield of 3.4-4.2% in FY27-29 (based on 50% payout ratio assumptions).
Analysis
- Results above expectations. Binastra Corporation Group (Binastra) reported an impressive 2QFY27 core net profit of RM50.6m (+44% qoq, +78% yoy) on record-high revenue of RM658.4m (+9% qoq, +666% yoy). 2QFY27 earnings improved 44% qoq in tandem with top-line growth, mainly reflecting better margins from selective solar installation and data centre fit-out projects, besides higher LF Lansen contributions. 1HFY27 results are deemed above expectations, making up 53% of our and consensus full-year estimates. We expect an improving earnings momentum through 2HFY27, anchored on better progress billings from the secured orderbook.
Highlights
- Above expectations (53% of our and consensus expectations), as we anticipate a stronger earnings momentum for 2HFY27. 2QFY27 revenue grew 66% yoy and core profit rose 78% yoy.
- Maintain BUY with a higher target price of RM3.05 (from RM2.68), rolled over to FY28 valuations. Binastra offers a resilient dividend yield of 3.4-4.2% in FY27-29 (based on 50% payout ratio assumptions).
Analysis
- Results above expectations. Binastra Corporation Group (Binastra) reported an impressive 2QFY27 core net profit of RM50.6m (+44% qoq, +78% yoy) on record-high revenue of RM658.4m (+9% qoq, +666% yoy). 2QFY27 earnings improved 44% qoq in tandem with top-line growth, mainly reflecting better margins from selective solar installation and data centre fit-out projects, besides higher LF Lansen contributions. 1HFY27 results are deemed above expectations, making up 53% of our and consensus full-year estimates. We expect an improving earnings momentum through 2HFY27, anchored on better progress billings from the secured orderbook.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
RM2.49
RM3.05
+22.5%
RM2.68
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
