Company Coverage
Surya Pertiwi (SPTO IJ): Market Leader With High Dividend Yield
NOT RATED
Current price:
Target price:
Upside:
Rp595
n.a.
n.a.
Analyst
Analyst
Highlights
- Exclusive TOTO distribution and cost advantage. SPTO has nearly five decades of TOTO exclusivity, local manufacturing advantages, and a nine-brand portfolio spanning all value segments.
- High dividend yield with upside potential. SPTO has an 11.8% yield at Rp595/share, with potential for a higher payout ratio and quarterly distributions.
- Seasonal 4Q strength, but margin pressure. 1H26 revenue grew 3.6% yoy to Rp1,375b, while gross margin fell to 27.6% amid higher discounting.
Analysis
- Japan-made quality at a structural price advantage over Chinese imports. Surya Pertiwi (SPTO) is the exclusive distributor of Surya Toto Indonesia (TOTO) products in Indonesia. Its shareholders co-founded TOTO with TOTO Japan in 1977 to manufacture ceramic sanitaryware, including closets, washbasins, and urinals, at TOTO’s large-scale facility in Tangerang using predominantly local raw materials. SPTO and TOTO operate as sister companies under the same shareholder group, with TOTO focused on manufacturing and SPTO on distribution. Local production gives SPTO a structural cost advantage over Chinese competitors by avoiding import duties and freight costs. Beyond ceramics, SPTO distributes nine brands across all value segments, from mass-market residential to European luxury, enabling it to supply entire projects under one roof.
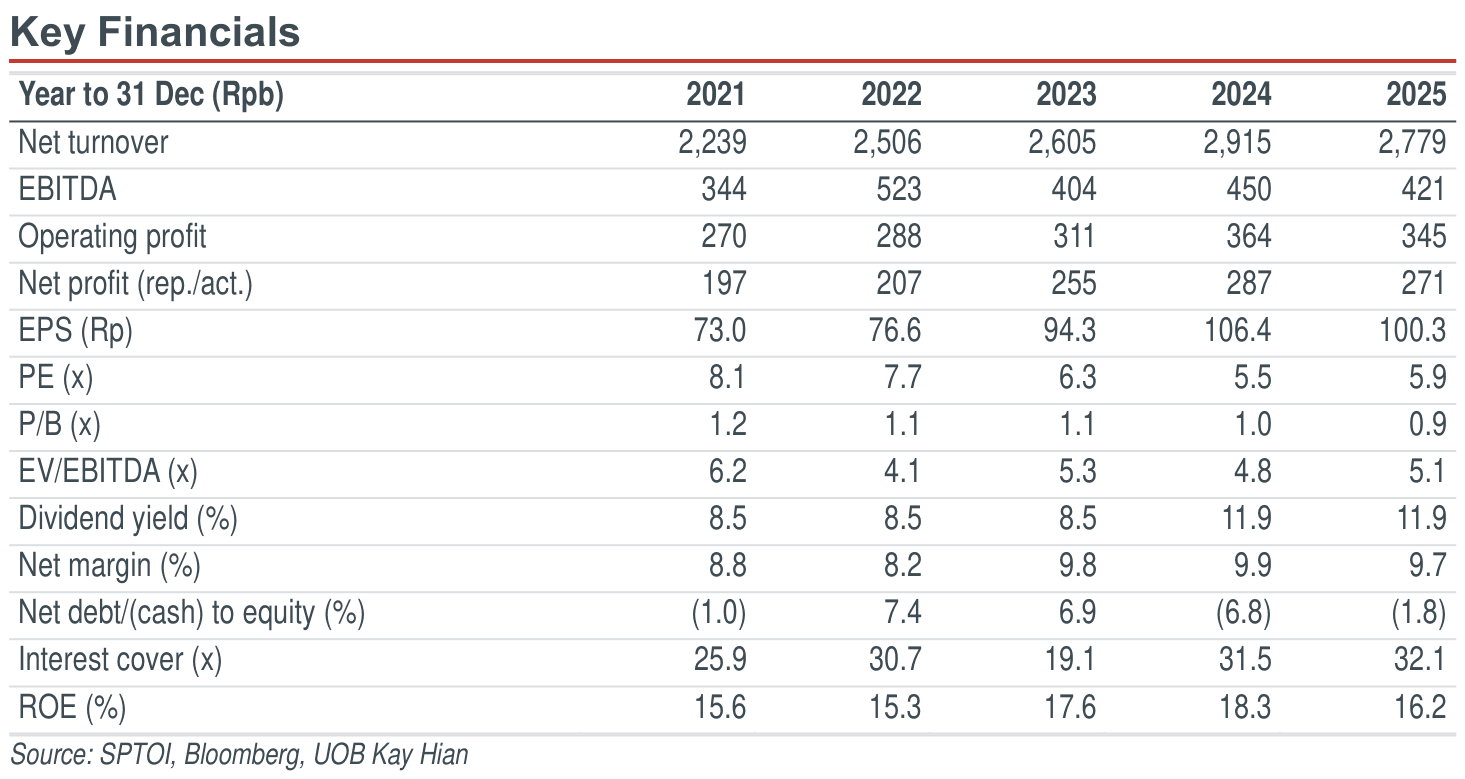
- High and potentially more frequent dividend distributions. At Rp595/share, SPTO offers a dividend yield of around 11.8%, split roughly equally between interim and final dividends at 5.9% each, based on a 70% payout ratio on 2025 net income. Its balance sheet remains solid, with a total liabilities-to-equity ratio of 0.37x in 1H26, unchanged from 2025 and below 0.44x in 2024, while its current ratio stood at a healthy 1.99x. With no major expansion capex planned in the near term, SPTO can allocate more cash to shareholders. Management is considering raising the payout ratio above 70% and moving from semi-annual to quarterly dividends, potentially providing a more regular income stream.
Highlights
- Exclusive TOTO distribution and cost advantage. SPTO has nearly five decades of TOTO exclusivity, local manufacturing advantages, and a nine-brand portfolio spanning all value segments.
- High dividend yield with upside potential. SPTO has an 11.8% yield at Rp595/share, with potential for a higher payout ratio and quarterly distributions.
- Seasonal 4Q strength, but margin pressure. 1H26 revenue grew 3.6% yoy to Rp1,375b, while gross margin fell to 27.6% amid higher discounting.
Analysis
- Japan-made quality at a structural price advantage over Chinese imports. Surya Pertiwi (SPTO) is the exclusive distributor of Surya Toto Indonesia (TOTO) products in Indonesia. Its shareholders co-founded TOTO with TOTO Japan in 1977 to manufacture ceramic sanitaryware, including closets, washbasins, and urinals, at TOTO’s large-scale facility in Tangerang using predominantly local raw materials. SPTO and TOTO operate as sister companies under the same shareholder group, with TOTO focused on manufacturing and SPTO on distribution. Local production gives SPTO a structural cost advantage over Chinese competitors by avoiding import duties and freight costs. Beyond ceramics, SPTO distributes nine brands across all value segments, from mass-market residential to European luxury, enabling it to supply entire projects under one roof.
- High and potentially more frequent dividend distributions. At Rp595/share, SPTO offers a dividend yield of around 11.8%, split roughly equally between interim and final dividends at 5.9% each, based on a 70% payout ratio on 2025 net income. Its balance sheet remains solid, with a total liabilities-to-equity ratio of 0.37x in 1H26, unchanged from 2025 and below 0.44x in 2024, while its current ratio stood at a healthy 1.99x. With no major expansion capex planned in the near term, SPTO can allocate more cash to shareholders. Management is considering raising the payout ratio above 70% and moving from semi-annual to quarterly dividends, potentially providing a more regular income stream.
NOT RATED
Current price:
Target price:
Upside:
Rp595
n.a.
n.a.
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.

