

Company Coverage
GoTo Gojek Tokopedia (GOTO IJ) : New Price Floor Today; Fintech Offsets The Take-Rate Hit
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Rp50
Rp60
+20.0%
Rp78
Analyst
Analyst
Highlights
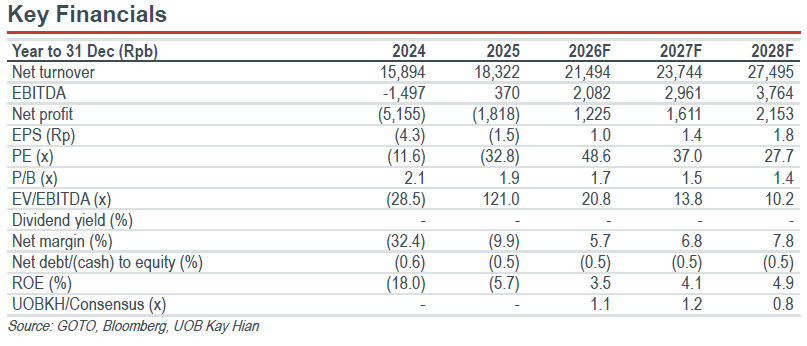
Today marks the IDX’s implementation of a lower price floor, from Rp50/share to Rp1/share. Note that the last average negotiated price was Rp28/share, near the day-4 level if the stock trades limit-down.
On the bright side, GOTO has announced a treasury share cancellation (32b shares; 2.7% of total shares) amid its Rp3.5t buyback plan. The company had ample cash of Rp23.4t as of end-2Q26, implying about Rp20/share.
We maintain BUY but lower our target price to Rp60 (from Rp78).
Analysis
Maintains EBITDA guidance. During our 2026 Asian Gems Conference, GoTo Gojek Tokopedia (GOTO) stated that it is maintaining its FY26 adjusted EBITDA guidance of Rp3.2t-3.4t, cutting on-demand service (ODS) guidance on a lower 2W take rate (8% vs 20% previously) while raising its guidance for the financial segment on surging transaction volume and a stronger ecosystem loan book.
3Q26 momentum intact. GOTO has posted two consecutive quarters of positive net profit. Some pressure in 3Q26 is possible given the modest impact of the lower 2W e-hailing take rate (~7% of revenue), though we still expect GOTO to remain in positive net profit territory.
ODS: Solid 2Q, but regulatory overhang lingers. GOTO has applied the new 8% 2W take rate since Jul 26, and downside regulatory risk remains amid reports that regulators may extend rules beyond 2W e-hailing to food delivery (not yet factored into our model). On the bright side, food and goods delivery have a more diversified monetisation model (spanning merchant commissions, delivery fees and in-app advertising), making them structurally less vulnerable than passenger transport to single-stream commission caps. Operationally, ODS remains positive: 2Q26 adjusted EBITDA reached Rp464b (+6% qoq, +41% yoy), with net revenue of Rp3,495b (+6% qoq, +19% yoy).
Fintech: GoPay building an ecosystem moat. Fintech has become the key earnings growth driver. 2Q26 net revenue reached Rp1,904b (+8% qoq, +57% yoy), adjusted EBITDA was Rp481b (+32% qoq, +447% yoy) and core GTV was Rp157.3t (+20% qoq, +91% yoy). Monthly transacting users grew to 28.8m (+29% yoy) on stronger ecosystem synergies and lower GoPay user acquisition costs, while the loan book expanded to Rp11.0t (+58% yoy). Launched in mid-23, the GoPay app anchors the funding and lending ecosystem and broke even in 2Q despite free transfers. Some 60% of the loan book originates from the core Gojek/GoPay ecosystem and 40% from third-party channels. Despite strong loan growth, NPLs (>90 days overdue) remain manageable at <1%, although credit underwriting will turn more selective given the current economic conditions.
Highlights
Today marks the IDX’s implementation of a lower price floor, from Rp50/share to Rp1/share. Note that the last average negotiated price was Rp28/share, near the day-4 level if the stock trades limit-down.
On the bright side, GOTO has announced a treasury share cancellation (32b shares; 2.7% of total shares) amid its Rp3.5t buyback plan. The company had ample cash of Rp23.4t as of end-2Q26, implying about Rp20/share.
We maintain BUY but lower our target price to Rp60 (from Rp78).
Analysis
Maintains EBITDA guidance. During our 2026 Asian Gems Conference, GoTo Gojek Tokopedia (GOTO) stated that it is maintaining its FY26 adjusted EBITDA guidance of Rp3.2t-3.4t, cutting on-demand service (ODS) guidance on a lower 2W take rate (8% vs 20% previously) while raising its guidance for the financial segment on surging transaction volume and a stronger ecosystem loan book.
3Q26 momentum intact. GOTO has posted two consecutive quarters of positive net profit. Some pressure in 3Q26 is possible given the modest impact of the lower 2W e-hailing take rate (~7% of revenue), though we still expect GOTO to remain in positive net profit territory.
ODS: Solid 2Q, but regulatory overhang lingers. GOTO has applied the new 8% 2W take rate since Jul 26, and downside regulatory risk remains amid reports that regulators may extend rules beyond 2W e-hailing to food delivery (not yet factored into our model). On the bright side, food and goods delivery have a more diversified monetisation model (spanning merchant commissions, delivery fees and in-app advertising), making them structurally less vulnerable than passenger transport to single-stream commission caps. Operationally, ODS remains positive: 2Q26 adjusted EBITDA reached Rp464b (+6% qoq, +41% yoy), with net revenue of Rp3,495b (+6% qoq, +19% yoy).
Fintech: GoPay building an ecosystem moat. Fintech has become the key earnings growth driver. 2Q26 net revenue reached Rp1,904b (+8% qoq, +57% yoy), adjusted EBITDA was Rp481b (+32% qoq, +447% yoy) and core GTV was Rp157.3t (+20% qoq, +91% yoy). Monthly transacting users grew to 28.8m (+29% yoy) on stronger ecosystem synergies and lower GoPay user acquisition costs, while the loan book expanded to Rp11.0t (+58% yoy). Launched in mid-23, the GoPay app anchors the funding and lending ecosystem and broke even in 2Q despite free transfers. Some 60% of the loan book originates from the core Gojek/GoPay ecosystem and 40% from third-party channels. Despite strong loan growth, NPLs (>90 days overdue) remain manageable at <1%, although credit underwriting will turn more selective given the current economic conditions.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Rp50
Rp60
+20.0%
Rp78
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.

