

Company Coverage
Bukit Asam (PTBA IJ): Scaling Operations For Upcoming Growth Cycle
NOT RATED
Current price:
Target price:
Upside:
Rp3,180
n.a.
n.a.
Analyst
Analyst
Highlights
- Production is set to accelerate in 2H26. Following 1H26 production of 19.45mt, PTBA's output could reach 28.55mt in 2H26 (+46.8% hoh), implying 2026 production of around 48mt. The stronger volume outlook, coupled with firmer coal prices, a higher export mix, and manageable cost pressures, should support earnings momentum into year-end.
- Catalysts from Kramasan completion (up to 20mtpa production addition), Sumsel 8 ramp-up, and Mempawah’s power plant expansion.
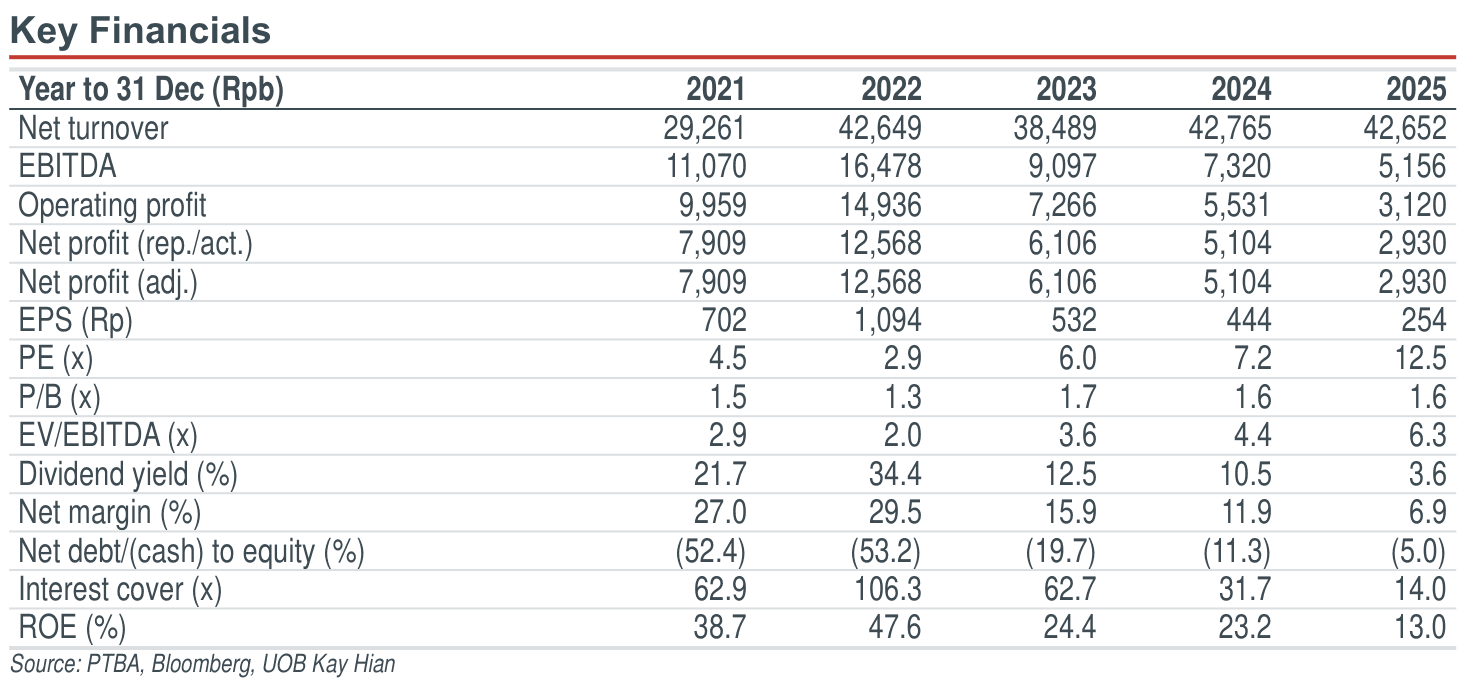
- PTBA is trading at 7.8x 2026F PE with a potential yield of up to 10%, in line with peers, while past dividend payouts of 45-75% imply a dividend yield of 6-10%.
Analysis
- An integrated, state-owned coal producer based in Sumatra. Bukit Asam (PTBA) holds 2.88b tonnes of coal reserves and 5.71b tonnes of resources as of Dec 25, implying a mine life of about 60 years based on 2025 production levels. Its main asset is an around 40,347ha concession at Tanjung Enim, South Sumatra, which produced 98% of its 47.2mt total output in 2025 with most sales in the 4,300-5,200 calorific value range. PTBA hauls coal on dedicated rail lines to its own ports at Tarahan (Lampung, 25mtpa capacity) and Kertapati (Palembang, 7mtpa), and supplies its own approximately 1.6GW of coal-fired power capacity. In 2025, 54% of sales went to the domestic market, mainly PLN power plants in Java and Sumatra, while the rest was exported, mainly to Asian customers.
- Kramasan completion remains the key near-term catalyst. The Tanjung Enim–Kramasan railway is a 158km coal haulage line linking PTBA's mining operations to a coal terminal near Palembang, developed in partnership with KAI. The line has an initial capacity of 20mtpa, with management targeting full operations in 2H27 and coal deliveries of around 8mt in 2027. Beyond easing current logistics bottlenecks, Kramasan could increase PTBA's production capacity by up to 60mt over the longer term (including all transporation from train and mine mouth sales). We believe the additional capacity would provide greater flexibility to increase export sales exposure, which could serve as a meaningful earnings catalyst given export coal prices have historically traded at a 28-68% premium to domestic prices over the past three years. Another potential catalyst is the optimisation of the Kertapati rail corridor, which could add a further 7mtpa of transport capacity.
- Upside from Sumsel 8 ramp-up. The 2x660MW Sumsel 8 coal-fired power plant, in which PTBA holds a 45% stake, is currently operating at about 60% utilisation. As utilisation improves toward full capacity, PTBA could benefit from additional mine-mouth coal sales of up to 2mtpa. We view these sales as particularly attractive as they are not constrained by transportation bottlenecks and generate relatively healthy margins.
Highlights
- Production is set to accelerate in 2H26. Following 1H26 production of 19.45mt, PTBA's output could reach 28.55mt in 2H26 (+46.8% hoh), implying 2026 production of around 48mt. The stronger volume outlook, coupled with firmer coal prices, a higher export mix, and manageable cost pressures, should support earnings momentum into year-end.
- Catalysts from Kramasan completion (up to 20mtpa production addition), Sumsel 8 ramp-up, and Mempawah’s power plant expansion.
- PTBA is trading at 7.8x 2026F PE with a potential yield of up to 10%, in line with peers, while past dividend payouts of 45-75% imply a dividend yield of 6-10%.
Analysis
- An integrated, state-owned coal producer based in Sumatra. Bukit Asam (PTBA) holds 2.88b tonnes of coal reserves and 5.71b tonnes of resources as of Dec 25, implying a mine life of about 60 years based on 2025 production levels. Its main asset is an around 40,347ha concession at Tanjung Enim, South Sumatra, which produced 98% of its 47.2mt total output in 2025 with most sales in the 4,300-5,200 calorific value range. PTBA hauls coal on dedicated rail lines to its own ports at Tarahan (Lampung, 25mtpa capacity) and Kertapati (Palembang, 7mtpa), and supplies its own approximately 1.6GW of coal-fired power capacity. In 2025, 54% of sales went to the domestic market, mainly PLN power plants in Java and Sumatra, while the rest was exported, mainly to Asian customers.
- Kramasan completion remains the key near-term catalyst. The Tanjung Enim–Kramasan railway is a 158km coal haulage line linking PTBA's mining operations to a coal terminal near Palembang, developed in partnership with KAI. The line has an initial capacity of 20mtpa, with management targeting full operations in 2H27 and coal deliveries of around 8mt in 2027. Beyond easing current logistics bottlenecks, Kramasan could increase PTBA's production capacity by up to 60mt over the longer term (including all transporation from train and mine mouth sales). We believe the additional capacity would provide greater flexibility to increase export sales exposure, which could serve as a meaningful earnings catalyst given export coal prices have historically traded at a 28-68% premium to domestic prices over the past three years. Another potential catalyst is the optimisation of the Kertapati rail corridor, which could add a further 7mtpa of transport capacity.
- Upside from Sumsel 8 ramp-up. The 2x660MW Sumsel 8 coal-fired power plant, in which PTBA holds a 45% stake, is currently operating at about 60% utilisation. As utilisation improves toward full capacity, PTBA could benefit from additional mine-mouth coal sales of up to 2mtpa. We view these sales as particularly attractive as they are not constrained by transportation bottlenecks and generate relatively healthy margins.
NOT RATED
Current price:
Target price:
Upside:
Rp3,180
n.a.
n.a.
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.

