

Company Coverage
Amman Mineral Internasional (AMMN IJ): 2Q26: Higher Concentrate And Refined Gold Sales Drive Earnings
BUY (Maintained)
Current price:
Target price:
Upside:
Rp4,710
Rp7,000
+48.6%
Analyst
Analyst
Highlights
- 1H26 results are in line with consensus and our estimates (at 53%/46% respectively). EBITDA surged 1,207% yoy from a low base to US$1,128m and net profit reached US$498m, driven by concentrate exports under the permit that is valid until Apr 26, ramp-up in production of refined gold, and higher Phase 8 grades.
- Operations are tracking ahead of schedule, with gold-in-concentrate guidance raised 34% to 775,000 oz for 2026 and the smelter and PMR fully commissioned. Maintain BUY with a target price of Rp7,000.
Analysis
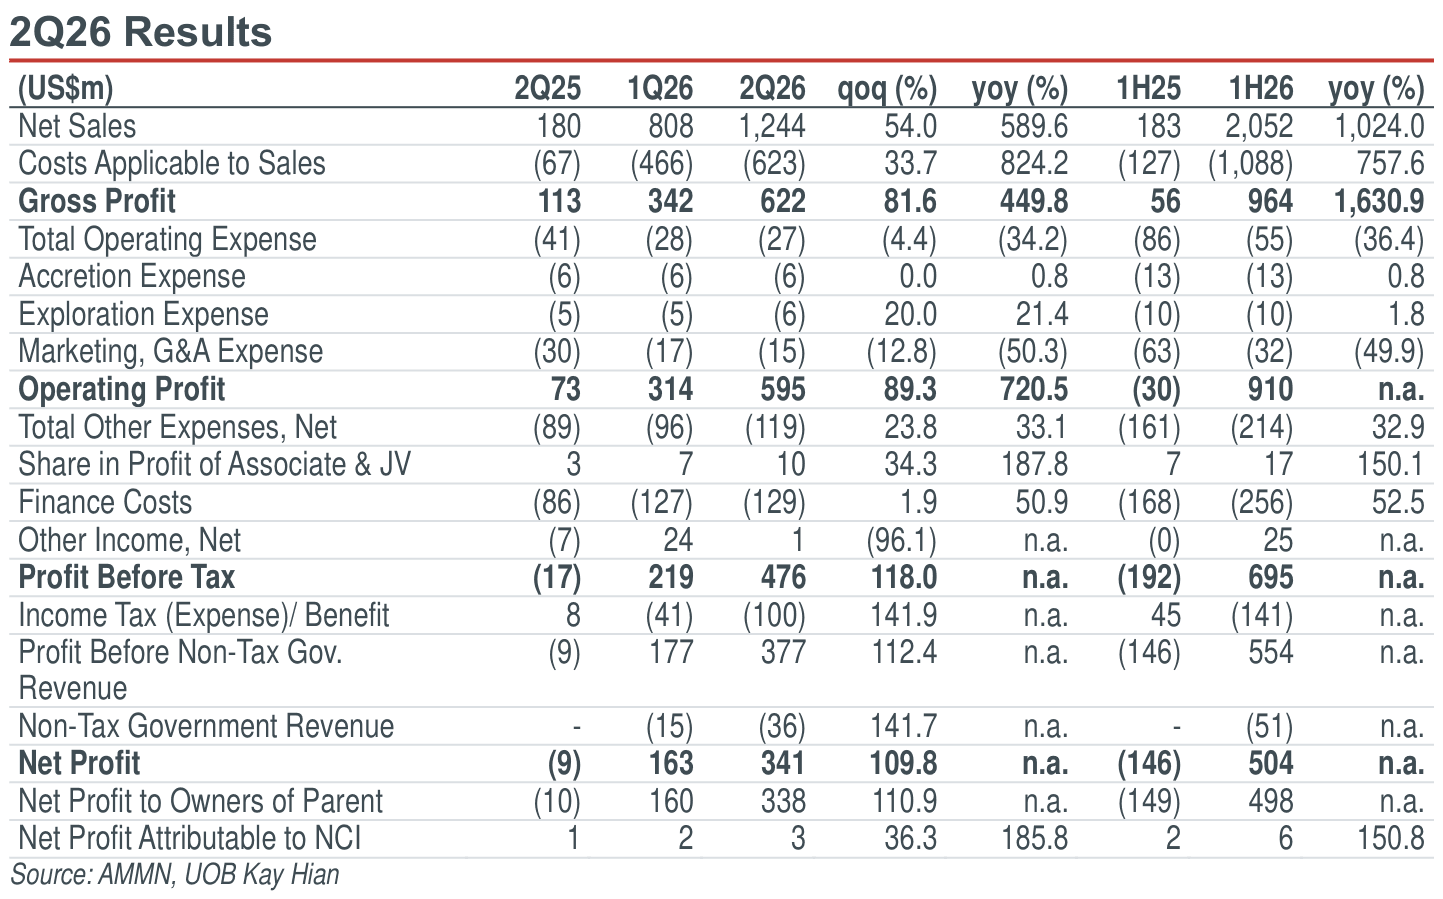
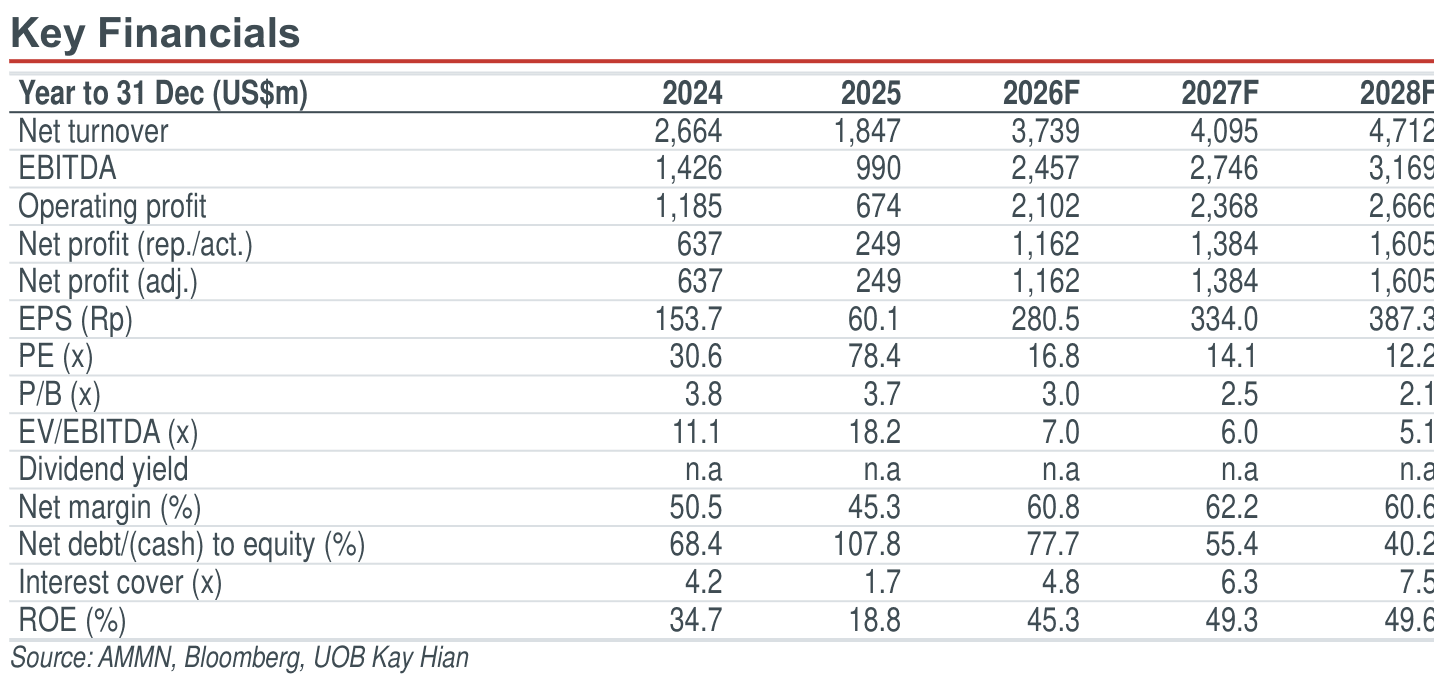
- 2Q26 net profit reached US$337.8m (+110.9% qoq). Amman Mineral Internasional’s (AMMN) 2Q26 net profit attributable reached US$338m (+110.9% qoq; 2Q25: US$10m loss), supported by net sales of US$1,244m (+54.0% qoq, +589.6% yoy). Gross profit rose 81.6% qoq to US$622m, lifting gross margin to 50.0% (1Q26: 42.4%), while opex declined 4.4% qoq to US$27m. As a result, operating profit increased 89.3% qoq to US$595m, with operating margin expanding to 47.8% (1Q26: 38.9%). 1H26 net profit attributable reached US$498m (1H25: US$149m loss), representing 43% of our 2026 estimate and 53% of consensus. EBITDA surged 1,207% yoy to US$1,128m, representing 53% of consensus and 45% of our full-year forecasts, albeit from a low base, as the smelter only restarted operations in 4Q25. Nevertheless, we expect 2H26 earnings to remain solid, supported by the smelter and precious metal refinery (PMR) being fully commissioned, as well as back-loaded cathode and refined gold production guidance.
Highlights
- 1H26 results are in line with consensus and our estimates (at 53%/46% respectively). EBITDA surged 1,207% yoy from a low base to US$1,128m and net profit reached US$498m, driven by concentrate exports under the permit that is valid until Apr 26, ramp-up in production of refined gold, and higher Phase 8 grades.
- Operations are tracking ahead of schedule, with gold-in-concentrate guidance raised 34% to 775,000 oz for 2026 and the smelter and PMR fully commissioned. Maintain BUY with a target price of Rp7,000.
Analysis
- 2Q26 net profit reached US$337.8m (+110.9% qoq). Amman Mineral Internasional’s (AMMN) 2Q26 net profit attributable reached US$338m (+110.9% qoq; 2Q25: US$10m loss), supported by net sales of US$1,244m (+54.0% qoq, +589.6% yoy). Gross profit rose 81.6% qoq to US$622m, lifting gross margin to 50.0% (1Q26: 42.4%), while opex declined 4.4% qoq to US$27m. As a result, operating profit increased 89.3% qoq to US$595m, with operating margin expanding to 47.8% (1Q26: 38.9%). 1H26 net profit attributable reached US$498m (1H25: US$149m loss), representing 43% of our 2026 estimate and 53% of consensus. EBITDA surged 1,207% yoy to US$1,128m, representing 53% of consensus and 45% of our full-year forecasts, albeit from a low base, as the smelter only restarted operations in 4Q25. Nevertheless, we expect 2H26 earnings to remain solid, supported by the smelter and precious metal refinery (PMR) being fully commissioned, as well as back-loaded cathode and refined gold production guidance.
BUY (Maintained)
Current price:
Target price:
Upside:
Rp4,710
Rp7,000
+48.6%
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
