
Company Coverage
Sun Hung Kai & Co. (86 HK): 1H26: Solid Credit Business And Continued Progress In Alternative Solutions
BUY (Maintained)
Current price:
Target price:
Upside:
HK$4.12
HK$6.40
+55.3%
Analyst
Highlights
- 1H26 attributable net profit fell 22.4% yoy to HK$688m (41% of our full-year estimate) due to a high base for its investment management segment in 1H25 with a sizeable one-off IPO gain, but partially offset by the solid performance of the credit business and continued progress in alternative solutions.
- SHK & Co. demonstrates disciplined asset allocation and deal-sourcing strength amid market volatilities. While still at an early stage, its growing strategic partnerships are expected to further unlock cross-segment synergies and flywheel benefits.
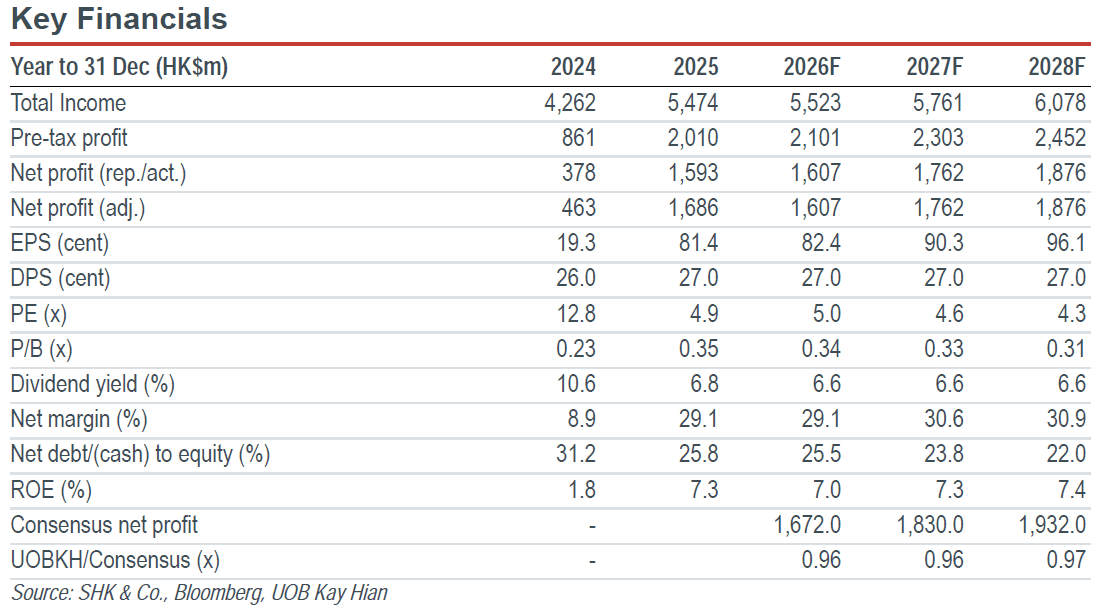
- Maintain BUY and target price of HK$6.40 based on 0.53x 2026F P/B.
Analysis
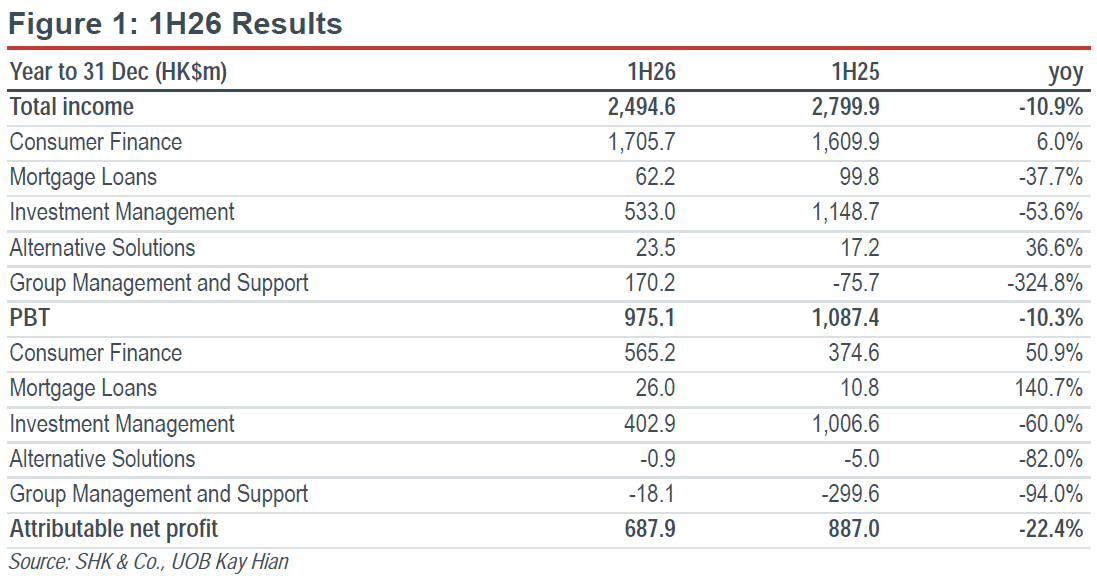
- 1H26 results. Sun Hung Kai & Co.’s (SHK & Co.) 1H26 total income fell 10.9% yoy to HK$2,495m (44% of our full-year estimate), mainly due to lower net investment income. Attributable net profit declined 22.4% yoy to HK$688m (41% of our full-year estimate) due to a high base for the investment management in 1H25, but partly offset by the solid performance of the credit business.
Highlights
- 1H26 attributable net profit fell 22.4% yoy to HK$688m (41% of our full-year estimate) due to a high base for its investment management segment in 1H25 with a sizeable one-off IPO gain, but partially offset by the solid performance of the credit business and continued progress in alternative solutions.
- SHK & Co. demonstrates disciplined asset allocation and deal-sourcing strength amid market volatilities. While still at an early stage, its growing strategic partnerships are expected to further unlock cross-segment synergies and flywheel benefits.
- Maintain BUY and target price of HK$6.40 based on 0.53x 2026F P/B.
Analysis
- 1H26 results. Sun Hung Kai & Co.’s (SHK & Co.) 1H26 total income fell 10.9% yoy to HK$2,495m (44% of our full-year estimate), mainly due to lower net investment income. Attributable net profit declined 22.4% yoy to HK$688m (41% of our full-year estimate) due to a high base for the investment management in 1H25, but partly offset by the solid performance of the credit business.
BUY (Maintained)
Current price:
Target price:
Upside:
HK$4.12
HK$6.40
+55.3%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

17 Sept 2026
Trip.com (9961 HK) - 2Q26: In-line Results; 3Q26 Growth To Slow On Regulatory Pressure; Expect A Recovery In 2027

7 Oct 2026
Tai Hing Group (6811 HK): A Multi-brand Casual Dining Restaurant Group In Hong Kong

8 Oct 2026
Geely Auto (175 HK): Exports And New Technologies Offset Weak Domestic Sales
Our latest research
15 Oct 2026
TA: Lenovo Group (0992 HK) / SHEIN Global (0625 HK)
14 Oct 2026
TA: Sinotruk Hong Kong (3808 HK) / Hong Kong Exchanges and Clearing (0388 HK)

14 Oct 2026