

Company Coverage
New World Development (17 HK): FY26: Core Profit Turns Positive; 11 SKIES Exit Helps Long-term Cash Flow, But Debt Metrics Warrant Caution
HOLD (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$6.05
HK$6.44
6.4%
HK$9.60
Analyst
Analyst
Highlights
- Underlying net profit back in profit, beating expectations, supported by lower finance costs as well as growth in core operations’ results. Higher provisions and impairment led to expanded attributable losses.
- Early termination of the 11 SKIES contract, as announced on 30 Sep 26, is positive on NWD’s long-term cash flow, but weaker debt metrics need caution.
- Maintain HOLD with a lower target price of HK$6.44 to reflect a wider NAV discount of 80% (previously 70%), taking into account the company’s debt metrics and the market’s interest-rate outlook.
Analysis
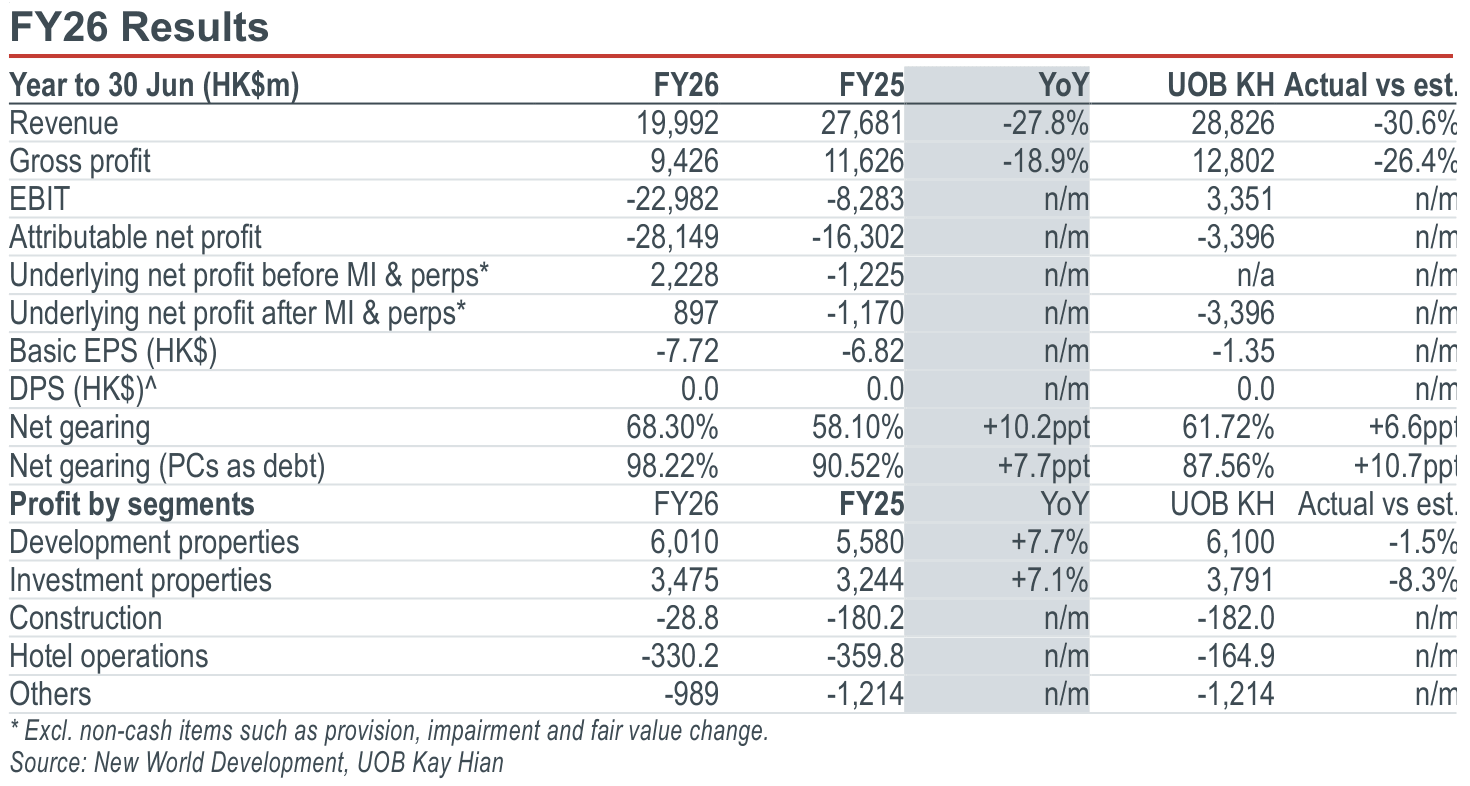
- Underlying net profit beat expectations; high provisions deepened net loss. In FY26, New World Development (NWD) reported HK$2.2b of underlying net profit from recurring and core operations (before minority interest and perps distribution), representing a turnaround from a loss of HK1.2b in FY25, beating market expectation of a loss of HK$2,125m. This is mainly thanks to: a) increase in profits from development and investment properties, and b) a 14.9% yoy decrease in finance costs. However, attributable net loss expanded 72.7% yoy to HK$28.2b in FY26, due to: a) HK$18.3b net impairment losses and provisions relating to the 11 SKIES project, and b) HK$8.0b impairment loss on property inventories. Net gearing ratio edged up 10.2ppt to 68.3% as cash declined 34.4% yoy to HK$17b as of Jun 26. The company continued to halt dividends and perps distribution.
Highlights
- Underlying net profit back in profit, beating expectations, supported by lower finance costs as well as growth in core operations’ results. Higher provisions and impairment led to expanded attributable losses.
- Early termination of the 11 SKIES contract, as announced on 30 Sep 26, is positive on NWD’s long-term cash flow, but weaker debt metrics need caution.
- Maintain HOLD with a lower target price of HK$6.44 to reflect a wider NAV discount of 80% (previously 70%), taking into account the company’s debt metrics and the market’s interest-rate outlook.
Analysis
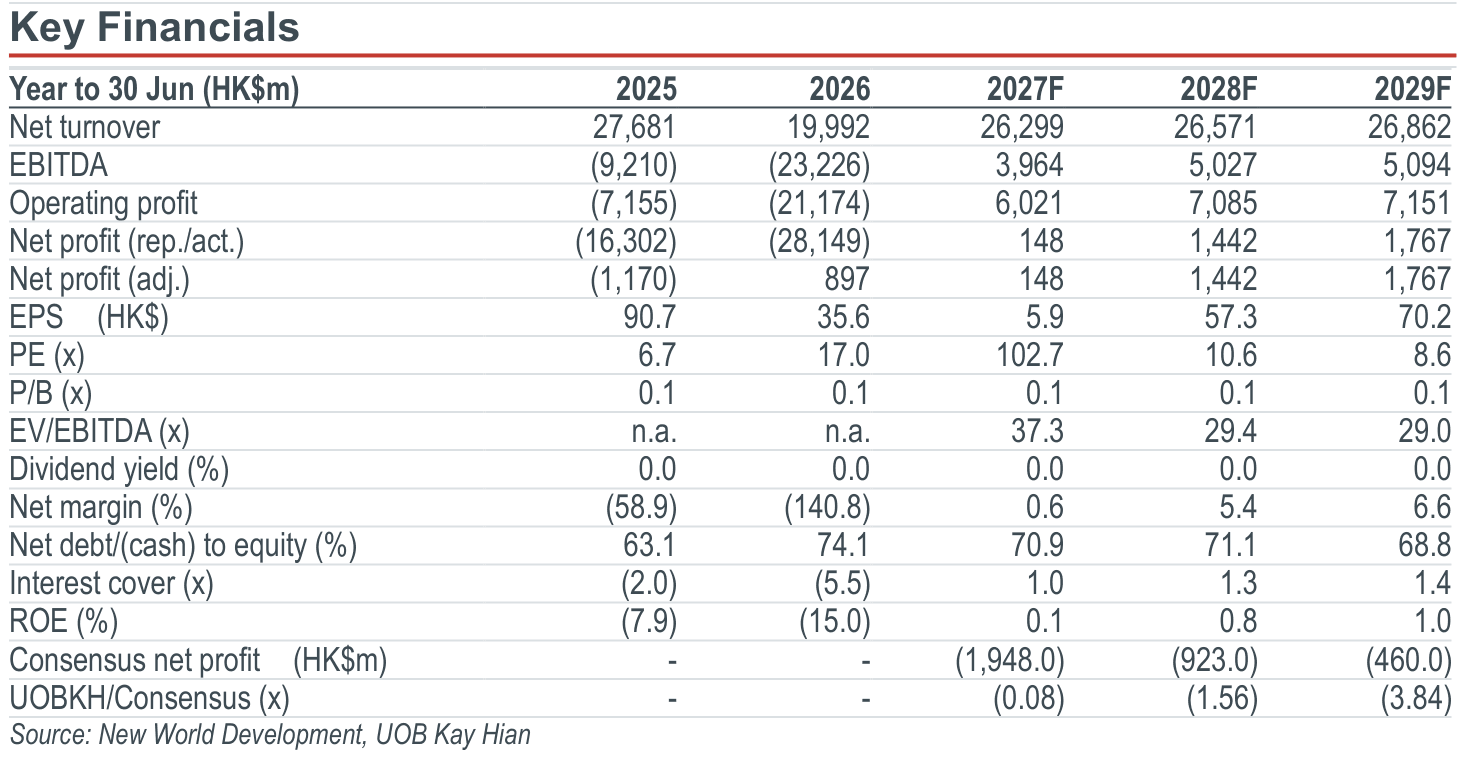
- Underlying net profit beat expectations; high provisions deepened net loss. In FY26, New World Development (NWD) reported HK$2.2b of underlying net profit from recurring and core operations (before minority interest and perps distribution), representing a turnaround from a loss of HK1.2b in FY25, beating market expectation of a loss of HK$2,125m. This is mainly thanks to: a) increase in profits from development and investment properties, and b) a 14.9% yoy decrease in finance costs. However, attributable net loss expanded 72.7% yoy to HK$28.2b in FY26, due to: a) HK$18.3b net impairment losses and provisions relating to the 11 SKIES project, and b) HK$8.0b impairment loss on property inventories. Net gearing ratio edged up 10.2ppt to 68.3% as cash declined 34.4% yoy to HK$17b as of Jun 26. The company continued to halt dividends and perps distribution.
HOLD (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$6.05
HK$6.44
6.4%
HK$9.60
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

23 Sept 2026
China Property: NBS Publishes Inaugural Second-Hand Transactions Data; Household Mortgage Borrowing Is Still Shrinking

8 Sept 2026
China Property: Shanghai Shifts Housing Supply From New Build To Renewal; National Land Supply Keeps Shrinking

30 Sept 2026
China Property: First Central Mortgage Interest Subsidy From 1 Oct 26; Tier 1 Land Supply Up 12% mom In Sep 26
Our latest research
2 Oct 2026
TA: CSPC Pharmaceutical Group (1093 HK) / China Resources Power Holdings (0836 HK)
30 Sept 2026
TA: Guming Holdings (1364 HK) / BYD Electronic (0285 HK)

29 Sept 2026