
Company Coverage
TAL Educational Group (TAL US) - 2QFY27: Revenue Miss And Strong Operating Leverage; Fair-value Loss Drags Net Profit
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
US$10.14
US$15.00
+47.9%
US$18.40
Analyst
Highlights
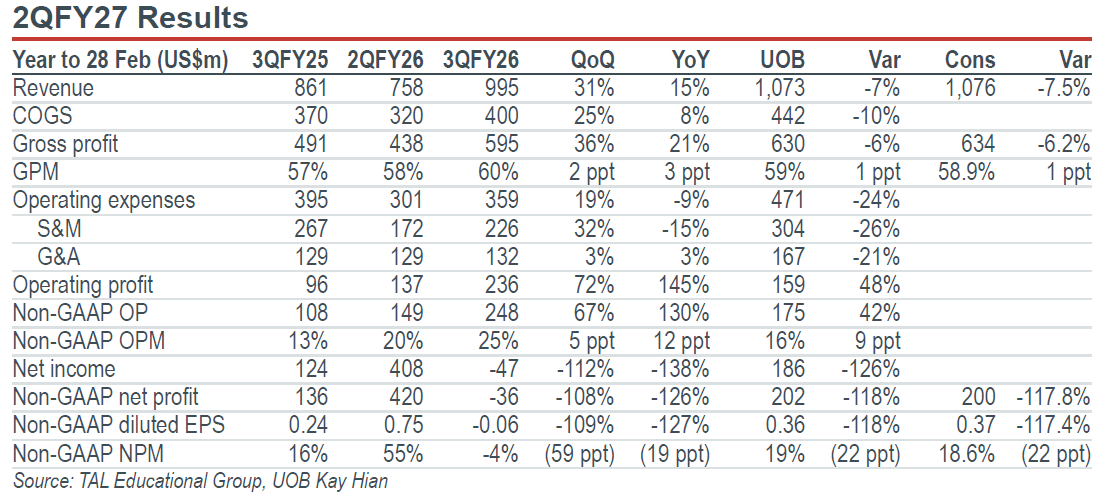
- TAL's 2QFY27 revenue grew 15% yoy to US$995m, 7% and 8% below our and consensus estimates. Non-GAAP operating profit more than doubled to US$248m, with operating margin expanding 12.4ppt yoy to 25% as S&M expenses fell 15% yoy. Non-GAAP net profit fell short of expectations and came in at losses of US$36m vs street’s estimate of US$200m due to fair-value loss on investments and tax charges.
- Maintain BUY with a lower target price of US$15.00.
Analysis
- Revenue growth moderates; below expectations. TAL Education Group's (TAL) revenue grew 15% yoy to US$995m in 2QFY27, decelerating from 32% yoy in 1QFY27 and 7% and 8% below our and consensus estimates. Growth was weighed down by weaker learning-device performance amid market contraction and intense competition, alongside moderating online enrichment growth, partly offset by healthy double-digit growth in Peiyou offline programmes, driven by enrolment gains. Management expects learning devices to remain a key drag on group revenue growth. Deferred revenue stood at US$930.4m at end-2QFY27, up 5.5% from end-FY26, supporting revenue visibility into 2HFY27.
- Better-than-expected margin expansion. Gross profit rose 21% yoy to US$595m in 2QFY27, with gross margin expanding 3ppt yoy to 60%. Non-GAAP operating margin widened 12ppt yoy to 25%, supported by higher gross margin and lower S&M expenses, partly offset by higher G&A expenses. S&M expenses declined 15% yoy to US$226m, bringing the expense ratio down 8ppt yoy to 23%, while G&A expenses rose 4% yoy to US$132m. non-GAAP operating profit reached US$248m, more than double the US$108m recorded in 2QFY26 and 42% above our estimate.
Highlights
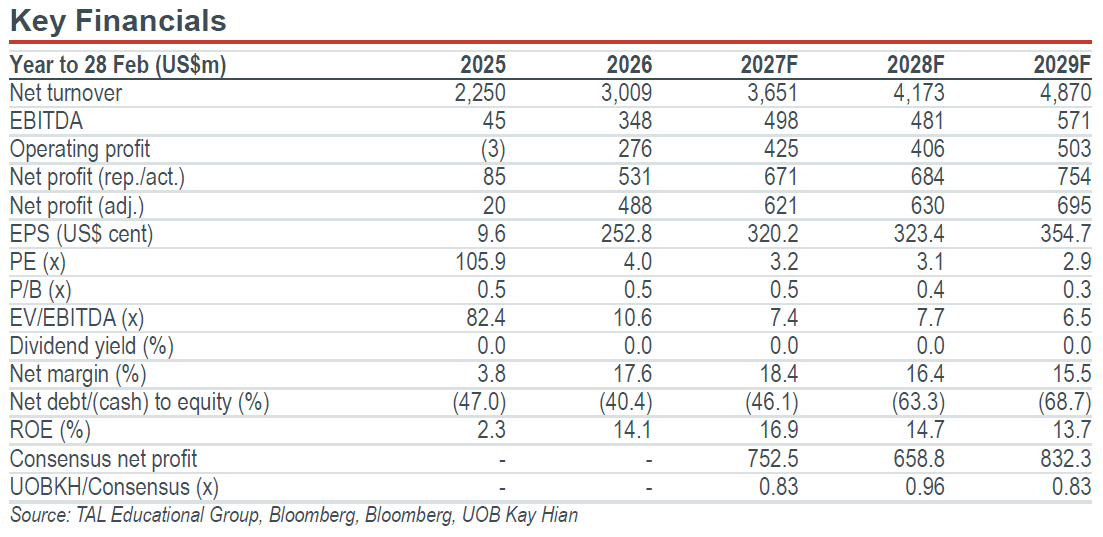
- TAL's 2QFY27 revenue grew 15% yoy to US$995m, 7% and 8% below our and consensus estimates. Non-GAAP operating profit more than doubled to US$248m, with operating margin expanding 12.4ppt yoy to 25% as S&M expenses fell 15% yoy. Non-GAAP net profit fell short of expectations and came in at losses of US$36m vs street’s estimate of US$200m due to fair-value loss on investments and tax charges.
- Maintain BUY with a lower target price of US$15.00.
Analysis
- Revenue growth moderates; below expectations. TAL Education Group's (TAL) revenue grew 15% yoy to US$995m in 2QFY27, decelerating from 32% yoy in 1QFY27 and 7% and 8% below our and consensus estimates. Growth was weighed down by weaker learning-device performance amid market contraction and intense competition, alongside moderating online enrichment growth, partly offset by healthy double-digit growth in Peiyou offline programmes, driven by enrolment gains. Management expects learning devices to remain a key drag on group revenue growth. Deferred revenue stood at US$930.4m at end-2QFY27, up 5.5% from end-FY26, supporting revenue visibility into 2HFY27.
- Better-than-expected margin expansion. Gross profit rose 21% yoy to US$595m in 2QFY27, with gross margin expanding 3ppt yoy to 60%. Non-GAAP operating margin widened 12ppt yoy to 25%, supported by higher gross margin and lower S&M expenses, partly offset by higher G&A expenses. S&M expenses declined 15% yoy to US$226m, bringing the expense ratio down 8ppt yoy to 23%, while G&A expenses rose 4% yoy to US$132m. non-GAAP operating profit reached US$248m, more than double the US$108m recorded in 2QFY26 and 42% above our estimate.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
US$10.14
US$15.00
+47.9%
US$18.40
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

2 Nov 2026
Inner Mongolia Yili Industrial Group (600887 CH) - 3Q26: Revenue Misses But Operating Margin Expansion Continues; Reiterates MSD Revenue Growth Target For 2026

2 Nov 2026
China Tourism Group Duty Free (601888 CH) - 3Q26: Results Miss Expectations

2 Nov 2026
Kweichow Moutai (600519 CH) - 3Q26: Results In Line; Direct Sales Up 40% On i-Moutai Growth
Our latest research
2 Nov 2026
China Tourism Group Duty Free (601888 CH) - 3Q26: Results Miss Expectations
2 Nov 2026
Inner Mongolia Yili Industrial Group (600887 CH) - 3Q26: Revenue Misses But Operating Margin Expansion Continues; Reiterates MSD Revenue Growth Target For 2026

2 Nov 2026