
Analyst
Elena Chen
elena.chen@uobkh.comAnalyst
Qi Wang, CFA
qi.wang@uobkh.comAnalyst
In collaboration with UOBKH Institutional Research
Key China Market Indices
Index | Price | Past 2-Week Return | YTD Return |
Hang Seng Index | 24,482 | 6.0% | -4.5% |
HSCEI Index | 8,274 | 6.7% | -7.2% |
Hang Seng Tech Index | 4,078 | 5.3% | -26.1% |
Shanghai Composite Index | 3,649 | -1.1% | -8.1% |
CSI 300 Index | 4,054 | -1.2% | -12.4% |
Source: UOB Kay Hian and iFinD, as of Nov 6, 2026
- Hong Kong stocks have recently outperformed A-shares. The Hang Seng Index gained 6.0%, while the CSI 300 fell 1.2% over the past two weeks. On Nov 5 alone, Hong Kong-listed internet shares led the Hang Seng Index’s 3.7% rally as the overhang from the US midterm elections lifted. However, some AI hardware stocks fell that day on concerns over potentially tighter data centres restrictions in some US states. Projects already underway are likely to keep buying equipment as planned, while those still awaiting approval could see orders delayed - creating uncertainty for Chinese suppliers.
- Hong Kong consumer names rallied despite continuing weak demand. Consumer stocks also led the market over the past two weeks. Mainland retail sales growth picked up to 1.1% yoy in September, but weak home prices continue to weigh on household wealth and make families more cautious about big-ticket purchases. With limited direct support for consumption, we see little reason to turn positive on Chinese consumption based solely on a temporary pickup in retail sales. We suggest investors stay selective and avoid chasing the sector’s relief rally.
- China’s A-share support is starting to reach the market. On Nov 6, six Chinese brokers made their first stock purchases under the PBOC’s RMB 100bn swap operation announced on Nov 3. Separately, on Nov 4 the PBOC cut the relending rate for share buybacks and stake increases by 25bp to 1%. Banks had applied for more than RMB 200bn under the relending programme. We expect large-cap A-shares to benefit the most, with state-backed buying concentrated in CSI 300-linked ETFs and swap funding potentially favoring higher-dividend-yield stocks. These flows can cushion any further sell-offs, while weak domestic demand still limits a broad recovery.
- Selectivity is key: buy defensive yield plays and get paid to wait. We favour China Mobile (0941.HK, 6.7% dividend yield), PetroChina (0857.HK, 5.6% yield), Midea (0300.HK, 4.4% yield) and the Central SOE High Dividend Yield ETF (3437.HK, 7.1% yield). These securities provide attractive income and help cushion downside while we wait for a broader recovery. China Mobile, PetroChina and Midea are all Core Recommendations, while the SOE High Dividend Yield ETF is an Investment Opportunity.
- Best-performing sectors: Conglomerates +8.1% (0001.HK, 0267.HK, 0019.HK), Consumer Staples +7.4% (2319.HK, 9633.HK, 0291.HK) and Consumer Discretionary +7.2% (9988.HK, 3690.HK, 9618.HK).
- Potential movers and shakers: Details inside.
Positive | BYD (1211.HK), CR Land (1109.HK) |
Neutral | COLI (0688.HK), CR Land (1109.HK), Longfor (0960.HK) |
Negative | - |
- Must Watch Events: Details below.
Date | Macro Data | Sector / Company Events |
Nov 10 | China Oct Exports & Imports YoY |
|
Nov 13 | Hong Kong 3Q GDP revision and updated 2026 forecast |
|
Nov 16 | China Oct activity data, including retail sales, industrial production and fixed asset investment |
|
Nov 17 |
| JD.com (9618.HK) 3Q2026 results |
Nov 18 | China APEC Economic Leaders’ Meeting (Nov 18- Nov 19) | Tencent (0700.HK) 3Q2026 results; Nvidia CEO Jensen Huang House Briefing (est) |
Nov 19 |
| Alibaba (9988.HK) 2QFY2027 results |
Best 3 Hang Seng Sectors (Past 2 Weeks)
Hang Seng Sector Index | Past 2-Week Return | YTD Return | Stock Drivers Past 2-Weeks |
Conglomerates | 8.1% | 27.2% | CK Hutchison Holdings Limited (0001.HK) +9.1%, CITIC Limited (0267.HK) +8%, Swire Pacific Ltd. (0019.HK) +8.4% |
Consumer Staples | 7.4% | -12.4% | China Mengniu Dairy Company Limited (2319.HK) +14.9%, Nongfu Spring Co., Ltd. (9633.HK) +8.9%, China Resources Beer (Holdings) Company Limited (0291.HK) +8% |
Consumer Discretionary | 7.2% | -23.7% | Alibaba Group Holding Limited (9988.HK) +7.3%, Meituan (3690.HK) +12.2%, JD.Com, Inc. (9618.HK) +13.3% |
Source: UOB Kay Hian and iFinD, as of Nov 6, 2026
- Conglomerates rose 8.1% over two weeks, taking the YTD return to 27.2%. CK Hutchison, CITIC and Swire Pacific have all gained significantly. Conglomerates was one of only three sectors already in positive territory YTD before this period, underscoring its resilience in a challenging market.
- Consumer Staples rose 7.4% over two weeks, narrowing the YTD decline to 12.4%. Gains were led by Mengniu but also extended broadly across dairy, beverages and beer. Better-than-expected pricing and sales of its premium milk support Mengniu’s 2026 operating margin target of at least 8% (2025: 8.0%). That said, we remain cautious on Chinese consumption until we see a sustained sales recovery across more consumer staples companies.
- Consumer Discretionary rose 7.2% over two weeks, trimming its YTD decline to 23.7%. Meituan and JD.com were among the strongest platform names. However, fundamentals remained muted, as first-phase Singles’ Day transaction value across major e-commerce platforms grew just 4% yoy (excluding instant retail), broadly in line with expectations. We see the sector’s gains as a relief rally, rather than the start of a sustained recovery.
Worst 3 Hang Seng Sectors (Past 2 Weeks)
Hang Seng Sector Index | Past 2-Week Return | YTD Return | Stock Drivers Past 2-Weeks |
Financials | 3.5% | 8.7% | HSBC Holdings Plc (0005.HK) -3%, Guotai Haitong Securities Co., Ltd. (2611.HK) -3.8%, Huatai Securities Co., Ltd. (6886.HK) -3.7% |
Industrials | 0.5% | -7.0% | Weichai Power Co.,Ltd. (2338.HK) -10.7%, Kingboard Laminates Holdings Ltd. (1888.HK) -19.4%, Kingboard Holdings Limited (0148.HK) -12.7% |
Materials | -0.1% | -27.3% | Jiangxi Copper Company Limited (0358.HK) -16.2%, CMOC Group Limited (3993.HK) -7.4%, Zijin Mining Group Company Limited (2899.HK) -1.9% |
Source: UOB Kay Hian and iFinD, as of Nov 6, 2026
- Financials rose 3.5% over two weeks, taking their YTD gain to 8.7%. “High-dividend” mainland banks supported the sector as investors turned more defensive in late Oct. The sector gained 1.6% in the week to Oct 30, outperforming Hang Seng’s 0.9% rise, with steady 3Q bank results also lending support. However, banks’ low beta limited their upside in the market rally. Financials gained only 3.5% over in the last two weeks, trailing the Hang Seng Index’s 6.0% surge.
- Industrials rose 0.5% over two weeks, leaving the sector down 7.0% YTD. China’s heavy-truck wholesale sales fell 13% yoy in Oct, clouding the outlook for truck and engine makers. Weichai fell 10.7% amid concerns over potential delays to US data centre projects, despite a 13.9% yoy increase in 3Q net profit excluding non-recurring items. Electronics suppliers also came under pressure, with both Kingboard stocks (0148.HK and 1888.HK) caught in the Nov 6 sell-off in AI hardware.
- Materials fell 0.1% over two weeks, taking the YTD decline to 27.3%. LME copper fell 2.7% in the week to Nov 6 as investors reassessed copper demand from US data centres. In China, falling inventories and lower smelter output pushed the import premium to a record USD 220 per tonne. Tight local supply supported that premium, while falling global copper prices weighed on the earnings outlook for miners.
Southbound Trading Summary (Past 2 Weeks)
(HKD millions) | Ticker | Total Buy | Total Sell | Net Buy (Sell) | % of Total Turnover | Past 2-Week Return | Data |
Southbound Total | HSHKI.HK | 405,799 | 420,072 | (14,273) | 34% | 4.7% | Full |
TENCENT | 0700.HK | 19,642 | 21,672 | (2,030) | 22% | 8.8% | Full |
Tracker Fund | 02800.HK | 16,619 | 13,755 | 2,864 | 18% | 3.5% | Partial |
SMIC | 0981.HK | 14,864 | 15,501 | (637) | 38% | -3.1% | Full |
Z.AI | 2513.HK | 14,114 | 11,930 | 2,184 | 41% | -14.6% | Partial |
YOFC | 6869.HK | 11,413 | 12,895 | (1,482) | 44% | -23.3% | Partial |
XIAOMI-W | 1810.HK | 7,458 | 14,687 | (7,229) | 21% | 13.4% | Partial |
BABA-W | 9988.HK | 9,558 | 12,037 | (2,478) | 17% | 7.3% | Partial |
CNOOC | 0883.HK | 7,219 | 7,308 | (89) | 48% | 1.6% | Partial |
KB LAMINATES | 1888.HK | 6,388 | 7,022 | (635) | 42% | -19.4% | Partial |
MINIMAX-W | 0100.HK | 4,827 | 4,505 | 322 | 45% | -17.0% | Partial |
Source: UOB Kay Hian and iFinD, as of Nov 6, 2026.
Note: Based on the two-week period from Oct 26 to Nov 6, 2026. For Stock Connect Southbound trading, only the top 10 most actively traded securities are disclosed. “Full data” means the stock appeared on the top 10 list for each of the past few trading days. “Partial data” means otherwise.
- Southbound selling eased as overseas inflows picked up. Southbound net selling narrowed to HKD 14.27bn over the last two weeks from HKD 23.68bn in the previous period. Meanwhile, offshore funds tracked by EPFR recorded net inflows of USD 1.51bn in the seven days to Nov 4, with about 90% going into index funds. This points to a notable return of overseas capital, even as mainland investors remained net sellers overall.
- The Tracker Fund led buying, while AI flows were mixed. The Tracker Fund (2800.HK) drew the most net inflows, likely signaling “National Team” buying. Mainland investors also bought selected AI model developers Z.AI and MiniMax on dips, as the shares fell roughly 15-17%. In hardware, YOFC and Kingboard Laminates both saw net selling and steeper declines.
- Southbound buyers returned to Tencent and Alibaba on the Nov 6 pullback. Both stocks saw net selling in the last two weeks but together drew HKD 1.36bn in net buying on Nov 6 as shares fell. Separately, Xiaomi saw net selling that day and recorded the largest outflow over the two weeks, despite gaining 13.4%.
Stocks: Potential Movers and Shakers
Please note that not all stocks mentioned below are recommended by PWM Research / CIO Office. Please refer to the Appendix for our China Stock Model Portfolio and official recommendations. Equity investing involves significant risk. Investor discretion is advised.
Stock | Sector | PWM Research Recommendation | Type of News | Our Read on the News |
BYD | Consumer Discretionary | No Recommendation | Sales / Products | Positive |
- October sales hit a year-to-date high, but a faster pace is needed to meet our full-year estimate. BYD sold 490,168 vehicles in Oct, up 11.0% yoy and 5.7% mom. Sales for the first ten months still fell 2.2% yoy to 3,621,744 units. To reach our 2026 estimate of 4.75m units (+3.2% yoy), BYD would need to sell an average of 564,128 vehicles a month in Nov and Dec, 15% above Oct’s level.
- Exports doubled as domestic sales fell. NEV exports rose 102.8% yoy to 170,194 units in Oct, accounting for 34.7% of total sales, while domestic sales fell 10.6% yoy to 319,974 units. Exports fell 5.8% mom, but overseas sales for the first ten months still rose 93.8% yoy to 1,513,154 units, reaching 76% of our 2026 estimate of 2m units (+91.2% yoy).
- BEVs accounted for nearly two-thirds of passenger vehicle sales. Passenger BEV sales rose 37.4% yoy to a record 305,743 units in Oct, while PHEV sales fell 17.2%. BEVs made up 63.3% of passenger vehicle sales, up from 51.0% a year earlier. The second-generation Seal 07 launched on Nov 5 at RMB 139,900-172,900, with the BEV entry price 12% below its March level.
- Maintain BUY on BYD with a target price of HK$100, pegged to 15x 2027F PE. (Zeng Sheng Di)
Stock | Sector | PWM Research Recommendation | Type of News | Our Read on the News |
COLI (0688.HK) | Real Estate | No Recommendation for all three | Sales / Products | Neutral |
- Top 100 developers' sales remained around 15% below last year’s. Gross sales of the top 100 mainland developers totalled RMB 2,358bn in 10M2026, down 14.9% yoy, or down 15.5% yoy on the 82 developers that were in the top 100 in both years, slightly worse than the 15.4% decline in 9M2026. Sales area fell 18.3% yoy to 111.0m sqm, a steeper decline than that in sales value. For the same 82 developers, Oct sales fell 16.7% yoy and were flat mom.
- Sales became more concentrated, with COLI and CR Land gaining. The top 10 accounted for 52.6% of top-100 sales in 10M2026, up 3.9ppt yoy. Only 18 of the 82 developers managed to grow sales. COLI and CR Land recorded gains of 5.1% and 6.3%, respectively, while Longfor’s sales fell 54.1%. In Oct alone, CR Land’s sales rose 3.3% yoy to RMB 15.7bn, while COLI’s fell 4.6% to RMB 17.8bn.
- Maintain UNDERWEIGHT on China's property sector. Presale approvals have tightened since September as local governments roll out reforms. We expect this to constrain new-home supply and weigh on new-home sales over the next 12 months, while secondary-home sales in core cities continue to grow. We prefer developers with low reliance on presale proceeds and strong exposure to Tier 1 cities. COLI remains our top pick. (Liu Jieqi/ Damon Shen)
Stock | Sector | PWM Research Recommendation | Type of News | Our Read on the News |
CR Land (1109.HK) | Real Estate | No Recommendation | Sales / Products | Positive |
- Same-store sales improved over National Day after a flat September. Based on our channel check with CR Mixc (1209 HK), we expect that tenant sales across CR Mixc malls grew by double digits yoy in 9M2026, with same-store sales up by mid-single digits (1H2026: +10.2%) and luxury malls outperforming. We estimate growth eased gradually from a strong 1Q2026; in Sep 2026, overall retail sales was expected to grow by high single digits yoy while same-store sales were expected to be flat, below the 1.1% growth in national retail sales. National Day holiday sales improved, with total sales up by double digits and same-store sales up by mid-single digits, although luxury malls lagged.
- Approval of the third Mixc C-REIT supports CR Land’s capital recycling. On Nov 2, the CSRC approved the registration of the ChinaAMC CR Land Closed-end Commercial Real Estate Fund. According to the draft prospectus filed in April, the underlying assets are Nantong Mixc and Linyi Mixc One, with expected fundraising of about RMB 5.41bn. It follows the Qingdao Mixc consumption REIT listed in Mar 2024 and the Chengdu Mixc inter-bank REIT listed in Jul 2026, and management expects to exit about five malls a year during the 15th Five-Year Plan period.
- Maintain BUY on CR Land with a target price of HK$39.60. We expect retail sales at CR Mixc malls to grow by double digits in 2026. We see CR Land as an early mover in using REITs to recycle capital from mature malls. (Liu Jieqi/ Damon Shen)
Type of News | Explanation |
Channel Checks | Industry-wide or supply chain news with implications to a particular sector or company |
Corporate Action | Dividends, special dividends, stock splits, share buybacks, equity / bond financing, M&As, spin-offs and restructuring etc. |
Earnings | Quarterly earnings for US-listed companies. Semi-annual earnings for Hong Kong-listed companies |
Insider Dealing | Company insiders’ buying / selling of stocks and derivatives of the company |
Investor Action | Lead investor buying / selling including activist investor actions |
Investor Roadshow | Deal and non-deal roadshows, reverse roadshows (analyst days), and company meetings at investment conferences |
Legal / Regulatory | Lawsuits, legislature/regulation changes, other regulatory events |
Macro / Industry Data | Regular economic or industry data related to the sector or stock |
Sales / Products | Sales or product related news, such as monthly sales or new product launches |
Public Event | Public speeches and appearances by companies in the media or industry conferences |
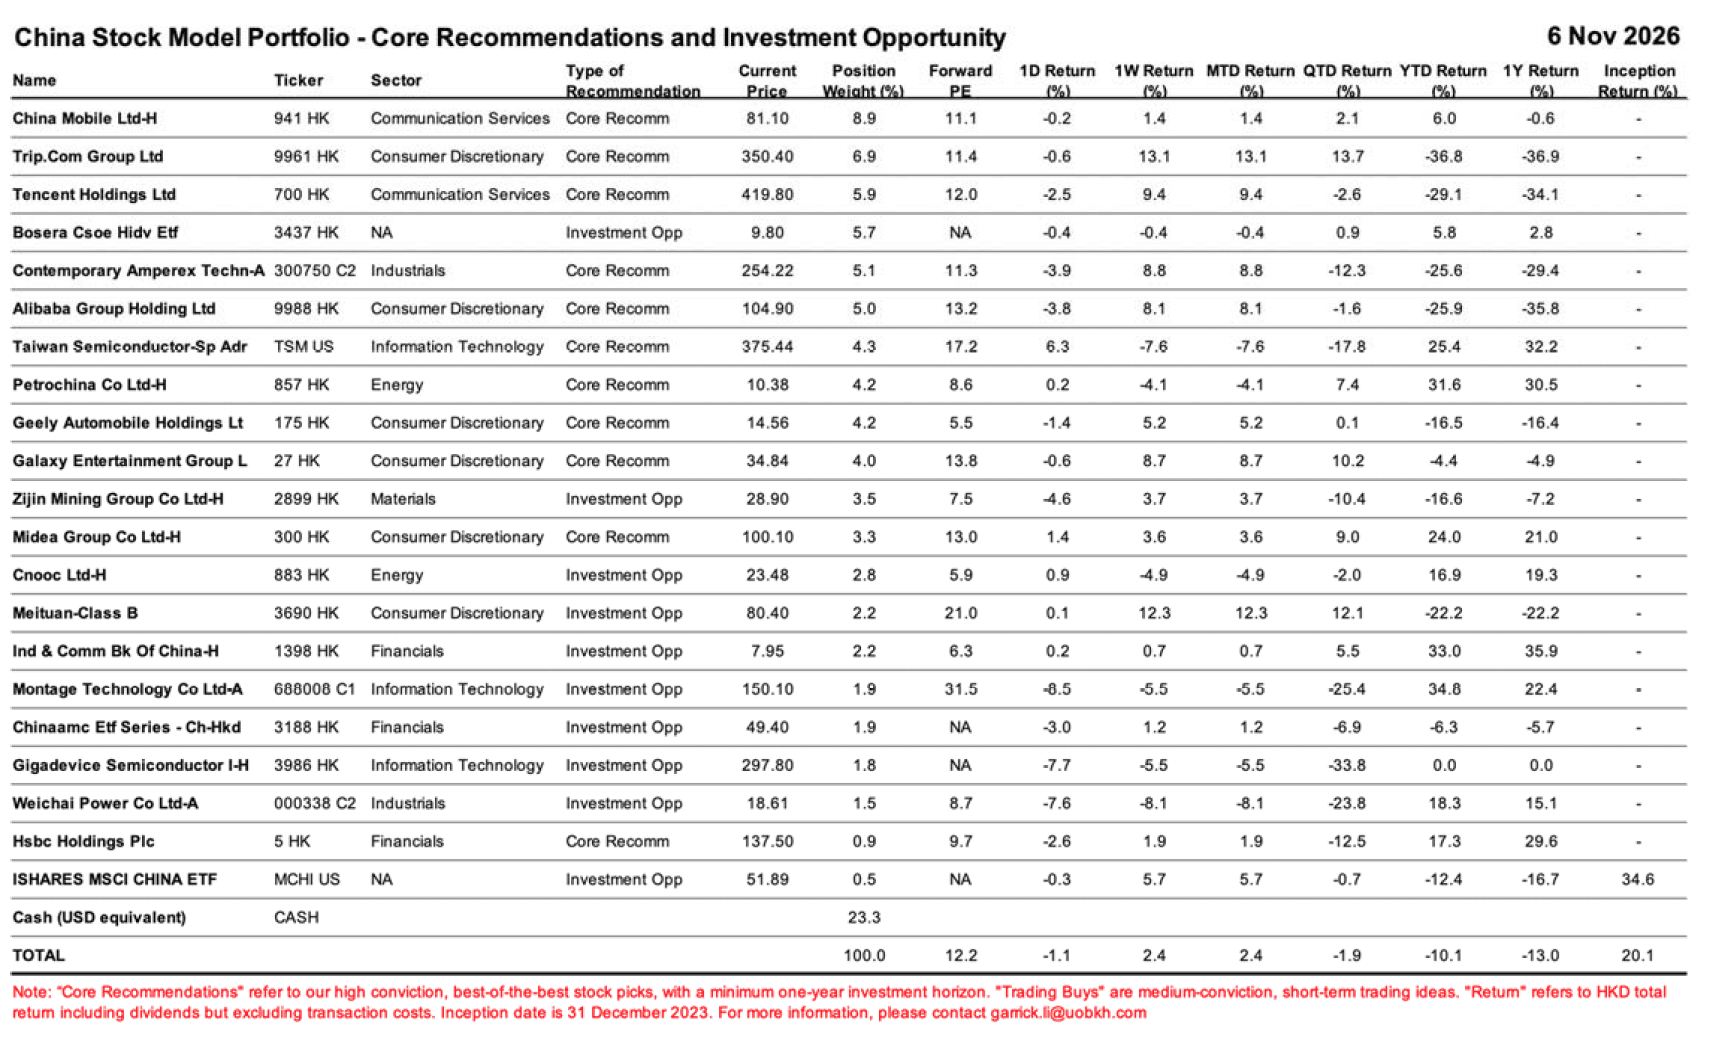
Appendix - China Stock Model Portfolio (Nov 6 Reference)
Key China Market Indices
Index | Price | Past 2-Week Return | YTD Return |
Hang Seng Index | 24,482 | 6.0% | -4.5% |
HSCEI Index | 8,274 | 6.7% | -7.2% |
Hang Seng Tech Index | 4,078 | 5.3% | -26.1% |
Shanghai Composite Index | 3,649 | -1.1% | -8.1% |
CSI 300 Index | 4,054 | -1.2% | -12.4% |
Source: UOB Kay Hian and iFinD, as of Nov 6, 2026
- Hong Kong stocks have recently outperformed A-shares. The Hang Seng Index gained 6.0%, while the CSI 300 fell 1.2% over the past two weeks. On Nov 5 alone, Hong Kong-listed internet shares led the Hang Seng Index’s 3.7% rally as the overhang from the US midterm elections lifted. However, some AI hardware stocks fell that day on concerns over potentially tighter data centres restrictions in some US states. Projects already underway are likely to keep buying equipment as planned, while those still awaiting approval could see orders delayed - creating uncertainty for Chinese suppliers.
- Hong Kong consumer names rallied despite continuing weak demand. Consumer stocks also led the market over the past two weeks. Mainland retail sales growth picked up to 1.1% yoy in September, but weak home prices continue to weigh on household wealth and make families more cautious about big-ticket purchases. With limited direct support for consumption, we see little reason to turn positive on Chinese consumption based solely on a temporary pickup in retail sales. We suggest investors stay selective and avoid chasing the sector’s relief rally.
- China’s A-share support is starting to reach the market. On Nov 6, six Chinese brokers made their first stock purchases under the PBOC’s RMB 100bn swap operation announced on Nov 3. Separately, on Nov 4 the PBOC cut the relending rate for share buybacks and stake increases by 25bp to 1%. Banks had applied for more than RMB 200bn under the relending programme. We expect large-cap A-shares to benefit the most, with state-backed buying concentrated in CSI 300-linked ETFs and swap funding potentially favoring higher-dividend-yield stocks. These flows can cushion any further sell-offs, while weak domestic demand still limits a broad recovery.
- Selectivity is key: buy defensive yield plays and get paid to wait. We favour China Mobile (0941.HK, 6.7% dividend yield), PetroChina (0857.HK, 5.6% yield), Midea (0300.HK, 4.4% yield) and the Central SOE High Dividend Yield ETF (3437.HK, 7.1% yield). These securities provide attractive income and help cushion downside while we wait for a broader recovery. China Mobile, PetroChina and Midea are all Core Recommendations, while the SOE High Dividend Yield ETF is an Investment Opportunity.
- Best-performing sectors: Conglomerates +8.1% (0001.HK, 0267.HK, 0019.HK), Consumer Staples +7.4% (2319.HK, 9633.HK, 0291.HK) and Consumer Discretionary +7.2% (9988.HK, 3690.HK, 9618.HK).
- Potential movers and shakers: Details inside.
Positive | BYD (1211.HK), CR Land (1109.HK) |
Neutral | COLI (0688.HK), CR Land (1109.HK), Longfor (0960.HK) |
Negative | - |
- Must Watch Events: Details below.
Date | Macro Data | Sector / Company Events |
Nov 10 | China Oct Exports & Imports YoY |
|
Nov 13 | Hong Kong 3Q GDP revision and updated 2026 forecast |
|
Nov 16 | China Oct activity data, including retail sales, industrial production and fixed asset investment |
|
Nov 17 |
| JD.com (9618.HK) 3Q2026 results |
Nov 18 | China APEC Economic Leaders’ Meeting (Nov 18- Nov 19) | Tencent (0700.HK) 3Q2026 results; Nvidia CEO Jensen Huang House Briefing (est) |
Nov 19 |
| Alibaba (9988.HK) 2QFY2027 results |
Best 3 Hang Seng Sectors (Past 2 Weeks)
Hang Seng Sector Index | Past 2-Week Return | YTD Return | Stock Drivers Past 2-Weeks |
Conglomerates | 8.1% | 27.2% | CK Hutchison Holdings Limited (0001.HK) +9.1%, CITIC Limited (0267.HK) +8%, Swire Pacific Ltd. (0019.HK) +8.4% |
Consumer Staples | 7.4% | -12.4% | China Mengniu Dairy Company Limited (2319.HK) +14.9%, Nongfu Spring Co., Ltd. (9633.HK) +8.9%, China Resources Beer (Holdings) Company Limited (0291.HK) +8% |
Consumer Discretionary | 7.2% | -23.7% | Alibaba Group Holding Limited (9988.HK) +7.3%, Meituan (3690.HK) +12.2%, JD.Com, Inc. (9618.HK) +13.3% |
Source: UOB Kay Hian and iFinD, as of Nov 6, 2026
- Conglomerates rose 8.1% over two weeks, taking the YTD return to 27.2%. CK Hutchison, CITIC and Swire Pacific have all gained significantly. Conglomerates was one of only three sectors already in positive territory YTD before this period, underscoring its resilience in a challenging market.
- Consumer Staples rose 7.4% over two weeks, narrowing the YTD decline to 12.4%. Gains were led by Mengniu but also extended broadly across dairy, beverages and beer. Better-than-expected pricing and sales of its premium milk support Mengniu’s 2026 operating margin target of at least 8% (2025: 8.0%). That said, we remain cautious on Chinese consumption until we see a sustained sales recovery across more consumer staples companies.
- Consumer Discretionary rose 7.2% over two weeks, trimming its YTD decline to 23.7%. Meituan and JD.com were among the strongest platform names. However, fundamentals remained muted, as first-phase Singles’ Day transaction value across major e-commerce platforms grew just 4% yoy (excluding instant retail), broadly in line with expectations. We see the sector’s gains as a relief rally, rather than the start of a sustained recovery.
Worst 3 Hang Seng Sectors (Past 2 Weeks)
Hang Seng Sector Index | Past 2-Week Return | YTD Return | Stock Drivers Past 2-Weeks |
Financials | 3.5% | 8.7% | HSBC Holdings Plc (0005.HK) -3%, Guotai Haitong Securities Co., Ltd. (2611.HK) -3.8%, Huatai Securities Co., Ltd. (6886.HK) -3.7% |
Industrials | 0.5% | -7.0% | Weichai Power Co.,Ltd. (2338.HK) -10.7%, Kingboard Laminates Holdings Ltd. (1888.HK) -19.4%, Kingboard Holdings Limited (0148.HK) -12.7% |
Materials | -0.1% | -27.3% | Jiangxi Copper Company Limited (0358.HK) -16.2%, CMOC Group Limited (3993.HK) -7.4%, Zijin Mining Group Company Limited (2899.HK) -1.9% |
Source: UOB Kay Hian and iFinD, as of Nov 6, 2026
- Financials rose 3.5% over two weeks, taking their YTD gain to 8.7%. “High-dividend” mainland banks supported the sector as investors turned more defensive in late Oct. The sector gained 1.6% in the week to Oct 30, outperforming Hang Seng’s 0.9% rise, with steady 3Q bank results also lending support. However, banks’ low beta limited their upside in the market rally. Financials gained only 3.5% over in the last two weeks, trailing the Hang Seng Index’s 6.0% surge.
- Industrials rose 0.5% over two weeks, leaving the sector down 7.0% YTD. China’s heavy-truck wholesale sales fell 13% yoy in Oct, clouding the outlook for truck and engine makers. Weichai fell 10.7% amid concerns over potential delays to US data centre projects, despite a 13.9% yoy increase in 3Q net profit excluding non-recurring items. Electronics suppliers also came under pressure, with both Kingboard stocks (0148.HK and 1888.HK) caught in the Nov 6 sell-off in AI hardware.
- Materials fell 0.1% over two weeks, taking the YTD decline to 27.3%. LME copper fell 2.7% in the week to Nov 6 as investors reassessed copper demand from US data centres. In China, falling inventories and lower smelter output pushed the import premium to a record USD 220 per tonne. Tight local supply supported that premium, while falling global copper prices weighed on the earnings outlook for miners.
Southbound Trading Summary (Past 2 Weeks)
(HKD millions) | Ticker | Total Buy | Total Sell | Net Buy (Sell) | % of Total Turnover | Past 2-Week Return | Data |
Southbound Total | HSHKI.HK | 405,799 | 420,072 | (14,273) | 34% | 4.7% | Full |
TENCENT | 0700.HK | 19,642 | 21,672 | (2,030) | 22% | 8.8% | Full |
Tracker Fund | 02800.HK | 16,619 | 13,755 | 2,864 | 18% | 3.5% | Partial |
SMIC | 0981.HK | 14,864 | 15,501 | (637) | 38% | -3.1% | Full |
Z.AI | 2513.HK | 14,114 | 11,930 | 2,184 | 41% | -14.6% | Partial |
YOFC | 6869.HK | 11,413 | 12,895 | (1,482) | 44% | -23.3% | Partial |
XIAOMI-W | 1810.HK | 7,458 | 14,687 | (7,229) | 21% | 13.4% | Partial |
BABA-W | 9988.HK | 9,558 | 12,037 | (2,478) | 17% | 7.3% | Partial |
CNOOC | 0883.HK | 7,219 | 7,308 | (89) | 48% | 1.6% | Partial |
KB LAMINATES | 1888.HK | 6,388 | 7,022 | (635) | 42% | -19.4% | Partial |
MINIMAX-W | 0100.HK | 4,827 | 4,505 | 322 | 45% | -17.0% | Partial |
Source: UOB Kay Hian and iFinD, as of Nov 6, 2026.
Note: Based on the two-week period from Oct 26 to Nov 6, 2026. For Stock Connect Southbound trading, only the top 10 most actively traded securities are disclosed. “Full data” means the stock appeared on the top 10 list for each of the past few trading days. “Partial data” means otherwise.
- Southbound selling eased as overseas inflows picked up. Southbound net selling narrowed to HKD 14.27bn over the last two weeks from HKD 23.68bn in the previous period. Meanwhile, offshore funds tracked by EPFR recorded net inflows of USD 1.51bn in the seven days to Nov 4, with about 90% going into index funds. This points to a notable return of overseas capital, even as mainland investors remained net sellers overall.
- The Tracker Fund led buying, while AI flows were mixed. The Tracker Fund (2800.HK) drew the most net inflows, likely signaling “National Team” buying. Mainland investors also bought selected AI model developers Z.AI and MiniMax on dips, as the shares fell roughly 15-17%. In hardware, YOFC and Kingboard Laminates both saw net selling and steeper declines.
- Southbound buyers returned to Tencent and Alibaba on the Nov 6 pullback. Both stocks saw net selling in the last two weeks but together drew HKD 1.36bn in net buying on Nov 6 as shares fell. Separately, Xiaomi saw net selling that day and recorded the largest outflow over the two weeks, despite gaining 13.4%.
Stocks: Potential Movers and Shakers
Please note that not all stocks mentioned below are recommended by PWM Research / CIO Office. Please refer to the Appendix for our China Stock Model Portfolio and official recommendations. Equity investing involves significant risk. Investor discretion is advised.
Stock | Sector | PWM Research Recommendation | Type of News | Our Read on the News |
BYD | Consumer Discretionary | No Recommendation | Sales / Products | Positive |
- October sales hit a year-to-date high, but a faster pace is needed to meet our full-year estimate. BYD sold 490,168 vehicles in Oct, up 11.0% yoy and 5.7% mom. Sales for the first ten months still fell 2.2% yoy to 3,621,744 units. To reach our 2026 estimate of 4.75m units (+3.2% yoy), BYD would need to sell an average of 564,128 vehicles a month in Nov and Dec, 15% above Oct’s level.
- Exports doubled as domestic sales fell. NEV exports rose 102.8% yoy to 170,194 units in Oct, accounting for 34.7% of total sales, while domestic sales fell 10.6% yoy to 319,974 units. Exports fell 5.8% mom, but overseas sales for the first ten months still rose 93.8% yoy to 1,513,154 units, reaching 76% of our 2026 estimate of 2m units (+91.2% yoy).
- BEVs accounted for nearly two-thirds of passenger vehicle sales. Passenger BEV sales rose 37.4% yoy to a record 305,743 units in Oct, while PHEV sales fell 17.2%. BEVs made up 63.3% of passenger vehicle sales, up from 51.0% a year earlier. The second-generation Seal 07 launched on Nov 5 at RMB 139,900-172,900, with the BEV entry price 12% below its March level.
- Maintain BUY on BYD with a target price of HK$100, pegged to 15x 2027F PE. (Zeng Sheng Di)
Stock | Sector | PWM Research Recommendation | Type of News | Our Read on the News |
COLI (0688.HK) | Real Estate | No Recommendation for all three | Sales / Products | Neutral |
- Top 100 developers' sales remained around 15% below last year’s. Gross sales of the top 100 mainland developers totalled RMB 2,358bn in 10M2026, down 14.9% yoy, or down 15.5% yoy on the 82 developers that were in the top 100 in both years, slightly worse than the 15.4% decline in 9M2026. Sales area fell 18.3% yoy to 111.0m sqm, a steeper decline than that in sales value. For the same 82 developers, Oct sales fell 16.7% yoy and were flat mom.
- Sales became more concentrated, with COLI and CR Land gaining. The top 10 accounted for 52.6% of top-100 sales in 10M2026, up 3.9ppt yoy. Only 18 of the 82 developers managed to grow sales. COLI and CR Land recorded gains of 5.1% and 6.3%, respectively, while Longfor’s sales fell 54.1%. In Oct alone, CR Land’s sales rose 3.3% yoy to RMB 15.7bn, while COLI’s fell 4.6% to RMB 17.8bn.
- Maintain UNDERWEIGHT on China's property sector. Presale approvals have tightened since September as local governments roll out reforms. We expect this to constrain new-home supply and weigh on new-home sales over the next 12 months, while secondary-home sales in core cities continue to grow. We prefer developers with low reliance on presale proceeds and strong exposure to Tier 1 cities. COLI remains our top pick. (Liu Jieqi/ Damon Shen)
Stock | Sector | PWM Research Recommendation | Type of News | Our Read on the News |
CR Land (1109.HK) | Real Estate | No Recommendation | Sales / Products | Positive |
- Same-store sales improved over National Day after a flat September. Based on our channel check with CR Mixc (1209 HK), we expect that tenant sales across CR Mixc malls grew by double digits yoy in 9M2026, with same-store sales up by mid-single digits (1H2026: +10.2%) and luxury malls outperforming. We estimate growth eased gradually from a strong 1Q2026; in Sep 2026, overall retail sales was expected to grow by high single digits yoy while same-store sales were expected to be flat, below the 1.1% growth in national retail sales. National Day holiday sales improved, with total sales up by double digits and same-store sales up by mid-single digits, although luxury malls lagged.
- Approval of the third Mixc C-REIT supports CR Land’s capital recycling. On Nov 2, the CSRC approved the registration of the ChinaAMC CR Land Closed-end Commercial Real Estate Fund. According to the draft prospectus filed in April, the underlying assets are Nantong Mixc and Linyi Mixc One, with expected fundraising of about RMB 5.41bn. It follows the Qingdao Mixc consumption REIT listed in Mar 2024 and the Chengdu Mixc inter-bank REIT listed in Jul 2026, and management expects to exit about five malls a year during the 15th Five-Year Plan period.
- Maintain BUY on CR Land with a target price of HK$39.60. We expect retail sales at CR Mixc malls to grow by double digits in 2026. We see CR Land as an early mover in using REITs to recycle capital from mature malls. (Liu Jieqi/ Damon Shen)
Type of News | Explanation |
Channel Checks | Industry-wide or supply chain news with implications to a particular sector or company |
Corporate Action | Dividends, special dividends, stock splits, share buybacks, equity / bond financing, M&As, spin-offs and restructuring etc. |
Earnings | Quarterly earnings for US-listed companies. Semi-annual earnings for Hong Kong-listed companies |
Insider Dealing | Company insiders’ buying / selling of stocks and derivatives of the company |
Investor Action | Lead investor buying / selling including activist investor actions |
Investor Roadshow | Deal and non-deal roadshows, reverse roadshows (analyst days), and company meetings at investment conferences |
Legal / Regulatory | Lawsuits, legislature/regulation changes, other regulatory events |
Macro / Industry Data | Regular economic or industry data related to the sector or stock |
Sales / Products | Sales or product related news, such as monthly sales or new product launches |
Public Event | Public speeches and appearances by companies in the media or industry conferences |
Appendix - China Stock Model Portfolio (Nov 6 Reference)
Analyst
Elena Chen
elena.chen@uobkh.comAnalyst
Qi Wang, CFA
qi.wang@uobkh.comAnalyst
In collaboration with UOBKH Institutional Research
Disclosures and disclaimers
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


