分析員
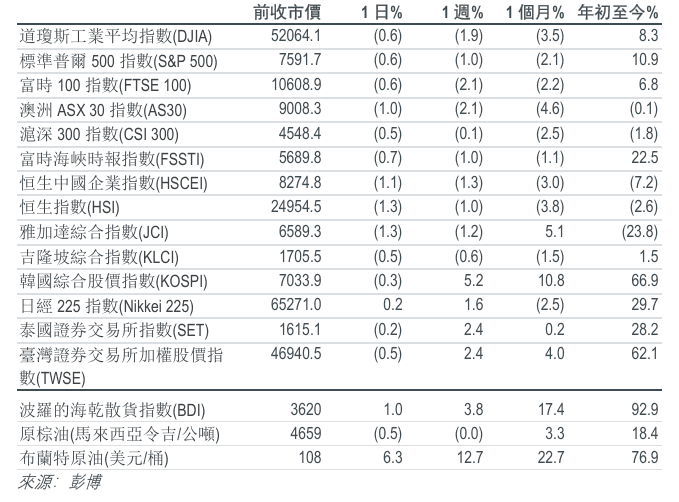
主要指數
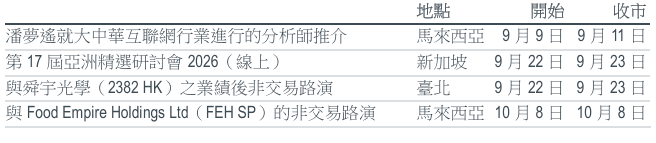
頭條新聞
行業更新 | 中國汽車
中國乘用車批發出貨量的按年跌幅由7月份的按年0.2%擴大至8月份的按年5.7%,但按月銷量增長仍維持在4.7%的正水平。當局重申了60天的付款期限政策。9月的新車發布日程比成都車展更加緊密。維持「與大市一致」評級。首選「買入」股份:比亞迪、吉利、寧德時代及敏實。首選「沽出」股份:理想汽車。
公司業績 | 新鴻基地產 (16 HK/買入/港幣116.7元/目標價:HK$143.80)
新鴻基地產2026財政年度基礎溢利按年增長4.6%至港幣228.5億元,大致符合市場預期。 融資成本下降以及出售帝景園所獲收益,抵銷了營業利潤3.6%的跌幅。 香港物業發展利潤率由2026財政年度上半年的7.6%提升至2026財政年度下半年的14.8%。 每股派息增長4.3%至港幣3.91元,而淨資產負債率則降至10.7%。 管理層將2027財政年度香港合約銷售目標定為港幣330億元。 我們預期物業及租賃市場的復甦將對2027財政年度的盈利構成支持。 維持「買入」評級;目標價:港幣143.8元。
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


