

Analyst
Analyst
Highlights
- The iEdge Singapore Next 50 Index tracks the performance of the next 50 largest companies listed on the SGX Mainboard. We screened the Next 50 component stocks for companies with attractive fundamentals:
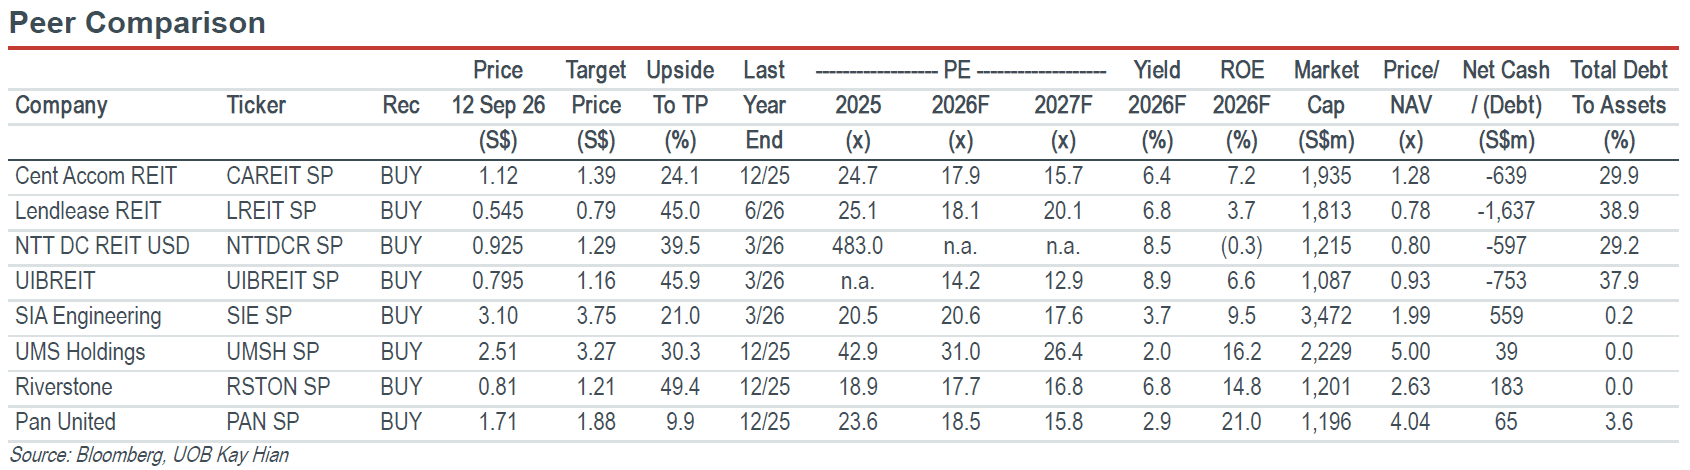
- Our top picks for S-REITs are CAREIT (Target: S$1.39), LREIT (Target: S$0.79), NTTDCR (Target: US$1.29) and UIBREIT (Target: S$1.16). Our preferred BUYs include SIE (Target: S$3.75) for the aviation sector and RSTON (Target: S$0.79) and UMSH (Target: S$3.27) for the technology sector. We also like construction play PAN (Target: S$1.88).
What’s New
- Next 50 Index spreads liquidity to a broader spectrum of companies. The iEdge Singapore Next 50 Index is a benchmark developed by the SGX to track the performance of the next 50 largest companies listed on the SGX Mainboard – those that fall just outside the top 30 by market capitalisation. The index emphasises tradability, liquidity, and replicability, making it suitable for investment products and benchmarking.
- Screening for the attractive gems with growth potential. We screened the Next 50 component stocks for companies with attractive fundamentals. Our preferred candidates for outperformance and accumulation are:
- Centurion Accommodation REIT (CAREIT SP/BUY/Target: S$1.39)
- Capacity expansion supports rental income growth. New blocks at Westlite Toh Guan and Westlite Mandai added 5,460 beds, expanding worker accommodation capacity by 25.7%, with further income contributions expected as occupancy ramps up. Westlite Ubi will add another 540 beds when its new block becomes operational, expected in 4Q27.
- Growing sponsor pipeline provides acquisition opportunities. Sponsor Centurion Corporation’s planned developments at Kranji Close and Lok Yang Way will add 12,000 beds, targeted for completion in 3Q28, creating potential acquisition opportunities once occupancy stabilised. CAREIT’s aggregate leverage of 29.9% and S$380m debt headroom, based on a 40% gearing threshold, provide capacity to pursue acquisitions.
- Regulatory capacity loss resulted in a shortage of PBWA beds. We forecast DPU to increase from 7.2 S cents in 2026 to 8.2 S cents in 2027, implying a DPU yield of 6.4% for 2026F and 7.3% for 2027F. Maintain BUY with target price of S$1.39 based on DDM (COE: 8.15%, terminal growth: 2.8%).
Highlights
- The iEdge Singapore Next 50 Index tracks the performance of the next 50 largest companies listed on the SGX Mainboard. We screened the Next 50 component stocks for companies with attractive fundamentals:
- Our top picks for S-REITs are CAREIT (Target: S$1.39), LREIT (Target: S$0.79), NTTDCR (Target: US$1.29) and UIBREIT (Target: S$1.16). Our preferred BUYs include SIE (Target: S$3.75) for the aviation sector and RSTON (Target: S$0.79) and UMSH (Target: S$3.27) for the technology sector. We also like construction play PAN (Target: S$1.88).
What’s New
- Next 50 Index spreads liquidity to a broader spectrum of companies. The iEdge Singapore Next 50 Index is a benchmark developed by the SGX to track the performance of the next 50 largest companies listed on the SGX Mainboard – those that fall just outside the top 30 by market capitalisation. The index emphasises tradability, liquidity, and replicability, making it suitable for investment products and benchmarking.
- Screening for the attractive gems with growth potential. We screened the Next 50 component stocks for companies with attractive fundamentals. Our preferred candidates for outperformance and accumulation are:
- Centurion Accommodation REIT (CAREIT SP/BUY/Target: S$1.39)
- Capacity expansion supports rental income growth. New blocks at Westlite Toh Guan and Westlite Mandai added 5,460 beds, expanding worker accommodation capacity by 25.7%, with further income contributions expected as occupancy ramps up. Westlite Ubi will add another 540 beds when its new block becomes operational, expected in 4Q27.
- Growing sponsor pipeline provides acquisition opportunities. Sponsor Centurion Corporation’s planned developments at Kranji Close and Lok Yang Way will add 12,000 beds, targeted for completion in 3Q28, creating potential acquisition opportunities once occupancy stabilised. CAREIT’s aggregate leverage of 29.9% and S$380m debt headroom, based on a 40% gearing threshold, provide capacity to pursue acquisitions.
- Regulatory capacity loss resulted in a shortage of PBWA beds. We forecast DPU to increase from 7.2 S cents in 2026 to 8.2 S cents in 2027, implying a DPU yield of 6.4% for 2026F and 7.3% for 2027F. Maintain BUY with target price of S$1.39 based on DDM (COE: 8.15%, terminal growth: 2.8%).
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.

