Analyst
Analyst
Key Calls
Karrie International (1050 HK)
- Karrie International’s (Karrie) 2QFY27 (Jul-Sep 26) revenue increased by about 45% yoy to HK$1.2b, primarily driven by a 48% yoy growth in server enclosure revenue (59% of total revenue), thanks to the continued shipments of AI server and rack products to the existing application-specific integrated circuit (ASIC) customer and Nvidia. Revenue from AI-related products accounted for 34% of its server enclosure revenue in 2QFY27 (1QFY27: 20%, FY26: 12%).
- Its existing ASIC customer has become the largest customer for its metal and plastic business in 2QFY27 after one year of mass production. For Nvidia, the company expects a more meaningful revenue contribution in 2HFY27. Meanwhile, Karrie is engaging with two new cloud service providers (CSP), with qualification completed for one CSP customer. Management expects a potential revenue contribution from one customer in 4QFY27 and the other in FY28.
- Management expects growth momentum to continue in 2HFY27 and expects 9MFY27 server-related revenue to exceed its full-year FY26 level. The company is confident about achieving a 1.5-2.0ppt gross margin expansion for the server enclosure segment in FY27 on a growing AI mix as well as operating leverage due to enhanced automation and better production efficiency.
- We see that shipments of server enclosure products for both the existing ASIC customer and Nvidia are on track. We believe growing industry demand for AI server enclosures and racks, as well as positive progress of customer qualification with two additional CSPs, support Karrie’s near- to medium-term growth momentum. We remain positive on Karrie’s ability to gain market share in AI server enclosures and racks, backed by its expertise in mechanical design engineering, hard tooling and mass production.
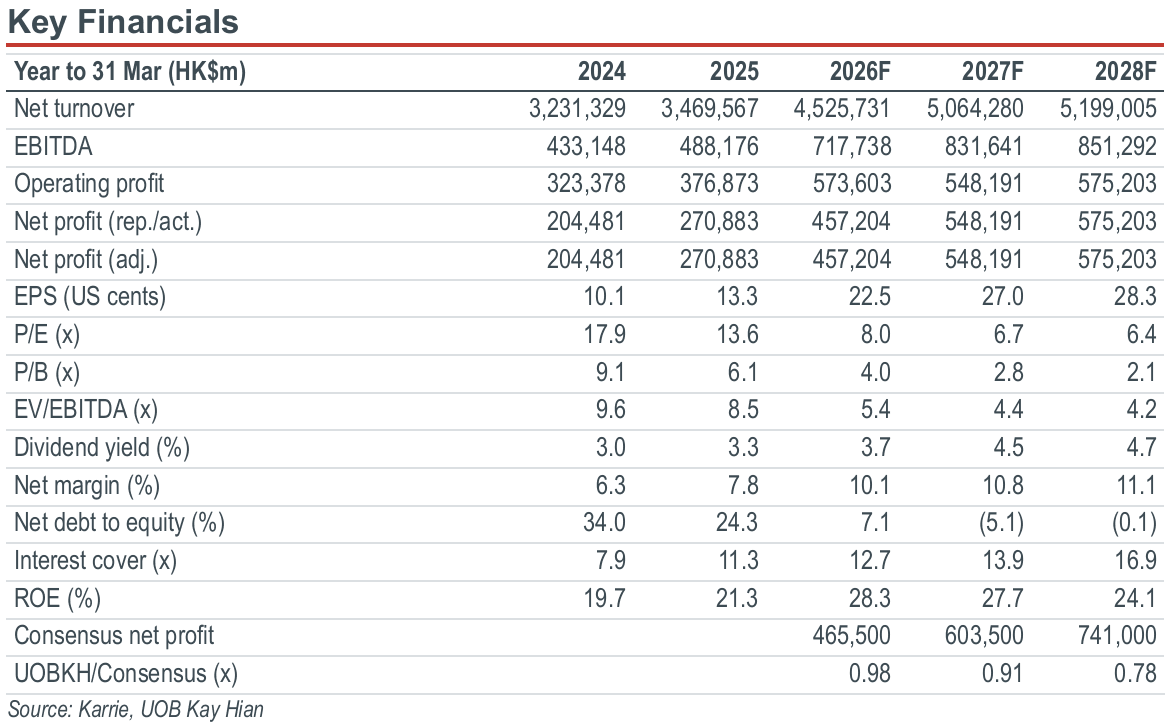
- Its share price has corrected by about 40% from its previous peak in June, which was largely related to the FY26 results miss on shipment delays due to geopolitical conflicts and weakening market sentiment on AI-related stocks. We believe its current valuation at 8.0x FY27F PE and a 3.7% FY27F dividend yield are attractive and see its 1HFY27 results to be announced in end-Nov 26 as a near-term catalyst.
Key Calls
Karrie International (1050 HK)
- Karrie International’s (Karrie) 2QFY27 (Jul-Sep 26) revenue increased by about 45% yoy to HK$1.2b, primarily driven by a 48% yoy growth in server enclosure revenue (59% of total revenue), thanks to the continued shipments of AI server and rack products to the existing application-specific integrated circuit (ASIC) customer and Nvidia. Revenue from AI-related products accounted for 34% of its server enclosure revenue in 2QFY27 (1QFY27: 20%, FY26: 12%).
- Its existing ASIC customer has become the largest customer for its metal and plastic business in 2QFY27 after one year of mass production. For Nvidia, the company expects a more meaningful revenue contribution in 2HFY27. Meanwhile, Karrie is engaging with two new cloud service providers (CSP), with qualification completed for one CSP customer. Management expects a potential revenue contribution from one customer in 4QFY27 and the other in FY28.
- Management expects growth momentum to continue in 2HFY27 and expects 9MFY27 server-related revenue to exceed its full-year FY26 level. The company is confident about achieving a 1.5-2.0ppt gross margin expansion for the server enclosure segment in FY27 on a growing AI mix as well as operating leverage due to enhanced automation and better production efficiency.
- We see that shipments of server enclosure products for both the existing ASIC customer and Nvidia are on track. We believe growing industry demand for AI server enclosures and racks, as well as positive progress of customer qualification with two additional CSPs, support Karrie’s near- to medium-term growth momentum. We remain positive on Karrie’s ability to gain market share in AI server enclosures and racks, backed by its expertise in mechanical design engineering, hard tooling and mass production.
- Its share price has corrected by about 40% from its previous peak in June, which was largely related to the FY26 results miss on shipment delays due to geopolitical conflicts and weakening market sentiment on AI-related stocks. We believe its current valuation at 8.0x FY27F PE and a 3.7% FY27F dividend yield are attractive and see its 1HFY27 results to be announced in end-Nov 26 as a near-term catalyst.
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

12 Oct 2026
Xiaomi Corp (1810 HK): SKYNOAD’s Locked Orders Surpass 70,000 Units

21 Oct 2026
Lenovo Group (992 HK): 2QFY27 Results Preview: ISG To Register Another Quarter Of Strong Growth

29 Sept 2026

