

Company Coverage
MISC (MISC MK): Tanker Boom Party Is Still On
BUY (Maintained)
Current price:
Target price:
Upside:
RM7.81
RM9.50
+12.0%
Analyst
Highlights
- Share price has adequately retraced to reflect M&A event risks. Following after its strong 2Q26 results, we still like the stock’s long-term strategy. However, we had previously expected share price to underperform in 2H26 relative to 1H26. Since then, share price has retraced by about 8%.
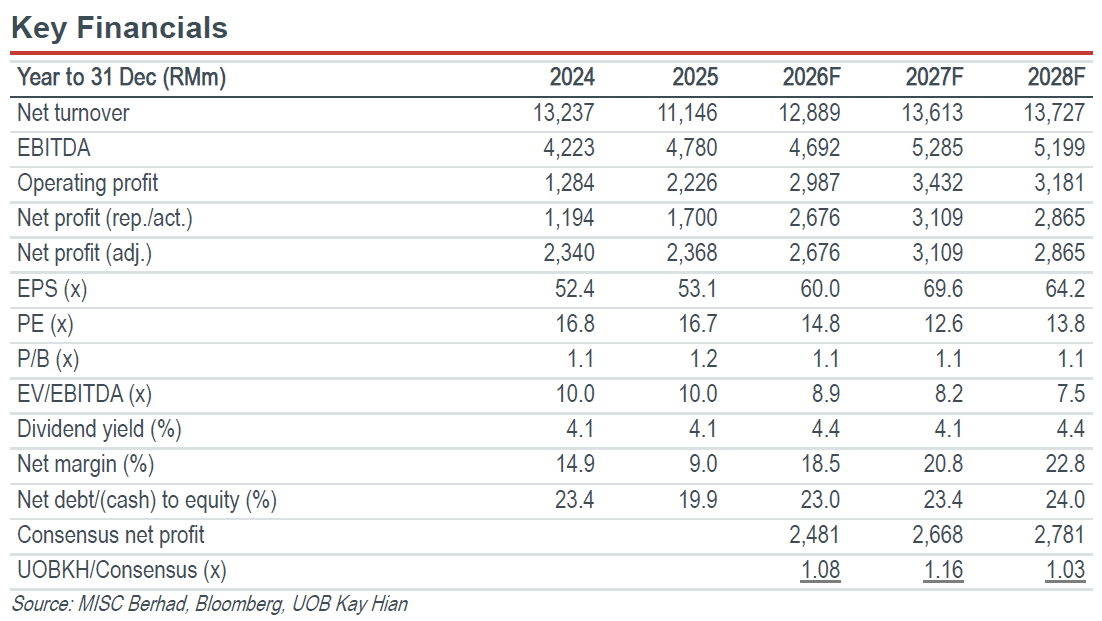
- The tanker boom supercycle may be stronger this time vs 1H26. Unlike the past, tankers are now increasingly being considered as strategic assets for energy security. Considering that MISC is the only local listed proxy, we see trading opportunities for investors to capitalise on the tanker boom. We also assume that there is still upside to consensus near-term earnings forecast for the petroleum division. Maintain BUY, with a target price of RM9.50.
Analysis
- VLCC spot rates recently hit US$1m. The surge in tanker rates is due to inefficiencies arising from the effective closure of the Strait of Hormuz since the onset of the US-Iran war. The Middle East situation has been increasingly volatile, including severe US-Iran kinetic re-engagements in the Straits, alongside Houthi forces recently closing in on the Bab el-Mandeb Strait, which caused a major prolonged disruption of Saudi oil flows to the Red Sea. These decoupled VLCC earnings and pushed rates to all-time highs. For the week ending 4 Sep 26, average VLCC daily spot rates closed at US$376,871, but several reports cited VLCC rates for Gulf-China routes were over US$800,000.
- 2026 tanker boom exceeded only once, by 2004-2008 supercycle. That supercycle was a demand-driven multi-year boom as China’s economy accelerated after it joined the World Trade Organisation. The 2026 cycle is being driven by supply-side, factor-specific disruptions caused by vessel supply constraints, global maritime chokepoints, and sanctions, which have created inefficiencies and extended routes, boosting tonne-miles even as demand declines.
Highlights
- Share price has adequately retraced to reflect M&A event risks. Following after its strong 2Q26 results, we still like the stock’s long-term strategy. However, we had previously expected share price to underperform in 2H26 relative to 1H26. Since then, share price has retraced by about 8%.
- The tanker boom supercycle may be stronger this time vs 1H26. Unlike the past, tankers are now increasingly being considered as strategic assets for energy security. Considering that MISC is the only local listed proxy, we see trading opportunities for investors to capitalise on the tanker boom. We also assume that there is still upside to consensus near-term earnings forecast for the petroleum division. Maintain BUY, with a target price of RM9.50.
Analysis
- VLCC spot rates recently hit US$1m. The surge in tanker rates is due to inefficiencies arising from the effective closure of the Strait of Hormuz since the onset of the US-Iran war. The Middle East situation has been increasingly volatile, including severe US-Iran kinetic re-engagements in the Straits, alongside Houthi forces recently closing in on the Bab el-Mandeb Strait, which caused a major prolonged disruption of Saudi oil flows to the Red Sea. These decoupled VLCC earnings and pushed rates to all-time highs. For the week ending 4 Sep 26, average VLCC daily spot rates closed at US$376,871, but several reports cited VLCC rates for Gulf-China routes were over US$800,000.
- 2026 tanker boom exceeded only once, by 2004-2008 supercycle. That supercycle was a demand-driven multi-year boom as China’s economy accelerated after it joined the World Trade Organisation. The 2026 cycle is being driven by supply-side, factor-specific disruptions caused by vessel supply constraints, global maritime chokepoints, and sanctions, which have created inefficiencies and extended routes, boosting tonne-miles even as demand declines.
BUY (Maintained)
Current price:
Target price:
Upside:
RM7.81
RM9.50
+12.0%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
