

Company Coverage
Adaro Andalan Indonesia (AADI IJ): Two Tailwinds In 2H26
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Rp12,225
Rp14,300
+17.2%
Rp10,900
Analyst
Analyst
Highlights
- Continued deliveries in Kalimantan. Deliveries uninterrupted as of 6 Sep 26, while the disruption sits upstream in Central Kalimantan.
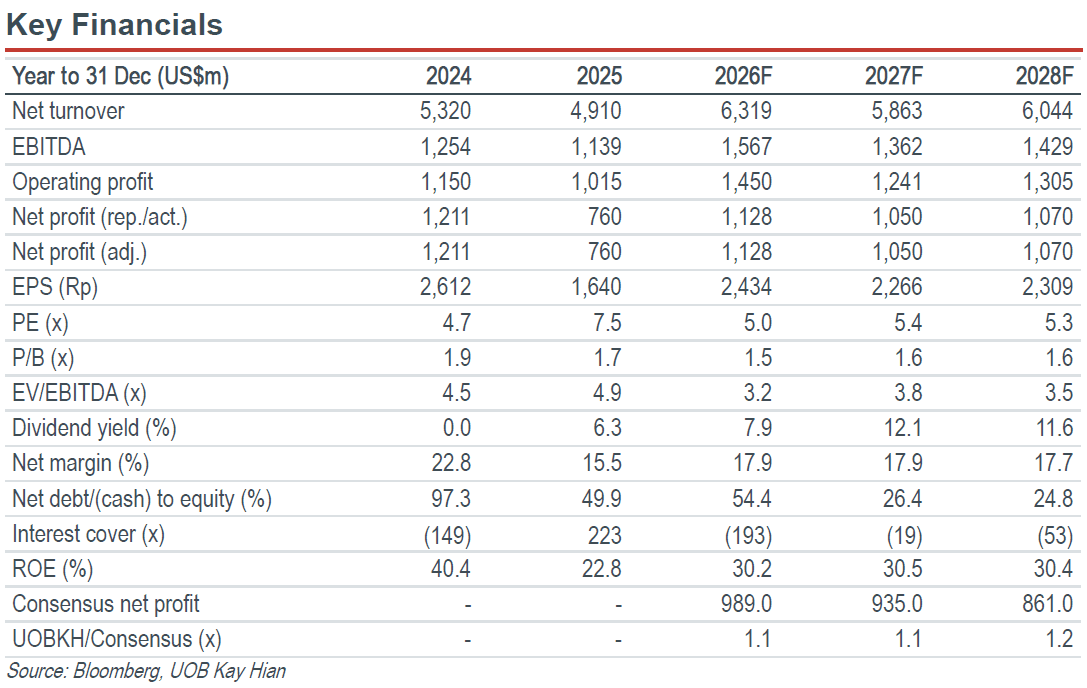
- Kaltara power contributes from 2H26. The 1GW captive plant is expected to add around US$60m to 2026 rental income.
- Maintain BUY with a higher target price of Rp14,300 from Rp10,900, based on 6.3x 2027F PE, reflecting Alamtri Resources Indonesia (ADRO)’s five-year average PE.
Analysis
- AADI's mines sit in South Kalimantan, away from the constrained upstream Barito. Adaro Andalan Indonesia (AADI)'s coal deliveries remain uninterrupted as of 6 Sep 26. Its major producing assets and the Adaro Indonesia (AI) coal mine are all in South Kalimantan and feed Kelanis via AADI's own 80km hauling road rather than by river. AADI only enters the river at the mid-Barito loading station and controls dredging on the stretch below through Sarana Daya Mandiri.
- Coal prices to stay elevated as supply disruption meets seasonal demand. Newcastle coal price is up 37.7% since the US-Iran conflict began in Feb 26, while seasonal demand and El Niño supply disruption should keep prices supported into 2H26. On the supply side, El Niño-driven low water levels have made parts of the upper Barito in Central Kalimantan unnavigable, with force majeure already declared by some shippers and Apindo estimating around 3.9 mt per month of barging at risk. On the demand side, the July to October window typically prices at the upper end of the range as Northern Hemisphere cooling demand overlaps with restocking ahead of winter, and this year the same El Niño is cutting Indian hydro output and monsoon replenishment, which pulls India back into the seaborne market.
- Kaltara power adds earnings. AADI started earning revenue in mid-26 by renting out its 1GW coal power plant to power Alamtri Minerals Indonesia's (ADMR) new aluminum smelter. The demand side is running ahead of plan. All 72 potlines at Kalimantan Aluminum Industry (KAI) are now operational, with 2026 targets of around 370,000 tonnes for production and 340,000 tonnes for sales and full capacity of around 500,000 tonnes next year. 2Q26 showed rental earnings of US$22m with potential to contribute US$60m in rental income in 2026, and a fuller contribution in 2027 of around US$80m.
Highlights
- Continued deliveries in Kalimantan. Deliveries uninterrupted as of 6 Sep 26, while the disruption sits upstream in Central Kalimantan.
- Kaltara power contributes from 2H26. The 1GW captive plant is expected to add around US$60m to 2026 rental income.
- Maintain BUY with a higher target price of Rp14,300 from Rp10,900, based on 6.3x 2027F PE, reflecting Alamtri Resources Indonesia (ADRO)’s five-year average PE.
Analysis
- AADI's mines sit in South Kalimantan, away from the constrained upstream Barito. Adaro Andalan Indonesia (AADI)'s coal deliveries remain uninterrupted as of 6 Sep 26. Its major producing assets and the Adaro Indonesia (AI) coal mine are all in South Kalimantan and feed Kelanis via AADI's own 80km hauling road rather than by river. AADI only enters the river at the mid-Barito loading station and controls dredging on the stretch below through Sarana Daya Mandiri.
- Coal prices to stay elevated as supply disruption meets seasonal demand. Newcastle coal price is up 37.7% since the US-Iran conflict began in Feb 26, while seasonal demand and El Niño supply disruption should keep prices supported into 2H26. On the supply side, El Niño-driven low water levels have made parts of the upper Barito in Central Kalimantan unnavigable, with force majeure already declared by some shippers and Apindo estimating around 3.9 mt per month of barging at risk. On the demand side, the July to October window typically prices at the upper end of the range as Northern Hemisphere cooling demand overlaps with restocking ahead of winter, and this year the same El Niño is cutting Indian hydro output and monsoon replenishment, which pulls India back into the seaborne market.
- Kaltara power adds earnings. AADI started earning revenue in mid-26 by renting out its 1GW coal power plant to power Alamtri Minerals Indonesia's (ADMR) new aluminum smelter. The demand side is running ahead of plan. All 72 potlines at Kalimantan Aluminum Industry (KAI) are now operational, with 2026 targets of around 370,000 tonnes for production and 340,000 tonnes for sales and full capacity of around 500,000 tonnes next year. 2Q26 showed rental earnings of US$22m with potential to contribute US$60m in rental income in 2026, and a fuller contribution in 2027 of around US$80m.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Rp12,225
Rp14,300
+17.2%
Rp10,900
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
