

Company Coverage
WuXi AppTec (2359 HK): 9M26: Results Beat; Further Raises 2026 Guidance
BUY (Maintained)
Current price:
Target price:
Upside:
HK$185.60
HK$220.00
18.5%
Analyst
Analyst
Highlights
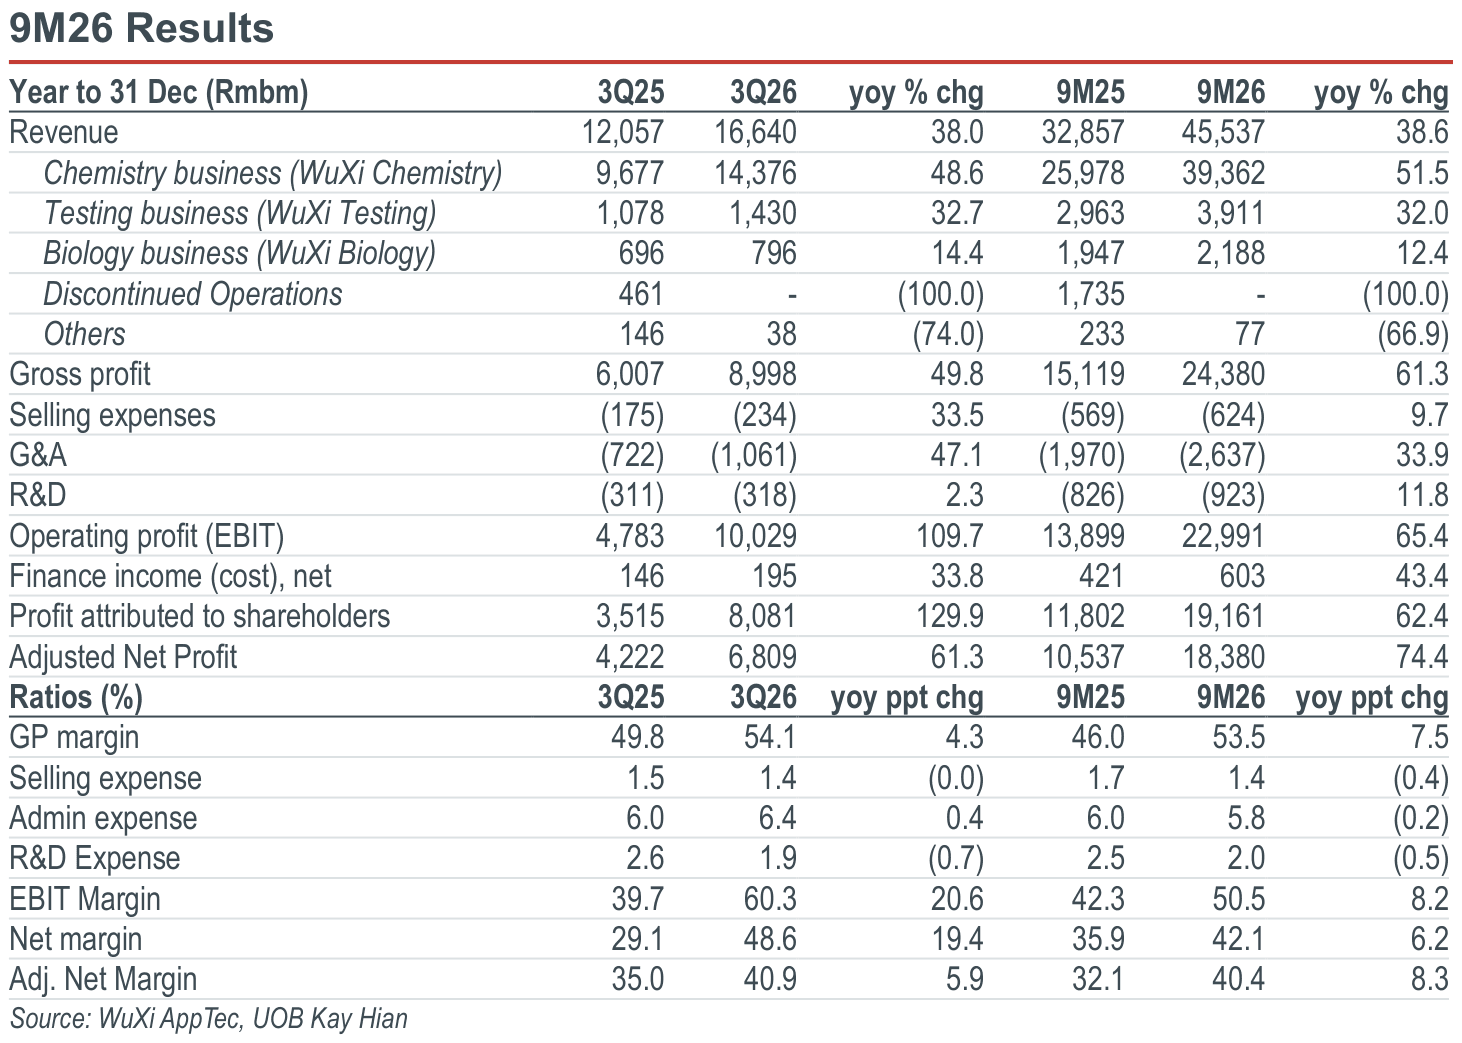
- WuXi AppTec delivered strong 9M26 results, with total revenue and adjusted net profit expanding 38.6% yoy and 74.4% yoy respectively, beating market estimates and its growth guidance.
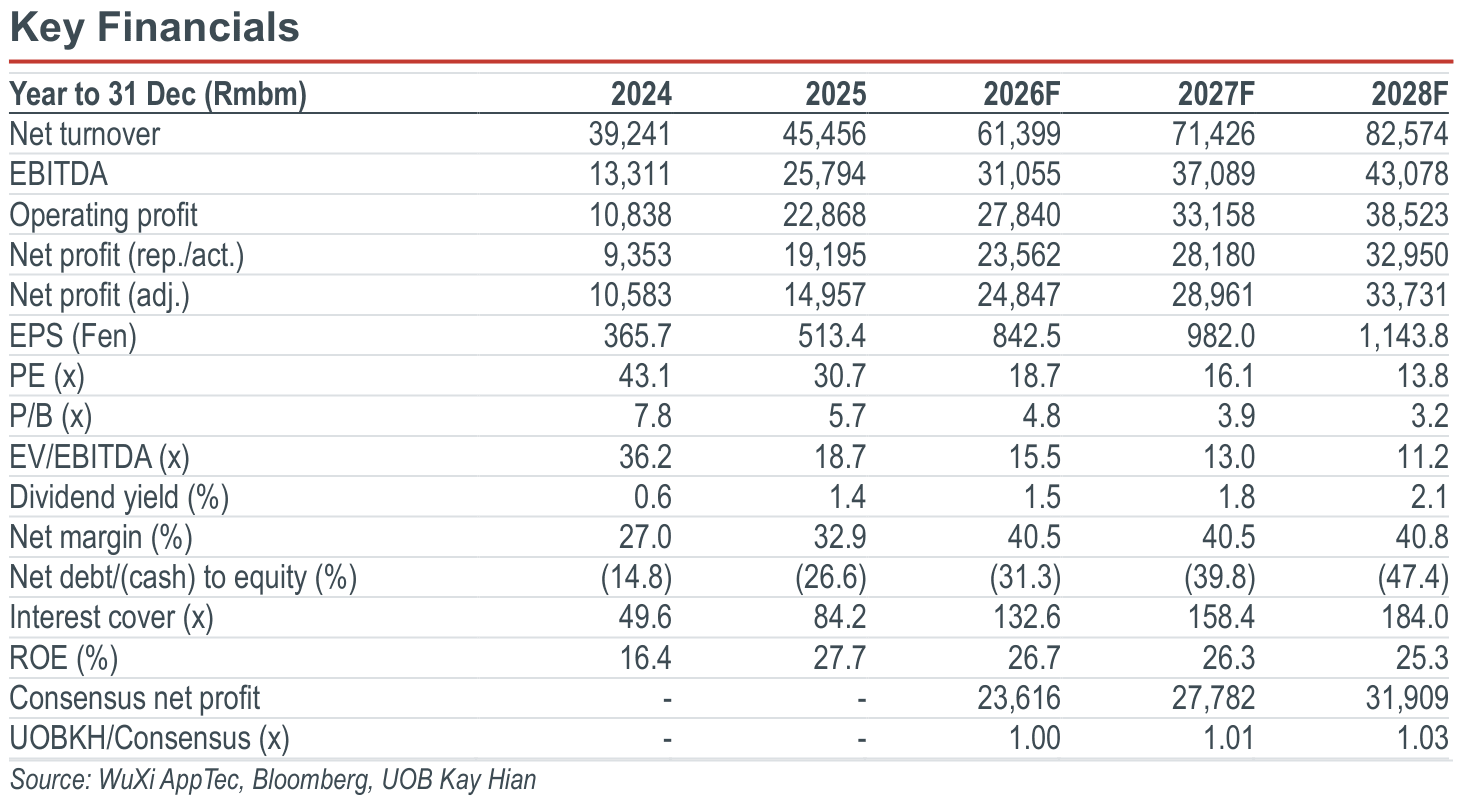
- Its backlog for continuing operations increased 36.4% yoy to Rmb76.7b at end-Sep 26. The company has raised its 2026 revenue target further from Rmb58.5b-60.5b to Rmb61.0b-61.9b, with continuing operations revenue growing 40-42% yoy (vs 35-39% previously).
- Maintain BUY and target price of HK$220.00.
Analysis
- Strong 9M26 results beat. WuXi AppTec reported much stronger-than-expected 9M26 results, with total revenue up 38.6% yoy to Rmb45.5b and revenue from continuing operations up 46.3% yoy, well ahead of its original 2026 growth guidance. Adjusted net earnings (excluding share-based compensation expenses, fair value gains/losses from investments and forex-related gains/losses) soared 74.4% yoy to Rmb18.4b in 9M26.
Highlights
- WuXi AppTec delivered strong 9M26 results, with total revenue and adjusted net profit expanding 38.6% yoy and 74.4% yoy respectively, beating market estimates and its growth guidance.
- Its backlog for continuing operations increased 36.4% yoy to Rmb76.7b at end-Sep 26. The company has raised its 2026 revenue target further from Rmb58.5b-60.5b to Rmb61.0b-61.9b, with continuing operations revenue growing 40-42% yoy (vs 35-39% previously).
- Maintain BUY and target price of HK$220.00.
Analysis
- Strong 9M26 results beat. WuXi AppTec reported much stronger-than-expected 9M26 results, with total revenue up 38.6% yoy to Rmb45.5b and revenue from continuing operations up 46.3% yoy, well ahead of its original 2026 growth guidance. Adjusted net earnings (excluding share-based compensation expenses, fair value gains/losses from investments and forex-related gains/losses) soared 74.4% yoy to Rmb18.4b in 9M26.
BUY (Maintained)
Current price:
Target price:
Upside:
HK$185.60
HK$220.00
18.5%
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

23 Oct 2026
Han’s Laser (002008 CH): 3Q26: Strong Beat In IT Business

23 Oct 2026
Ping An Healthcare and Technology Company (1833 HK): 3Q26: Revenue Decline Deepens; Low-Margin Business Run-off To Weigh On Revenue Until Early-27

27 Oct 2026
EVE Energy (300014 CH): 3Q26: Earnings Up 60% yoy/4.5% qoq, Missing Estimates; Cut Target Price To Rmb57.00
Our latest research
28 Oct 2026
TA: Swire Properties (1972 HK) / CK Hutchison (0001 HK)

28 Oct 2026
Huizhou Desay SV (002920 CH): 3Q26: Revenue Growth Accelerates To 24%, But Earnings Miss On Subsidy Cuts, Credit Provisions, Associates’ Losses, And Tax Hikes

28 Oct 2026